
Company: Polymatech Electronics Limited
CIN: U32107TN2007PLC063706
ISIN: INE0OLN01029
Face Value: ₹2 per share after stock split
Status: Active Unlisted Public Company
Registered Office: Plot OZ-13, SIPCOT Hi-Tech SEZ, Oragadam, Kancheepuram, Tamil Nadu
Industry: Semiconductors / Opto-Semiconductors / Electronics
Promoters: Eswara Rao Nandam, Uma Nandam & family
Latest independently verified audited financial year: FY2024-25
Official Company Website: Polymatech Electronics
Investor Relations: Polymatech Investor Relations
Executive Summary
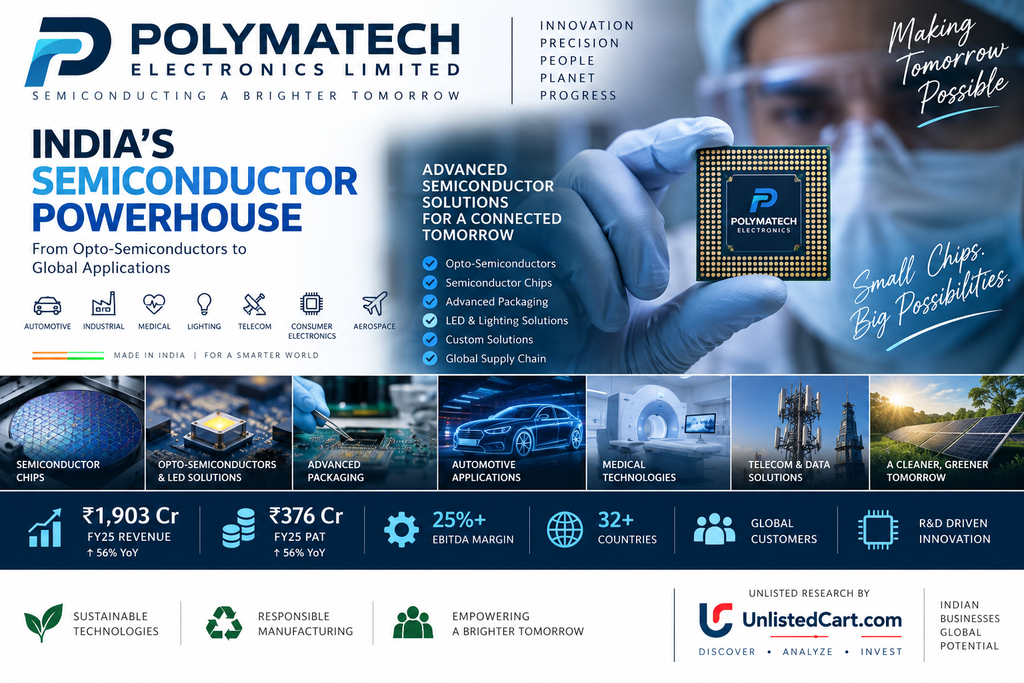
Polymatech Electronics Limited is an Indian semiconductor and opto-semiconductor company headquartered in Oragadam, Tamil Nadu.
The company was originally incorporated in 2007 as a subsidiary of a Japanese entity and was subsequently acquired by the current promoters. It became a public limited company in 2023. The company’s business is focused on semiconductor products, opto-semiconductor technologies, chip packaging and related applications.
Polymatech has positioned itself as an Indian semiconductor manufacturer serving applications across areas such as:
- Automotive
- Industrial electronics
- Medical applications
- Lighting
- Data transmission
- Consumer electronics
- Telecom
- Aerospace and other specialised applications
The company’s official website describes its business as being focused on opto-semiconductor innovation, with manufacturing facilities in India and international expansion.
The financial growth over the last few years has been substantial.
FY2022 → FY2025 Revenue
₹126 Cr → ₹1,903 Cr
FY2022 → FY2025 PAT
₹35 Cr → ₹376 Cr
FY2025 consolidated revenue increased approximately 56%, while PAT increased approximately 56%.
The company also has a relatively strong balance sheet.
FY2025 consolidated:
- Revenue: ₹1,902.90 Cr
- Total income: ₹1,912.13 Cr
- PBT: ₹444.54 Cr
- PAT: ₹375.59 Cr
- PAT attributable to owners: ₹361.37 Cr
- Equity: approximately ₹1,156 Cr
- Cash & cash equivalents: ₹392.27 Cr
- Total borrowings: approximately ₹53.62 Cr
- Debt-equity: approximately 0.04x on the current unlisted-market data basis.
At an indicative unlisted price around ₹48/share, the current market capitalisation is approximately ₹1,900 Cr.
That translates to roughly:
5.1x FY2025 earnings
and around:
1.5–1.7x book value
depending on the exact reference price and financial-data convention.
This valuation is not excessive for a rapidly growing semiconductor business, but the investment case depends heavily on whether Polymatech can sustain its extraordinary growth and execute its planned capacity expansion.
Company Background
Polymatech Electronics was incorporated on 29 May 2007 as Polymatech Electronics Private Limited.
According to the company’s DRHP, it was initially a foreign-company subsidiary and was subsequently taken over by the current promoters through a share purchase agreement dated December 2016.
The company was converted into a public limited company in 2023 and renamed Polymatech Electronics Limited.
The company’s registered manufacturing location is at:
SIPCOT Hi-Tech SEZ, Oragadam, Kancheepuram, Tamil Nadu.
The company is now controlled by the Nandam promoter family.
What Does Polymatech Do?
Polymatech operates in the semiconductor and opto-semiconductor ecosystem.
Its business broadly covers:
1. Opto-Semiconductors
Opto-semiconductors convert electrical signals into optical signals or vice versa and are used in:
- Lighting
- Communication
- Sensors
- Medical equipment
- Industrial applications
- Consumer electronics
2. Semiconductor Chips
The company manufactures semiconductor chips and related products for specialised applications.
3. Semiconductor Packaging
Packaging is a critical part of semiconductor manufacturing.
It involves assembling semiconductor dies into packages that protect the chip and enable it to connect with the broader electronic system.
Polymatech’s positioning in packaging and semiconductor manufacturing provides exposure to the growing OSAT / semiconductor assembly ecosystem.
4. LED & Lighting Solutions
The company has developed semiconductor-based lighting technologies for different applications.
5. Specialised Applications
The company has highlighted applications including:
- Medical
- Data transmission
- Sanitisation
- Photosynthesis
- Aqua lighting
- Industrial lighting
The company’s DRHP describes its product development across specialised applications.
Technology Positioning
Polymatech’s official website describes the company as a manufacturer of advanced opto-semiconductor solutions and highlights compound semiconductor technology as an important part of its strategy.
The company also highlights:
- 17+ years of technological experience
- 25+ strategic alliances
- 50+ global partnerships
- Multiple industry accolades
- Large-scale semiconductor manufacturing capabilities
These are company-reported figures and should be independently verified during detailed due diligence.
Customer / Industry Exposure
Polymatech’s current website displays a very broad list of global technology and industrial names, including companies such as:
- AMD
- Apple
- Boeing
- Broadcom
- Cisco
- Denso
- Foxconn
- GE
- Honeywell
- HP
- IBM
- Infineon
- Intel
- Micron
- Nokia
- NXP
- Panasonic
- Philips
- Qualcomm
- Samsung
- Sony
- SpaceX
- TSMC
- Tesla
This is presented by the company as its broader group/customer ecosystem; investors should not automatically interpret every displayed logo as a current direct customer of Polymatech Electronics Limited.
Why Semiconductor Manufacturing Matters
India imports a significant proportion of its semiconductor requirements.
The government has therefore been attempting to build a domestic semiconductor ecosystem covering:
- Chip design
- Wafer fabrication
- Semiconductor packaging
- Testing
- Electronics manufacturing
- Compound semiconductors
Polymatech’s positioning within semiconductor manufacturing gives it exposure to this structural theme.
The company has specifically positioned itself around Atma Nirbhar Bharat and domestic semiconductor capability.
Financial Performance
The financial transformation has been dramatic.
| Particular | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|
| Revenue | ₹126 Cr | ₹649 Cr | ₹1,221 Cr | ₹1,903 Cr |
| EBITDA | ₹39.8 Cr | ₹184 Cr | ₹304 Cr | ₹487 Cr |
| PBT | ₹35 Cr | ₹167 Cr | ₹270 Cr | ₹445 Cr |
| PAT | ₹35 Cr | ₹167 Cr | ₹240 Cr | ₹376 Cr |
FY2025 figures are consolidated; FY2023 and FY2024 comparability should be considered carefully because earlier financial presentations included standalone figures.
Revenue CAGR
From FY2022 revenue of ₹126 Cr to FY2025 revenue of ₹1,903 Cr represents an extraordinary increase.
This is one of the strongest aspects of the Polymatech investment story.
FY2025 Financial Performance
Revenue
Revenue from operations:
₹1,902.90 Cr
Other income:
₹9.23 Cr
Total income:
₹1,912.13 Cr
PBT
₹444.54 Cr
PAT
₹375.59 Cr
PAT attributable to owners
₹361.37 Cr
EPS
Approximately:
₹9.07/share
on the post-split share structure.
EBITDA
FY2025 EBITDA was approximately:
₹487 Cr
This implies an EBITDA margin of approximately:
25.6%
This is a strong operating margin for a manufacturing company and demonstrates the economic attractiveness of the business if the current profitability can be sustained.
Balance Sheet
FY2025 consolidated balance sheet:
| Particular | FY2025 |
|---|---|
| PPE | ₹407.54 Cr |
| Capital Work-in-Progress | ₹201.88 Cr |
| Goodwill | ₹5.66 Cr |
| Investments | ₹6.78 Cr |
| Inventory | ₹731.58 Cr |
| Trade Receivables | ₹1,252.16 Cr |
| Cash & Cash Equivalents | ₹392.27 Cr |
| Total Assets | ₹3,081.46 Cr |
| Equity | ~₹1,156 Cr |
| Borrowings | ~₹53.62 Cr |
Cash Position
Cash and cash equivalents were approximately:
₹392 Cr
This is a significant liquidity cushion.
However, investors should not simply treat all cash as surplus cash because semiconductor manufacturing requires substantial working capital and ongoing capital expenditure.
Working Capital
One area that requires close attention is working capital.
FY2025:
Inventory: ~₹732 Cr
Trade receivables: ~₹1,252 Cr
Together, these represented nearly ₹2,000 Cr.
This is extremely significant relative to annual revenue.
Therefore, although the company reports high profitability, investors should closely monitor:
- Receivable collection
- Inventory days
- Customer advances
- Supplier credit
- Operating cash flow
- Working-capital funding
The company’s current ratio was around 1.45x.
Debt Position
The company’s debt position is relatively comfortable.
FY2025 non-current borrowings were approximately:
₹53.42 Cr
Current borrowings:
₹0.21 Cr
Total borrowings:
~₹53.6 Cr
Against equity of more than ₹1,150 Cr, this represents low leverage.
Unlisted-market data places debt/equity around:
0.04x
This is one of the company’s strongest financial characteristics.
Capital Expenditure
Semiconductor manufacturing is highly capital intensive.
Polymatech had:
Capital Work-in-Progress: ~₹201.9 Cr
at March 2025.
This indicates that the company was actively investing in capacity and manufacturing infrastructure.
Future expansion therefore remains an important part of the investment thesis.
IPO History
This is one of the most important aspects of the company.
Polymatech filed a Draft Red Herring Prospectus with SEBI on 29 September 2023.
The proposed IPO was structured as a:
Fresh issue of up to ₹750 Cr
with no Offer for Sale component in the original DRHP.
The stated purpose included funding machinery and expansion of its manufacturing facilities.
SEBI’s official filing confirms the DRHP.
Important IPO Caveat
A DRHP is not the same as an approved IPO or confirmed listing date.
The original ₹750 Cr IPO should therefore be treated as a historical IPO proposal unless and until the company/SEBI confirms an updated issue process.
I would not market Polymatech as “IPO coming soon” solely based on the 2023 DRHP.
Current IPO / Listing Status
As of the latest information reviewed:
Polymatech remains unlisted.
Current unlisted-market sources continue to quote the shares privately.
The company maintains an investor-relations section on its website, but a confirmed current IPO launch date was not identified in the sources reviewed.
Recent Corporate / Legal Development
An important development occurred in 2026.
A petition filed before the Chennai NCLT by Vencap Capital Advisory Pvt Ltd under Section 9 of the IBC was withdrawn after the parties reported settlement.
The NCLT order records a settled amount of:
₹98.25 Cr principal
plus
₹58.95 Cr interest
for a total stated default amount of:
₹157.20 Cr
The petition was subsequently disposed of as withdrawn.
This is important for investors because it demonstrates that Polymatech has had a material creditor dispute.
At the same time, the matter being settled and withdrawn is materially different from an insolvency admission or CIRP proceeding.
This should still be investigated through the company’s latest legal disclosures and financial statements.
Current Unlisted Share Price
There is significant price variation between unlisted-market intermediaries.
Planify
Approximately:
₹47.85/share
as of 12 September 2026.
52-week range:
₹45–₹87
UnlistedZone
Approximately:
₹48/share
as of 10 September 2026.
Market cap:
~₹1,913 Cr
Neoma Capital
Approximately:
₹47.52/share
as of 12 September 2026.
Unlisted Nivesh
Approximately:
₹53/share
as of 12 September 2026.
These are indicative private-market references, not NSE/BSE prices.
Share Capital & Stock Split
Polymatech underwent a face-value split.
The current face value is:
₹2/share
and current unlisted-market sources report approximately:
39.84 crore shares
outstanding.
This is important because older reports may show:
- ₹10 face value
- ~7.97 crore shares
while newer reports show:
- ₹2 face value
- ~39.84 crore shares
The economic value is unchanged by the split.
Investors should always use the current post-split capital structure when calculating valuation.
Market Capitalisation
At approximately ₹48/share:
39.84 Cr shares × ₹48
= approximately:
₹1,913 Cr market capitalisation
This is consistent with current unlisted-market references.
Valuation
At ₹48/share:
Market Capitalisation
~₹1,913 Cr
FY2025 PAT
~₹375.6 Cr
P/E
Approximately:
5.1x
This is a relatively low earnings multiple for a semiconductor business with the company’s historical growth rate.
However, the critical question is whether FY2025 earnings represent a sustainable base.
Price-to-Book
Current unlisted-market sources report book value around:
₹31.97/share
At ₹48:
P/B ≈ 1.5x
Therefore, the stock is trading at a meaningful premium to book value, but not an extreme multiple given the semiconductor theme and profitability.
Valuation Sensitivity
Using FY2025 PAT of approximately ₹375.6 Cr and 39.84 Cr shares:
Approximate EPS:
₹9.43
| P/E | Indicative Share Value |
|---|---|
| 5x | ₹47 |
| 7x | ₹66 |
| 10x | ₹94 |
| 12x | ₹113 |
| 15x | ₹141 |
| 20x | ₹189 |
This is a valuation sensitivity analysis, not a target price.
The current ₹48 area effectively values the company at approximately 5x FY2025 earnings.
Why the Valuation Could Be Attractive
There are several reasons investors may find the current valuation interesting.
1. Strong Historical Growth
Revenue grew from approximately ₹126 Cr in FY2022 to ₹1,903 Cr in FY2025.
2. Strong Profitability
FY2025 PAT was approximately ₹376 Cr.
3. High EBITDA Margin
EBITDA margin was approximately 25.6%.
4. Low Debt
Debt/equity around 0.04x.
5. Semiconductor Theme
India’s semiconductor ecosystem is receiving significant policy and capital support.
6. Capacity Expansion
The company has substantial capital work-in-progress.
7. IPO Optionality
A historical ₹750 Cr DRHP demonstrates that the company has previously pursued a public-market listing route.
Key Growth Drivers
Semiconductor Import Substitution
India’s dependence on imported semiconductor components creates a large potential domestic market.
Government Semiconductor Push
The national semiconductor ecosystem can provide opportunities for domestic manufacturers.
Automotive Electronics
Modern vehicles require increasing semiconductor content.
Industrial Electronics
Industrial automation and electronics are increasing semiconductor demand.
Telecom & Data
5G, optical communication and data infrastructure require specialised semiconductor components.
Medical Electronics
Medical equipment is becoming increasingly electronics-intensive.
Export Growth
International customers can provide significant addressable-market expansion.
New Product Development
Management has indicated ambitions to introduce new products and enter additional semiconductor applications.
Competitive Advantages
First-Mover Positioning
Polymatech has developed semiconductor manufacturing capabilities in India at a time when domestic semiconductor capacity is still developing.
Manufacturing Infrastructure
The Oragadam facility provides an established industrial base.
Technology
The company has developed proprietary processes and technologies around opto-semiconductors.
R&D
The company highlights large-scale R&D and product development capabilities.
Low Financial Leverage
Low debt gives management greater flexibility to fund expansion.
Promoter Ownership
Promoters continue to hold a substantial stake.
Current unlisted-market data indicates:
- Eswara Rao Nandam: ~41.57%
- Uma Nandam: ~31.81%
- Others: ~26.62%
Major Risks
1. Semiconductor Execution Risk
Semiconductor manufacturing is technologically complex.
Capacity expansion does not automatically translate into revenue and profit.
2. Customer Concentration
Large semiconductor customers can have significant negotiating power.
3. Working Capital
Receivables and inventory are substantial.
This is one of the most important financial risks.
4. Technology Obsolescence
Semiconductor technology changes rapidly.
Continuous R&D investment is required.
5. Capital Intensity
The business requires continuous investment in:
- Machinery
- Clean-room facilities
- Testing
- Packaging
- R&D
- Capacity expansion
6. IPO Uncertainty
The 2023 DRHP does not guarantee a future listing.
7. Regulatory / Legal Risk
The 2026 NCLT creditor dispute highlights the need for careful legal due diligence.
8. Valuation Risk
Although ₹48 looks inexpensive on FY2025 earnings, the market may be discounting uncertainty around future earnings quality, cash conversion and expansion.
9. Rapid Growth Sustainability
Growing from ₹126 Cr to ₹1,903 Cr in three years is extraordinary.
The key question is whether this growth can continue.
What Investors Should Track
For the next few years, I would closely monitor:
Revenue
Can Polymatech sustain 20%+ growth?
EBITDA Margin
Can the company maintain margins above 20%?
Operating Cash Flow
Does cash flow grow alongside PAT?
Receivables
Can the company reduce receivable days?
Inventory
Does inventory grow slower than revenue?
Capex
What return is generated on the new capacity?
New Customers
Are new global customers being added?
Product Mix
Is the company moving toward higher-value semiconductor products?
IPO
Does the company revive/update its DRHP?
Investment Thesis
Polymatech is essentially a bet on:
India’s semiconductor manufacturing opportunity + company execution + continued high earnings growth.
The investment becomes particularly interesting because the current indicative market price around ₹48 implies only around:
5x FY2025 earnings
while the company has:
- ₹1,900+ Cr revenue
- ₹375+ Cr PAT
- ~25% EBITDA margin
- ~₹392 Cr cash
- low debt
- significant manufacturing assets
- semiconductor exposure
- substantial historical growth
But There Is a Catch
The valuation looks cheap only if FY2025 earnings are sustainable.
Investors should therefore avoid simply applying a 15–20x semiconductor-sector multiple to the company.
A more conservative approach is to ask:
What is normalized earnings?
If FY2025 PAT of ₹375 Cr is sustainable, ₹48 looks inexpensive.
If FY2025 represented an unusually strong cycle and normalized earnings are materially lower, the valuation becomes less attractive.
Overall Assessment
| Parameter | Assessment |
|---|---|
| Business Potential | ★★★★★ |
| Semiconductor Opportunity | ★★★★★ |
| Historical Growth | ★★★★★ |
| Profitability | ★★★★★ |
| Balance Sheet | ★★★★☆ |
| Debt Position | ★★★★★ |
| Cash Position | ★★★★☆ |
| Revenue Visibility | ★★★★☆ |
| IPO Optionality | ★★★☆☆ |
| Working Capital | ★★★☆☆ |
| Execution Risk | ★★★☆☆ |
| Unlisted Liquidity | ★★☆☆☆ |
| Valuation at ~₹48 | ★★★★☆ |
Final Investment View
Polymatech Electronics is one of the more interesting semiconductor-focused companies in India’s unlisted market.
The strongest part of the story is the combination of business growth and profitability.
From FY2022 to FY2025:
Revenue: ₹126 Cr → ₹1,903 Cr
PAT: ₹35 Cr → ₹376 Cr
while the company maintained relatively low financial leverage.
At approximately ₹48/share, the implied market capitalisation is around ₹1,900 Cr, against FY2025 PAT of approximately ₹376 Cr.
That gives an approximate:
5x P/E
which looks attractive if earnings are sustainable.
The company also has a potentially powerful long-term tailwind from India’s semiconductor manufacturing push.
However, this is not a risk-free investment.
The biggest issues to monitor are:
Working capital + customer concentration + technology execution + capex returns + sustainability of FY2025 earnings + IPO status.
The historical ₹750 Cr DRHP is a positive indicator of the company’s earlier listing ambition, but investors should not assume an imminent IPO until a fresh regulatory filing or official announcement confirms it.
Bottom Line
At around ₹48, Polymatech appears to offer an interesting risk-reward profile for investors seeking exposure to India’s semiconductor manufacturing theme, provided the investor is comfortable with unlisted-market liquidity and execution risk.
The valuation becomes particularly compelling if the company can sustain strong earnings growth while improving cash conversion and successfully monetising its expanding semiconductor capacity.
For UnlistedCart, I would position this as:
“A high-growth Indian semiconductor opportunity — but the next phase is about proving that exceptional growth can translate into sustainable cash flows.”
Important Links
Official Company Website:
Polymatech Electronics Limited
Official Investor Relations:
Polymatech Investor Relations
SEBI – Official DRHP Filing:
SEBI Polymatech Electronics DRHP
Polymatech DRHP – September 2023:
Official DRHP Document
FY2025 Financial Statements / Annual Report:
Polymatech FY2025 Financials & Annual Report
Current Unlisted Price Reference:
Polymatech – Planify
Current Unlisted Price & Fundamentals:
Polymatech – UnlistedZone
Current Unlisted Price Reference:
Polymatech – Neoma Capital
Disclaimer
This report is prepared for informational and research purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Polymatech Electronics Limited is currently unlisted. Prices quoted by private-market intermediaries are indicative and may differ substantially depending on availability, quantity, liquidity and transaction terms.
Historical financial performance, including FY2025 earnings, should not automatically be extrapolated into future years. Semiconductor manufacturing involves significant technology, execution, capital expenditure, customer concentration and working-capital risks.
The 2023 DRHP represents a historical IPO filing and should not be interpreted as confirmation of an imminent IPO or listing.
Investors should independently verify the latest audited financial statements, current capital structure, legal proceedings, shareholding, corporate actions, IPO status, related-party transactions and executable transaction price before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
