
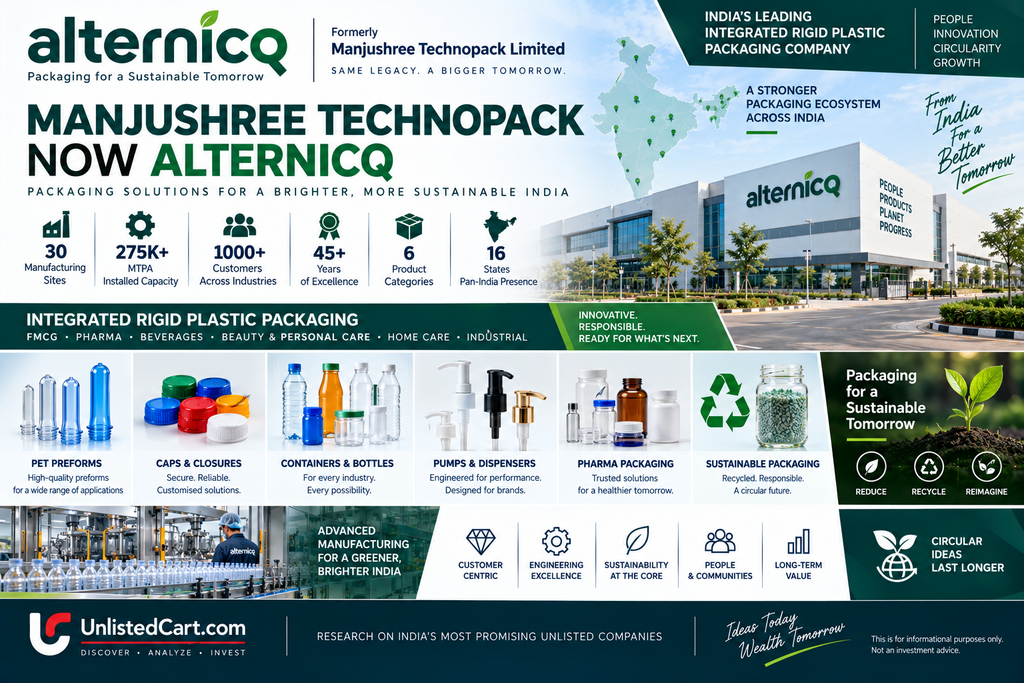
Now known as Alternicq Limited
Sector: Rigid Plastic Packaging | Status: Unlisted Public Company
ISIN: INE435H01023 | Face Value: ₹2 per share
Research Period: FY2025–FY2026
Indicative Unlisted Price: ₹883–₹925 per share
1. Executive Summary
Manjushree Technopack, now Alternicq Limited, is one of India’s large integrated rigid plastic packaging companies, supplying packaging solutions across beverages, food, dairy, pharma, personal care, home care, paints, agrochemicals, lubricants and other industries.
The company has evolved from a conventional packaging manufacturer into an integrated packaging platform covering design, manufacturing, recycling, innovation and multiple packaging formats. Its current website highlights 29 facilities across 16 states and six major product categories, including preforms, caps & closures, containers, pumps & dispensers and pharma packaging solutions.
The investment story, however, has changed materially from the original Manjushree IPO narrative. The company shelved its proposed IPO in November 2024 and was subsequently acquired by PAG. In 2026, the company rebranded as Alternicq and is pursuing a proposed merger with Pravesha Industries, adding a significant pharmaceutical-packaging component to the business.
FY25 revenue was strong at ₹2,569.83 Cr, but reported PAT of ₹247.63 Cr was substantially influenced by exceptional items. Current FY26 secondary financial databases indicate revenue of approximately ₹2,716.75 Cr and PAT of ₹46.27 Cr, showing why normalized earnings need to be examined carefully rather than relying only on headline revenue growth.
2. Company Overview
Legal name: Alternicq Limited
Former name: Manjushree Technopack Limited
CIN: U67120HR1987PLC138149
ISIN: INE435H01023
Incorporated: 1987
Registered Office: IMT Manesar, Haryana
Corporate Office: Bengaluru, Karnataka
The company states that its roots go back more than four decades and that it has built an integrated rigid-plastic packaging platform serving multiple consumer and industrial applications. Its stated vision is to become a ₹8,500+ Cr enterprise by 2030 with 20%+ ROCE. This is a management vision, not a forecast or guarantee.
3. What Does the Company Do?
Alternicq operates across several packaging categories:
- PET preforms
- Caps & closures
- Plastic containers
- Bottles and jars
- Pumps & dispensers
- Pharma rigid packaging
- Pharma print solutions
- Recycled/PCR packaging
- Packaging design and engineering
- Recycling and circular packaging solutions
The company currently reports 29 facilities, six product categories and presence across 16 states.
Major end-user industries
The company serves:
- Beverages
- Food & nutrition
- Dairy
- Personal care
- Beauty & wellness
- Home care
- Pharmaceuticals
- Alcoholic beverages
- Paints & construction chemicals
- Agrochemicals
- Automotive lubricants
- Retail
4. Manufacturing Scale
The company’s current website highlights significant manufacturing scale.
For beverage packaging alone, Alternicq states annual capacity of more than:
140,000 MT of PET preforms
14 billion+ closures
It also states that its products are exported to 45+ countries, with manufacturing distributed across multiple locations to provide supply continuity.
This scale is strategically important because packaging is a high-volume, logistics-sensitive business where proximity to customers, manufacturing scale and reliable supply can influence customer retention.
5. Product & Technology Differentiation
The company’s competitive proposition is increasingly based on integrated capabilities rather than simply producing commodity plastic packaging.
Its website highlights:
- Advanced injection moulding
- PET preform manufacturing
- Aseptic packaging capabilities
- Cleanroom manufacturing
- Product design and development
- Lightweighting
- PCR/recycled plastic solutions
- Packaging re-engineering
- Technical customer support
- Recycling and circularity initiatives
The company has also introduced Project Earth, its sustainability transformation programme focused on increasing PCR usage and developing circular packaging solutions.
6. Customer & Industry Opportunity
Rigid plastic packaging benefits from structural demand across FMCG, beverages, pharma, personal care, food and industrial applications.
Alternicq’s diversification across these industries reduces dependence on any single end market compared with a company focused exclusively on one packaging segment.
The company has specifically been expanding its presence in regulated pharmaceuticals, beauty/personal care and sustainable packaging. Its 2026 participation in CPHI India and Cosmoprof India highlights the company’s focus on these segments.
7. Financial Performance
Consolidated financial snapshot
| Particulars | FY22 | FY23 | FY24 | FY25 | FY26* |
|---|---|---|---|---|---|
| Revenue | ₹1,412 Cr | ₹2,109 Cr | ₹2,130 Cr | ₹2,584 Cr | ₹2,726 Cr |
| Revenue from Operations | ₹1,406 Cr | ₹2,096 Cr | ₹2,117 Cr | ₹2,570 Cr | ₹2,717 Cr |
| EBITDA | ₹234 Cr | ₹302 Cr | ₹407 Cr | ₹588 Cr | ₹367 Cr |
| PAT | ₹79.8 Cr | ₹59.2 Cr | ₹140.8 Cr | ₹247.6 Cr | ₹46.3 Cr |
| Net Worth | ₹922 Cr | ₹951 Cr | ₹1,008 Cr | ₹1,411 Cr | ₹1,443 Cr |
| Operating Cash Flow | ₹274.7 Cr | ₹322.6 Cr | ₹352.4 Cr | ₹343.6 Cr | ₹326.4 Cr |
*FY26 figures are based on currently available secondary financial databases; the company’s current investor-relations website does not yet provide an FY26 annual report in the same format as the FY25 report.
Key observation
Revenue has continued to grow, but profitability has been much more volatile.
FY25 revenue from operations increased around 21%, but the reported PAT included a substantial exceptional item of ₹176.90 Cr. Profit before exceptional items was only ₹89.82 Cr.
Therefore, FY25’s ₹247.63 Cr PAT should not be treated as a normal recurring earnings base.
FY26 data indicates revenue increased further to around ₹2,717 Cr, while PAT fell sharply to approximately ₹46 Cr. EBITDA also declined to approximately ₹361–367 Cr depending on the database methodology.
8. Cash Flow
FY26 operating cash flow was approximately:
₹326.41 Cr
This compares with ₹343.64 Cr in FY25.
Investing cash flow was approximately -₹232 Cr, while financing cash flow was approximately -₹72 Cr. Cash and equivalents increased to approximately ₹135.62 Cr at FY26 year-end.
The continued positive operating cash generation is an important factor because the company operates with substantial working-capital requirements.
9. Balance Sheet & Leverage
FY26 reported total assets were approximately ₹3,354.72 Cr, with net worth of approximately ₹1,443.10 Cr.
CRISIL had earlier highlighted a large working-capital requirement as one of the key constraints on the business. The rating agency also reported debt/EBITDA of approximately 1.3x for FY25 and expected leverage to remain around 1–1.4x over the medium term.
The company therefore needs to be evaluated not only on revenue growth but also on:
- Working-capital intensity
- Interest costs
- Capacity utilisation
- Capex returns
- Debt reduction
- Operating margins
10. Credit Rating
CRISIL has historically assigned:
CRISIL AA-/Stable / CRISIL A1+
to the company’s bank facilities.
In February 2026, the rated amount was enhanced to approximately ₹1,486 Cr, while the ratings were placed on Watch with Developing Implications because of the proposed merger with Pravesha Industries.
CRISIL’s assessment highlights the company’s established market position and operating capabilities, while identifying working-capital requirements and competition as key constraints.
11. PAG Acquisition
A major change in the ownership structure occurred in 2025.
PAG acquired a substantial stake in Manjushree Technopack from Advent International. Media reports put the transaction valuation at approximately $1 billion for the company.
The transaction was significant because Advent had been preparing the company for a public-market listing.
12. IPO Status
Manjushree had filed a DRHP for a proposed IPO in 2024.
However, the company decided in November 2024 not to proceed with the proposed IPO, following the PAG transaction.
Therefore:
Current status: Unlisted
There is no confirmed current IPO date.
Some unlisted-share websites continue to display “DRHP Filed” because historical IPO documents remain available. That should not be interpreted as confirmation of an active IPO process.
13. Major New Development – Proposed Pravesha Merger
One of the most important developments for existing and prospective shareholders is the proposed merger between Alternicq and Pravesha Industries Private Limited.
Pravesha is focused on pharmaceutical and regulated packaging.
CRISIL reported that the merger remained subject to regulatory/NCLT approvals and placed Alternicq’s ratings on Watch with Developing Implications while the transaction was being evaluated.
A current merger update indicates:
FY25
| Alternicq | Pravesha | Combined | |
|---|---|---|---|
| Total Income | ₹2,584 Cr | ₹603 Cr | ₹3,187 Cr |
| PBT | ₹266.7 Cr | ₹94.3 Cr | ₹361 Cr |
| PAT | ₹247.6 Cr | ₹70.9 Cr | ₹318.5 Cr |
The proposed scheme reportedly provides for 111 Alternicq equity shares for every 100 Pravesha equity shares/CCPS, subject to the scheme’s terms and approvals.
This merger could increase the group’s exposure to higher-value regulated pharmaceutical packaging, but the final impact depends on completion of the scheme, accounting treatment, capital structure and future earnings.
14. Shareholding
Available merger information indicates that before the proposed scheme, promoters/promoter group held approximately 92% of Alternicq, with approximately 8% held by other shareholders.
The proposed post-scheme structure is indicated at approximately 90% promoter/promoter group and 10% other shareholders.
This high promoter ownership is relevant for unlisted investors because secondary-market liquidity can be substantially lower than that of listed companies.
15. Current Unlisted Share Price
Current OTC references are approximately:
₹883–₹925 per share
Recent references include:
- ₹883.33 — Moneycontrol
- ₹885 — UnlistedZone, 15 September 2026
- ₹925 — multiple unlisted-market platforms in September 2026
These are indicative OTC prices and not NSE/BSE market quotes.
Important valuation-data issue
There is a significant inconsistency in currently available secondary-market databases.
For example, Moneycontrol displays a price around ₹883, FY26 EPS of ₹4.90 and P/E of 28.47x simultaneously. Mathematically, ₹883 ÷ ₹4.90 is approximately 180x, not 28x.
Therefore, investors should not blindly rely on the P/E displayed by unlisted-share websites.
The underlying FY26 earnings/share data and share-count adjustments should be independently verified before using P/E for valuation.
16. Valuation Framework
Using the FY26 EPS of approximately ₹4.90 reported by current financial databases:
| P/E Multiple | Implied Value |
|---|---|
| 10x | ₹49 |
| 15x | ₹74 |
| 20x | ₹98 |
| 25x | ₹123 |
| 30x | ₹147 |
| 40x | ₹196 |
This demonstrates that FY26 reported EPS cannot by itself explain an OTC price near ₹900.
A more relevant valuation exercise would therefore require:
- Normalised EBITDA
- Normalised PAT
- Treatment of exceptional items
- Post-merger share capital
- Pravesha earnings contribution
- Debt and net debt
- Future margin recovery
- Potential future IPO/listing structure
CRISIL had previously expected FY26 PAT of approximately ₹76 Cr, materially above the currently reported secondary-database PAT of ₹46.27 Cr.
This difference itself highlights the importance of determining normalised earnings before assigning a valuation.
17. Key Growth Drivers
1. Scale in rigid plastic packaging
Large manufacturing capacity and a broad customer base provide operating scale.
2. Beverage packaging
The company has substantial PET preform and closure capacity and exports to multiple markets.
3. Pharma packaging
The proposed combination with Pravesha could increase exposure to regulated pharmaceutical packaging.
4. Beauty & personal care
Alternicq is actively expanding its presence in beauty, health and personal-care packaging.
5. Sustainable packaging
PCR, lightweighting and circular packaging could become increasingly important for large FMCG customers.
6. Customer proximity
Multiple manufacturing facilities across India allow the company to supply large customers closer to their production locations.
18. Key Risks
Earnings volatility
FY26 profitability declined substantially despite revenue growth.
Exceptional items
FY25 PAT was materially influenced by exceptional items, making historical P/E comparisons potentially misleading.
High interest burden
FY26 finance cost was approximately ₹119 Cr in the currently available financial database.
Working-capital requirement
CRISIL specifically identifies working-capital intensity as a key constraint.
Raw-material volatility
Plastic resin and crude-linked input prices can affect margins, particularly where price pass-through is delayed.
Merger execution
The Pravesha merger remains subject to the applicable regulatory and NCLT process.
Unlisted liquidity
There is no continuous exchange-traded market, and OTC prices can differ significantly between buyers and sellers.
IPO uncertainty
The earlier IPO was withdrawn, and there is currently no confirmed listing timetable.
19. Investment Monitoring Checklist
For investors evaluating the shares, the following should be monitored closely:
Financial
- EBITDA margin recovery
- PAT excluding exceptional items
- Interest coverage
- Debt/EBITDA
- Operating cash flow
- Working-capital days
Corporate
- Completion of Pravesha merger
- Final share-exchange implications
- Post-merger share count
- Promoter holding
- Any fresh capital infusion
Listing
- Any fresh DRHP/RHP
- SEBI approval
- IPO timetable
- Proposed issue price/band
- OFS versus fresh issue
Valuation
- Normalised EPS
- EV/EBITDA
- Debt-adjusted valuation
- Post-merger earnings
- Comparable listed packaging companies
20. Overall Assessment
Manjushree Technopack has transformed considerably and should now be viewed through the lens of Alternicq, rather than simply as the earlier Manjushree IPO story.
The company has significant scale, diversified packaging capabilities, a broad end-market presence, positive operating cash generation and a major strategic push into sustainable and regulated packaging. Its current platform reports 29 facilities, six product categories and exports to more than 45 countries.
At the same time, the financial picture requires careful analysis. FY25 headline PAT was supported by exceptional items, while FY26 reported profitability was substantially lower. Leverage, interest costs, working capital and the economics of the proposed Pravesha merger are therefore critical factors.
The ₹883–₹925 OTC price should not be evaluated using the headline P/E ratios displayed on some unlisted-share platforms, because current databases contain inconsistencies between price, EPS, share count and reported P/E.
The most important future catalysts are likely to be earnings normalisation, margin recovery, successful completion of the Pravesha merger, integration benefits and any renewed IPO/listing plan.
21. Important Sources
Manjushree FY2024-25 Annual Report
Disclaimer
This report is prepared for research and informational purposes based on publicly available company documents, rating-agency reports and indicative unlisted-market information. Unlisted share prices are not exchange-traded prices and may vary based on transaction size, availability, buyer/seller demand and liquidity.
Financial figures from secondary databases should be independently reconciled with the latest audited financial statements before making an investment decision. Valuation scenarios are illustrative and are not price targets or guaranteed returns.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
