
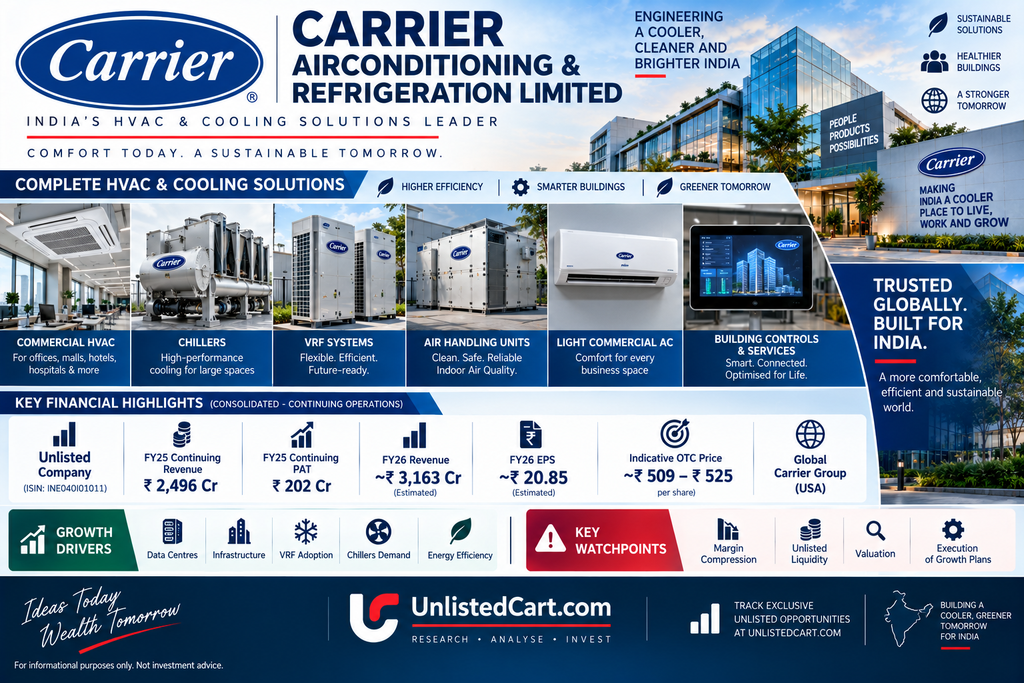
Sector: HVAC, Air Conditioning & Cooling Solutions
Status: Active Public Unlisted Company
CIN: U74999HR1992FLC036104
ISIN: INE040I01011
Face Value: ₹10
Registered Office: Narsingpur, Kherki Daula, Gurugram, Haryana
Global Parent: Carrier Global Corporation
Current Indicative Unlisted Price: ~₹509–₹525/share
Research Date: September 2026
1. Executive Summary
Carrier Airconditioning & Refrigeration Limited is the Indian operating company of the global Carrier group and is engaged in heating, ventilation, air conditioning, refrigeration and building-climate solutions.
The company has a substantially broader business profile than a conventional residential AC manufacturer. Its portfolio includes VRF systems, chillers, air-handling systems, light-commercial air conditioning, building controls, service and lifecycle solutions, with significant exposure to commercial buildings, infrastructure, airports, railway stations, healthcare, hospitality and data centres.
The company’s FY25 performance benefited from strong growth in continuing HVAC operations. However, FY25 reported profit also included gains from the sale of businesses that Carrier was strategically exiting. The Commercial Refrigeration business was transferred to Haier Appliances (India) and the Fire & Security business was divested separately.
The more relevant earnings base is therefore continuing HVAC operations, rather than simply using FY25 total PAT.
Secondary financial data indicates that FY26 revenue from operations increased to approximately ₹3,163 Cr, while continuing PAT increased to approximately ₹222 Cr. EBITDA, however, grew much more slowly than revenue, indicating margin pressure.
At an indicative unlisted price around ₹519–₹525, the company is valued at roughly ₹5,500–₹5,600 Cr.
2. Company Overview
Carrier Airconditioning & Refrigeration Limited was incorporated in 1992 and is classified as an active public company and subsidiary of a foreign company. It remains unlisted on Indian stock exchanges.
The company is part of the Carrier global ecosystem, whose history goes back to Willis Carrier and the development of modern air conditioning.
Carrier’s Indian operations have developed manufacturing, engineering, sales and service capabilities across multiple HVAC categories.
Official company resources
Official Carrier India website:
Carrier India
Investor Relations:
Carrier India Investor Information
The company’s investor page currently includes FY2026 AGM materials, including approval of financial statements and the draft annual return for FY2025-26.
3. Business Model
Carrier operates across several segments of the cooling ecosystem.
A. Commercial HVAC
This includes:
- Chillers
- VRF systems
- Air handling units
- Fan coil units
- Building controls
- Applied cooling systems
- Energy-efficiency solutions
Carrier’s FY25 annual report highlights strong growth in commercial HVAC and particularly in VRF and applied cooling.
B. Light Commercial
The company offers products for:
- Retail outlets
- Offices
- Restaurants
- Small commercial establishments
- High-end residential applications
Its portfolio includes inverter systems, cassettes, floor-standing units and other light-commercial products.
C. Chillers
Chillers are an important part of Carrier’s commercial and industrial proposition.
The FY25 annual report highlights:
- Screw chillers
- Scroll chillers
- Centrifugal chillers
- Oil-free centrifugal chillers
- Water-cooled chillers
- Air-cooled chillers
Carrier also launched locally manufactured 19XR centrifugal chillers from its Gurugram facility during FY25.
D. VRF
VRF is one of the company’s key growth areas.
Carrier reported that the VRF market expanded because of its efficiency and flexibility and said that it grew faster than the market during FY25, increasing its share in the segment.
The company also launched a new generation of VRF products with enhanced reliability and redundancy features.
E. Services & Lifecycle Solutions
Carrier is increasingly building a service-oriented business around its installed equipment base.
Its FY25 report discusses:
- Service modernization
- Digital monitoring
- Predictive maintenance
- Building automation
- Energy optimization
- AI-enabled chiller plant optimization
- Long-term service solutions
The company has also been developing Energy-as-a-Service and CAPEX-based models where Carrier can participate in energy audits, plant operations and performance commitments.
This creates an opportunity for recurring revenue beyond the initial equipment sale.
4. Product Portfolio
Carrier’s FY25 annual report shows a broad product portfolio.
Key products
Air Conditioning
- VRF
- Split systems
- Cassette systems
- Floor-standing systems
- Ducted systems
Applied HVAC
- Screw chillers
- Scroll chillers
- Centrifugal chillers
- Air-handling units
- Fan coil units
Controls & Digital
- Building automation
- Intelligent controls
- Digital monitoring
- Energy optimization
The company also manufactures Toshiba-branded Hi-Wall and VRF products following the integration of relevant manufacturing assets.
5. FY25 Financial Performance
According to the FY25 audited annual report, continuing operations generated:
| Particulars | FY24 | FY25 | Growth |
|---|---|---|---|
| Revenue from Operations | ₹2,131.14 Cr | ₹2,496.12 Cr | ~17.1% |
| Other Income | ₹28.58 Cr | ₹47.41 Cr | ~65.9% |
| Total Income | ₹2,159.72 Cr | ₹2,543.53 Cr | ~17.8% |
| PBT – Continuing Operations | ₹175.45 Cr | ₹275.24 Cr | ~56.9% |
| PAT – Continuing Operations | ₹131.78 Cr | ₹202.46 Cr | ~53.6% |
| EPS – Continuing Operations | ₹12.39 | ₹19.04 | ~53.7% |
The audited annual report reports revenue from operations of ₹2,496.12 Cr and continuing-operations PAT of ₹202.46 Cr for FY25.
Important: FY25 PAT requires adjustment
Total FY25 PAT was approximately ₹452.59 Cr, but this included profit from discontinued operations.
The discontinued-business profit included the gain from the Commercial Refrigeration transaction and the Fire & Security divestment.
Therefore, for valuation purposes:
FY25 continuing PAT = ₹202.46 Cr
is considerably more relevant than:
FY25 total PAT = ₹452.59 Cr
6. FY26 Financial Performance
The latest secondary financial databases indicate the following FY26 performance:
| Particulars | FY25 | FY26 | Growth |
|---|---|---|---|
| Revenue from Operations | ₹2,496.12 Cr | ₹3,163.15 Cr | +26.7% |
| EBITDA | ₹257.95 Cr | ₹265.68 Cr | +3.0% |
| PBT | ₹275.24 Cr | ₹298.28 Cr | +8.4% |
| Continuing PAT | ₹202.46 Cr | ₹221.83 Cr | +9.6% |
| EPS | ₹19.03 | ₹20.85 | +9.6% |
Source: currently available FY26 secondary financial databases. The official Carrier investor page shows FY26 financial statements being approved and FY2025-26 AGM documentation available, but the full FY26 annual report was not available in the same searchable format used for FY25 at the time of this research.
Key takeaway
Revenue grew by approximately 27%, but EBITDA grew only around 3%.
This means the company experienced a meaningful operating-margin compression.
FY25 EBITDA margin was approximately 10.3%, compared with approximately 8.4% in FY26 based on the secondary dataset.
This is an important factor to monitor.
7. Cash Flow
FY25 operating cash flow from continuing company operations was approximately:
₹171.46 Cr
compared with:
₹273.12 Cr in FY24
The company generated ₹284.04 Cr of investing cash flow during FY25, substantially influenced by investment/divestment-related cash movements, while financing cash flow was approximately -₹394.68 Cr, primarily reflecting dividend distributions.
The company ended FY25 with approximately ₹480.52 Cr of cash and cash equivalents according to the audited cash-flow data.
Dividend distribution
Carrier paid an interim dividend of:
₹26.50/share
and recommended a final FY25 dividend of:
₹35.50/share
for a total FY25 dividend of approximately:
₹62/share
subject to the applicable approvals.
This is a significant cash distribution and partly explains the sharp reduction in net worth/cash flow from financing activities.
8. Balance Sheet
Secondary FY26 financial data indicates:
| Particular | FY25 | FY26 |
|---|---|---|
| Total Assets | ₹1,647.90 Cr | ₹2,010.69 Cr |
| Net Worth | ₹579.33 Cr | ₹424.50 Cr |
| Total Liabilities | ₹1,068.57 Cr | ₹1,586.19 Cr |
| Operating Cash Flow | ₹171.46 Cr | ₹86.64 Cr |
| EPS | ₹19.03 | ₹20.85 |
The fall in net worth despite profit generation should be interpreted alongside the company’s very large dividend distributions.
Carrier is not a conventional highly leveraged company; finance cost was only approximately ₹2.13 Cr in FY26 in the available financial dataset.
9. Commercial Refrigeration Business Sale
One of the biggest structural changes in the company occurred during FY25.
Carrier entered into a Business Transfer Agreement with Haier Appliances (India) Private Limited for the sale of its Commercial Refrigeration business.
The audited report states that the transaction was consummated on October 1, 2024.
The final consideration was revised to approximately ₹265 Cr, and the business was transferred on a slump-sale basis.
The transaction generated a pre-tax gain of approximately ₹261.54 Cr in the company’s accounts.
Why this matters
Investors should not use historical revenue and profit numbers without considering this change in business composition.
Carrier today is more concentrated around:
HVAC + commercial cooling + VRF + chillers + controls + services
rather than the earlier broader combination that included Commercial Refrigeration.
10. Fire & Security Divestment
Carrier also exited the Fire & Security products business.
The company had established Kiddel Technologies India Private Limited and subsequently sold the subsidiary to Kidde Fenwal LLC for approximately ₹41.86 Cr.
The transaction generated a profit of approximately ₹21.49 Cr.
This further simplified Carrier India’s business portfolio.
11. Data Centre Opportunity
Data centres are becoming an increasingly important demand driver for high-performance cooling.
Carrier’s FY25 annual report specifically states that the company launched its 30XF Z range of chillers to address data-centre cooling requirements.
Data centres require:
- High reliability
- 24×7 cooling
- Energy-efficient systems
- Redundancy
- Precision temperature management
- High-capacity chillers
- Digital monitoring
This is strategically attractive for companies with established commercial HVAC capabilities.
12. Infrastructure Opportunity
Carrier reported strong demand from:
- Airports
- Metro projects
- Railway stations
- Government buildings
- Commercial offices
- Healthcare
- Sports complexes
- Data centres
The company specifically highlighted government infrastructure projects and the Amrit Bharat Station Scheme as demand contributors to VRF and chiller markets.
This provides a broader demand base than purely residential AC sales.
13. Manufacturing & Localization
Localization is a major part of Carrier’s India strategy.
During FY25, Carrier:
- Expanded local manufacturing
- Started manufacturing new VRF products
- Localized centrifugal chillers
- Expanded chiller capabilities
- Continued manufacturing Toshiba-branded products
- Invested in engineering and product development
The company states that its first India-manufactured centrifugal chiller range should improve localization, competitiveness and potentially margins.
14. Sri City Expansion
Carrier has also announced a major manufacturing expansion in Sri City, Andhra Pradesh.
Current unlisted-market research reports indicate that Carrier plans a significant investment in a new greenfield facility at Sri City, strengthening its manufacturing footprint in India.
This can potentially support:
- Additional capacity
- Localization
- Regional supply
- Export opportunities
- Product diversification
- Manufacturing efficiency
However, the return on this investment should be evaluated after the facility reaches meaningful utilization.
15. Industry Opportunity
India’s HVAC industry has several structural demand drivers:
Rising cooling demand
Increasing temperatures and higher household and commercial penetration can support long-term HVAC demand.
Urbanization
Expansion of:
- Residential towers
- Commercial offices
- Retail
- Hospitals
- Hotels
- Airports
- Metro systems
creates demand for HVAC equipment.
Data centres
India’s expanding digital infrastructure requires high-performance cooling systems.
Energy efficiency
Businesses are increasingly seeking lower energy consumption, creating demand for efficient chillers, VRF systems and digital controls.
Replacement cycle
The installed HVAC base creates a recurring replacement and modernization market.
16. Competitive Advantages
Global Carrier brand
Carrier has more than a century of global HVAC heritage and technology.
Commercial HVAC expertise
The company has significant exposure to large commercial and infrastructure projects.
Broad product portfolio
Carrier can supply multiple components of an HVAC installation rather than relying exclusively on one product.
Manufacturing localization
Local production of chillers and VRF systems can improve supply-chain responsiveness and reduce dependence on imports.
Service ecosystem
Lifecycle services, maintenance, modernization and digital solutions can provide recurring revenue.
Technology
Carrier’s focus on intelligent controls, energy optimization and AI-enabled solutions can help differentiate its commercial offering.
17. Current Unlisted Share Price
As of September 2026, available OTC references indicate:
~₹509–₹525/share
Moneycontrol currently shows approximately ₹519.47/share, while other unlisted-market platforms have reported prices around ₹509.85–₹525.
These are indicative unlisted-market prices, not NSE/BSE traded prices.
The price can vary materially between dealers because there is no continuous exchange order book.
18. Current Valuation
Using the Moneycontrol reference price of approximately ₹519.47:
Market Capitalisation
Approximately:
₹5,526 Cr
based on 10.64 Cr outstanding shares.
FY26 EPS
Approximately:
₹20.85
Implied P/E
₹519.47 ÷ ₹20.85 ≈
24.9×
Moneycontrol reports approximately 25.18×.
Book Value
Approximately:
₹39.91/share
P/B
Approximately:
13×
19. Valuation Sensitivity
Using FY26 EPS of ₹20.85:
| P/E Multiple | Implied Value |
|---|---|
| 15× | ₹313 |
| 18× | ₹375 |
| 20× | ₹417 |
| 22× | ₹459 |
| 25× | ₹521 |
| 28× | ₹584 |
| 30× | ₹626 |
| 35× | ₹730 |
At approximately ₹519, the market is effectively valuing the company around 25× FY26 EPS.
Therefore, the valuation leaves relatively less room for disappointment if earnings growth slows or margins remain compressed.
20. Earnings Scenario Analysis
Illustrative—not forecasts:
Scenario A: EPS ₹23
At 25×:
₹575/share
At 30×:
₹690/share
Scenario B: EPS ₹26
At 25×:
₹650/share
At 30×:
₹780/share
Scenario C: EPS ₹30
At 25×:
₹750/share
At 30×:
₹900/share
The key question is therefore not simply whether India’s HVAC industry grows, but whether Carrier can translate that growth into sustainable EPS growth and margin expansion.
21. IPO / Listing Status
Carrier Airconditioning & Refrigeration Limited remains unlisted.
Available current databases show:
DRHP: Not Filed
and no confirmed IPO timetable has been identified.
Therefore, the shares should not be marketed as a confirmed pre-IPO opportunity.
Any future listing would be an additional optional catalyst, not the core basis of the current valuation.
22. Share & Demat Information
ISIN: INE040I01011
Face Value: ₹10
Outstanding Shares: 10,63,76,745
Status: Unlisted
Depository availability: NSDL/CDSL references are available in the secondary market.
Carrier’s official investor information also provides a process for dematerialisation of shares.
23. Registrar & Transfer Agent
Carrier’s current investor-grievance page identifies:
Link Intime India Private Limited
as the Registrar & Share Transfer Agent for Carrier Airconditioning & Refrigeration Limited.
Official investor grievance page:
Carrier Investor Grievance / RTA Information
This is particularly important for unlisted investors dealing with:
- Dematerialisation
- Share transfer
- Transmission
- Duplicate certificates
- Corporate actions
- Investor grievances
24. Key Risks
1. Valuation risk
At approximately 25× FY26 EPS, the stock is not inexpensive on an absolute earnings multiple basis.
2. Margin compression
Revenue grew strongly in FY26, but EBITDA grew only around 3%, resulting in lower operating margins.
3. Unlisted liquidity
There is no continuous exchange-traded liquidity.
4. Business restructuring
The company has recently exited Commercial Refrigeration and Fire & Security businesses. Historical financial comparisons therefore require normalization.
5. HVAC cyclicality
Large commercial projects and construction activity can be cyclical.
6. Raw-material costs
Metals, compressors, electronics and refrigerant-related inputs can influence margins.
7. Competition
The Indian HVAC market has several established global and domestic players.
8. Project execution
Large infrastructure and data-centre projects require strict delivery, installation and service capabilities.
9. Capital allocation
The company has distributed substantial dividends, while simultaneously investing in manufacturing expansion. Investors should monitor whether future capital expenditure produces adequate returns.
25. Important Catalysts to Monitor
Near to medium term
1. FY26 official annual report
The full audited FY26 financial statements should be reconciled against secondary databases once available.
2. Sri City manufacturing expansion
Track investment, commissioning and capacity utilization.
3. Chiller localization
Monitor whether locally manufactured chillers improve gross margins and market share.
4. Data-centre orders
Data centres could become an important high-value commercial HVAC vertical.
5. VRF growth
Carrier’s performance in VRF will be an important driver of future revenue.
6. Service revenue
Growth in maintenance, modernization and digital services could improve recurring revenue quality.
7. Margin recovery
This is arguably one of the most important metrics to monitor after the FY26 revenue growth.
26. Investment View – Research Perspective
Carrier Airconditioning & Refrigeration is fundamentally different from a small unlisted AC manufacturer.
It combines:
Global brand + commercial HVAC + chillers + VRF + manufacturing + engineering + services + infrastructure exposure + data-centre opportunity.
The FY25–FY26 period also represents a transition phase because the company has divested non-core businesses and is becoming more focused on HVAC.
The strongest part of the investment thesis is therefore the structural growth of India’s cooling and commercial HVAC market combined with Carrier’s technology, brand and localization capabilities.
The principal issue at the current OTC valuation is earnings growth versus valuation.
At around ₹519/share and approximately 25× FY26 EPS, investors are paying a meaningful multiple for a business whose revenue is growing rapidly but whose EBITDA growth has recently lagged revenue growth.
Consequently, the key parameters to monitor are:
Revenue growth → EBITDA margin → EPS growth → ROCE → cash generation → valuation multiple
rather than simply relying on the Carrier brand or a possible future IPO.
27. Overall Assessment
Carrier Airconditioning & Refrigeration Limited represents a large, globally backed, technology-oriented HVAC platform in India’s unlisted market.
The company has several structural growth opportunities:
- Rising cooling demand
- Commercial HVAC
- VRF
- Chillers
- Data centres
- Infrastructure
- Energy efficiency
- Building automation
- Service and modernization
- Manufacturing localization
FY26 revenue growth was strong, with continuing revenue from operations increasing to approximately ₹3,163 Cr. However, EBITDA growth was considerably slower and margins compressed.
The divestment of Commercial Refrigeration and Fire & Security also means investors should focus on the new, more concentrated HVAC earnings profile rather than historical headline profits.
At approximately ₹509–₹525/share, the stock is being valued at around 25× FY26 EPS, making future earnings growth and margin normalization important determinants of valuation support.
For an unlisted investor, the additional consideration is liquidity: even a fundamentally strong company can have limited exit opportunities because shares are not continuously traded on NSE/BSE.
28. Important Links
Official Carrier India:
Carrier India
Investor Relations:
Carrier Investor Information
Investor Grievance / RTA:
Carrier Investor Grievance
FY2024-25 Annual Report:
Carrier Airconditioning & Refrigeration FY2024-25 Annual Report
Current unlisted-market reference:
Carrier Unlisted Share Price – Moneycontrol
Disclaimer
This report is prepared for research and informational purposes using publicly available company documents, the company’s official investor information, audited FY2024-25 financial statements and current secondary-market financial data.
Unlisted share prices are indicative OTC references and are not NSE/BSE exchange prices. Actual transaction prices can differ depending on liquidity, lot size, seller availability and transaction terms.
FY2026 financial figures cited from secondary databases should be reconciled with Carrier’s final audited FY2025-26 annual report when available.
Valuation calculations and scenario analysis are illustrative and should not be interpreted as guaranteed returns or price targets. Investors should independently verify the latest financial statements, share ownership, ISIN, dematerialisation status and transferability before entering into an unlisted-share transaction.
For more such unlisted stocks visit Unlisted Shares on UnlistedCart
