
India’s Established Elevator & Escalator Manufacturing Company
Company: Johnson Lifts Private Limited
CIN: U27209TN1981PTC008718
Incorporated: 15 April 1981
Status: Active Unlisted Private Company
Headquarters: Chennai, Tamil Nadu
Industry: Elevators, Escalators, Vertical Mobility & Engineering
Website: Johnson Lifts – Official Website
1. Executive Summary
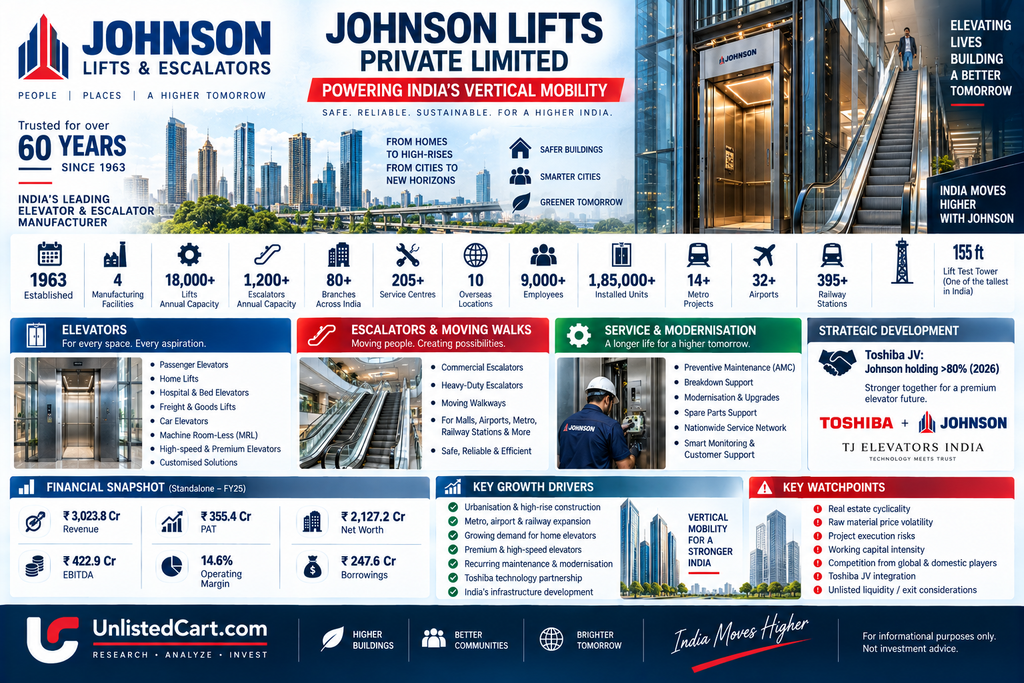
Johnson Lifts is one of India’s established elevator and escalator manufacturers, with roots going back to 1963, when the Johnson brand was founded by K.J. John. The current legal entity, Johnson Lifts Private Limited, was incorporated in 1981. The company manufactures, installs, services and modernises elevators and escalators across residential, commercial and infrastructure applications.
According to the company’s current website, Johnson operates four manufacturing facilities, with combined production capacity of more than 18,000 lifts and 1,200 escalators per year. It has a nationwide service and branch network, overseas operations and an installed base running into more than 185,000 units according to its corporate profile.
The company’s latest available FY25 financial information is particularly notable:
- Revenue: approximately ₹3,023.84 Cr
- Revenue growth: approximately 13%
- EBITDA: approximately ₹422.9 Cr
- PAT: approximately ₹355.4 Cr
- Net worth: approximately ₹2,127.2 Cr
- Borrowings: approximately ₹247.6 Cr
- EBITDA growth: approximately 35.6%
- PAT growth: approximately 45.3%
A major 2026 development is Johnson Lifts’ increase of its stake in Toshiba Johnson Elevators (India) Private Limited from 49% to more than 80%. The business has subsequently been presented as TJ Elevators India, with Toshiba continuing as the technology partner and exclusive Toshiba-brand partner in India.
This gives Johnson exposure to both the mass-market elevator business and the premium/high-speed elevator segment.
2. Company Background
Johnson Lifts traces its operating history to 1963, when Mr. K.J. John founded the Johnson business.
The company’s first lift was installed at Hotel New Woodlands in Chennai in 1966. Over subsequent decades, Johnson expanded its manufacturing, sales, installation and maintenance capabilities across India.
Its manufacturing footprint now includes:
- Poonamallee, Chennai
- Sengadu, Chennai
- Oragadam, Chennai – escalator facility
- Nagpur
The company states that these four facilities have combined annual capacity of 18,000+ lifts and 1,200+ escalators.
Company profile: Johnson Lifts – About the Company
3. Business Model
Johnson Lifts operates across the complete vertical-mobility value chain:
Design → Manufacturing → Installation → Maintenance → Modernisation
This creates revenue opportunities both when a new elevator is installed and throughout the operating life of the equipment.
The major business areas are:
Elevators / Lifts
Johnson manufactures elevators for:
- Residential buildings
- Villas and independent houses
- Commercial buildings
- Hospitals
- Hotels
- Airports
- Industrial facilities
- Government buildings
- Railway stations
- Metro projects
Its portfolio includes machine-room-less and machine-room elevators, gearless systems, passenger elevators, freight elevators, car lifts and specialised elevators.
Escalators
Johnson manufactures commercial and heavy-duty escalators and has operated a dedicated escalator manufacturing facility in Oragadam, Chennai since 2010.
Moving Walkways
The company also supplies moving walks for airports, metro systems and other high-footfall infrastructure.
Service & Maintenance
Maintenance is a strategically important part of the elevator industry because installed equipment requires periodic servicing, spare parts and eventual modernisation.
Johnson currently operates a large service network and offers preventive maintenance, breakdown service and modernisation solutions.
4. Product Portfolio
Johnson’s product range includes:
| Category | Examples |
|---|---|
| Residential | Home lifts, low-rise and medium-rise elevators |
| Passenger | Standard passenger elevators |
| Premium | High-speed and gearless elevators |
| Commercial | High-capacity commercial elevators |
| Industrial | Goods/freight elevators |
| Automotive | Car elevators |
| Healthcare | Hospital/special-purpose elevators |
| Escalators | Commercial & heavy-duty escalators |
| Moving Walks | Airport & infrastructure moving walkways |
| Modernisation | Elevator upgrades and replacement systems |
The company also provides technologies including permanent-magnet synchronous motors, VVVF drives, regenerative drives, infrared safety screens and machine-room-less systems.
Product catalogue: Johnson Lifts – Product & Catalogue Centre
5. Manufacturing Capabilities
Johnson has invested significantly in manufacturing capacity.
The company currently operates four factories with combined annual capacity of:
18,000+ Lifts
1,200+ Escalators
Its manufacturing infrastructure is supported by R&D, quality control and testing facilities.
Johnson also operates a 155-foot test tower, which it describes as one of the tallest lift-testing towers in India.
The company’s Poonamallee facility has also received CII GreenCo Silver Certification, highlighting its focus on environmentally responsible manufacturing.
6. Installed Base & Service Network
A major competitive feature of an elevator company is its installed base.
Johnson’s current corporate profile states:
- 185,000+ installed units
- 80+ branches
- 205+ service centres
- 10 overseas operations
- 9,000+ employees
The company’s service page separately reports more than 1,00,000 lifts and 3,500+ escalators under its service ecosystem, reflecting differences in how the company presents its current service coverage versus its broader lifetime installed base.
The service business includes:
- Preventive maintenance
- Breakdown service
- Spare parts
- Mobile service vans
- Customer-service monitoring
- Modernisation
- Annual maintenance contracts
This recurring-service component can provide a longer-term relationship with customers beyond the initial equipment sale.
7. Infrastructure Exposure
Johnson has participated in major infrastructure projects.
The company states that it has a presence across:
- 14+ metro projects
- 32+ airports
- 395+ railway stations
Earlier company disclosures also highlighted projects involving Chennai Metro, Chennai Airport and railway infrastructure.
This gives Johnson exposure to India’s ongoing:
Urbanisation + Metro Expansion + Airport Expansion + Railway Modernisation + Commercial Real Estate
cycle.
8. Financial Performance
Standalone Financial Trend
Available FY21–FY25 financial information indicates substantial growth:
| ₹ Crore | FY21 | FY22 | FY23 | FY24 | FY25 |
|---|---|---|---|---|---|
| Sales | 1,467.9 | 1,889.3 | 2,372.8 | 2,594.2 | 2,901.7 |
| Operating Profit | 179.5 | 181.7 | 228.2 | 311.8 | 422.9 |
| PAT | 123.1 | 130.4 | 164.7 | 244.6 | 355.4 |
| Operating Margin | 12.2% | 9.6% | 9.6% | 12.0% | 14.6% |
| Net Margin | 8.2% | 6.8% | 6.8% | 9.2% | 11.9% |
The trend is important because the company has not merely grown revenue; profitability has expanded faster than revenue in recent years.
9. FY25 Financial Highlights
FY25:
Total revenue: ~₹2,987.5 Cr
Sales: ~₹2,901.7 Cr
EBITDA / Operating Profit: ~₹422.9 Cr
PBT: ~₹470.3 Cr
PAT: ~₹355.4 Cr
Net worth: ~₹2,127.2 Cr
Assets: ~₹4,227.7 Cr
Borrowings: ~₹247.6 Cr
FY25 revenue increased by approximately 12.9%, EBITDA increased approximately 35.6%, and net profit increased approximately 45.3% according to the financial database’s MCA-based analysis.
10. Margin Expansion
One of the more important financial trends is operating-margin improvement.
| Year | Operating Margin |
|---|---|
| FY21 | 12.2% |
| FY22 | 9.6% |
| FY23 | 9.6% |
| FY24 | 12.0% |
| FY25 | 14.6% |
This suggests that FY25 growth was accompanied by meaningful operating leverage.
Possible factors include:
- Higher scale
- Product mix
- Better operating efficiency
- Service contribution
- Improved project execution
However, the exact contribution of each factor requires detailed company-level financial statements and management commentary.
11. Balance Sheet
FY25 reported figures include:
| Particular | FY25 |
|---|---|
| Total Assets | ~₹4,227.7 Cr |
| Net Worth | ~₹2,127.2 Cr |
| Borrowings | ~₹247.6 Cr |
| Debt/Equity | ~0.10x |
| Paid-up Capital | ₹0.75 Cr |
| Authorised Capital | ₹1.00 Cr |
The reported debt-equity ratio of approximately 0.10x indicates relatively moderate leverage compared with the size of the business.
MCA-linked databases also show open charges registered against the company. As of September 2026, TheCompanyCheck reported approximately ₹560.6 Cr of open charges, with ₹57.02 Cr satisfied.
Importantly, registered charges should not automatically be treated as current outstanding debt; the underlying MCA charge documents and latest balance sheet should be checked to determine the actual funded debt position.
12. Profitability Ratios
FY25 ratios reported by Tofler include:
Gross Margin: ~47.0%
Operating Margin: ~14.6%
Net Margin: ~11.9%
ROE: ~16.7%
ROCE: ~19.5%
Debt/Equity: ~0.10x
The combination of rising margins and relatively low leverage is an important feature of the FY25 financial profile.
13. Toshiba Partnership – Major 2026 Development
One of the most important developments for Johnson Lifts is its increased ownership in the Toshiba elevator joint venture.
Historically, Toshiba Johnson Elevators India was established in 2012 with:
Toshiba: 51%
Johnson Lifts: 49%
In April 2026, Johnson Lifts increased its holding to more than 80%, becoming the majority shareholder. Toshiba continues as the strategic technology partner.
The business has subsequently been presented under the TJ Elevators India identity.
TJ Elevators: TJ Elevators India – Official Website
14. Why the Toshiba Transaction Matters
The transaction potentially strengthens Johnson’s position in the premium elevator market.
Johnson contributes:
- Indian manufacturing
- Distribution
- Installation capability
- Service network
- Local customer relationships
- Infrastructure-project experience
Toshiba contributes:
- Japanese technology
- High-speed elevator expertise
- Premium product technology
- Technical support
- Toshiba brand
The new structure therefore combines local scale with Japanese technology.
15. Toshiba JV Financial Opportunity
The Toshiba-linked business currently has a significantly smaller revenue base than Johnson Lifts itself.
Toshiba Johnson Elevators India reported FY25 revenue of approximately ₹343.33 Cr.
Following the ownership restructuring, company management indicated an ambition to double the Toshiba-Johnson business over the next 3–4 years from its current level of around ₹300 Cr.
The business is focused on premium and high-speed elevators, where Toshiba technology can complement Johnson’s nationwide reach.
16. Market Position
Johnson has historically described itself as a leading player in India’s elevator industry.
In its corporate material, the company has cited approximately 20% market share in the Indian lift market. More recent 2026 industry coverage stated that the combined Johnson/Toshiba presence represents approximately 20% of the elevator market and around 30% of the escalator market.
These figures are company/industry-source claims rather than independently verified market-share measurements, so they should be treated accordingly.
17. India’s Elevator Industry Opportunity
India’s rapid urbanisation is creating structural demand for vertical mobility.
Major demand drivers include:
Residential Construction
High-rise apartments increasingly require multiple elevators per building.
Commercial Real Estate
Office towers, hotels, hospitals and shopping centres require passenger and service elevators.
Metro Expansion
Metro systems require elevators, escalators and moving walks.
Airports
Passenger movement within airports requires elevators, escalators and travelators.
Railway Modernisation
Railway stations increasingly require accessibility infrastructure.
Home Lifts
Home elevators are becoming more common in premium residences and independent houses.
Johnson itself notes the increasing transition of home lifts from a luxury product toward a practical accessibility solution.
18. Home Elevator Opportunity
Johnson has a dedicated home-lift portfolio.
Its products include:
- Mini Sukranti LR
- Eazy Ride Plus
- Enduronic
The company highlights features including:
- Machine-room-less operation
- Gearless technology
- Low pit depth
- Short headroom
- Single-phase operation
- Wheelchair accessibility
- Energy efficiency
This segment can potentially expand the company’s addressable market beyond large commercial and infrastructure projects.
19. R&D & Technology
Johnson maintains an internal R&D and testing ecosystem.
The company states that its R&D is led by professionals with decades of experience in design, research and manufacturing. It manufactures lifts and escalators compliant with applicable Indian and European standards, including BIS and EN81-certified products.
Technologies highlighted by Johnson include:
- Permanent Magnetic Synchronous Motors
- VVVF Drives
- Regenerative Drives
- Infrared Safety Screens
- Machine-Room-Less Technology
- Gearless Systems
- BMS/RMS compatibility
- Energy-efficient systems
20. Service & Modernisation – Recurring Opportunity
The elevator business has a useful characteristic: once installed, elevators require ongoing maintenance.
Johnson provides:
- Annual maintenance
- Preventive maintenance
- Breakdown support
- Spare parts
- Modernisation
- Smart service monitoring
The company operates service centres and dedicated training infrastructure for technicians.
Modernisation can become particularly important as India’s existing elevator installed base ages.
Replacing controllers, drives, doors and other components can extend the useful life of existing installations without replacing the entire elevator.
21. Competitive Advantages
1. Long Operating History
Johnson’s operating history dates back to 1963.
2. Manufacturing Scale
18,000+ lifts and 1,200+ escalators of annual capacity provide substantial manufacturing capability.
3. Nationwide Service Network
The company’s extensive service network provides an important competitive advantage in a maintenance-heavy industry.
4. Large Installed Base
A large installed base can create recurring service and modernisation opportunities.
5. Infrastructure Experience
The company has participated in metro, airport and railway projects.
6. Toshiba Technology
The increased ownership in the Toshiba JV adds access to Japanese technology and the premium/high-speed segment.
7. Product Diversification
Johnson serves residential, commercial, industrial and infrastructure markets.
22. Growth Drivers
Urbanisation
Growing urban density and high-rise construction increase demand for elevators.
Infrastructure Spending
Metro, airports and railway projects create demand for elevators, escalators and moving walks.
Premiumisation
High-speed and premium elevators offer a higher-value market opportunity.
Home Elevators
Increasing adoption of home lifts creates a newer residential opportunity.
Modernisation
Existing elevators require periodic upgrades and replacement of critical systems.
Toshiba Integration
Greater control over the Toshiba-linked business could expand Johnson’s premium-market presence.
Service Revenue
A growing installed base can support recurring maintenance and spare-parts revenue.
23. Key Risks
1. Real Estate Cyclicality
A slowdown in residential or commercial construction could affect new elevator orders.
2. Raw Material Prices
Steel, copper and other input costs can influence margins.
3. Project Execution
Large infrastructure contracts may involve long installation cycles and milestone-based payments.
4. Working Capital
Elevator projects can require significant working capital before final installation and customer acceptance.
5. Competition
The Indian elevator industry includes major multinational and domestic competitors.
6. Toshiba Integration
The increased ownership in the Toshiba JV creates an opportunity but also adds execution and integration responsibilities.
7. Unlisted Liquidity
Johnson Lifts is privately held and has no NSE/BSE trading platform.
An investor purchasing shares privately may face:
- Limited buyers
- Wide bid/ask spreads
- Limited price discovery
- Long holding periods
- Transfer restrictions
- Difficulty exiting at a desired price
24. Current Unlisted Share Price
No reliable publicly verified current OTC price found
Johnson Lifts is an unlisted private company and does not have an NSE/BSE market price.
I have therefore not inserted an unverified ₹/share figure into this report.
For any private transaction, investors should verify:
- Latest actual transaction price
- Number of shares being offered
- Seller/buyer identity
- Latest cap table
- Share-transfer restrictions
- Share certificate/demat status
- Applicable taxes and stamp duty
- Any shareholder agreement restrictions
A private-market asking price is not equivalent to a liquid market valuation.
25. Valuation Framework
Because Johnson Lifts is unlisted, conventional exchange-based valuation metrics are unavailable.
A suitable private-market valuation should consider:
Operating Earnings
FY25 EBITDA of approximately ₹422.9 Cr and PAT of approximately ₹355.4 Cr.
Net Worth
Approximately ₹2,127 Cr in FY25.
Growth
Revenue has increased from approximately ₹1,468 Cr in FY21 to approximately ₹2,902 Cr in FY25, while PAT increased from approximately ₹123 Cr to approximately ₹355 Cr over the same period.
Margin Expansion
Operating margin increased from 12.2% in FY21 to 14.6% in FY25.
Toshiba JV
The company now has majority control of the Toshiba-linked business, potentially expanding its exposure to the premium segment.
Service & Modernisation
The installed base provides potential recurring revenue beyond new installations.
For an actual investment, an EV/EBITDA + P/E + book-value + SOTP approach should be considered rather than relying on one valuation multiple.
26. Important Due-Diligence Checklist
Before purchasing Johnson Lifts shares in the private market, investors should obtain:
- Latest audited FY26 financial statements
- FY26 profit and loss statement
- Balance sheet
- Cash-flow statement
- Latest shareholding pattern
- Latest number of shares outstanding
- Latest valuation/transaction history
- Toshiba JV acquisition consideration
- Updated ownership structure of TJ Elevators
- Order book
- Segment-wise revenue
- Service/AMC revenue
- Receivables ageing
- Inventory
- Outstanding debt
- MCA charge status
- Related-party transactions
- Litigation
- Share-transfer restrictions
- Any IPO/listing plans
27. IPO / Listing Status
Currently Unlisted
Johnson Lifts Private Limited is classified as an active unlisted private company.
There is currently no confirmed IPO/DRHP identified in the sources reviewed.
Therefore:
NSE Listing: No
BSE Listing: No
Current Exchange Price: Not available
IPO: No confirmed current IPO
28. Key Numbers at a Glance
| Parameter | Latest Available |
|---|---|
| Founded | 1963 |
| Legal Entity Incorporated | 1981 |
| Status | Unlisted Private Company |
| FY25 Revenue | ~₹3,023.8 Cr |
| FY25 Sales | ~₹2,901.7 Cr |
| FY25 EBITDA | ~₹422.9 Cr |
| FY25 PAT | ~₹355.4 Cr |
| FY25 Net Worth | ~₹2,127.2 Cr |
| FY25 Borrowings | ~₹247.6 Cr |
| FY25 Operating Margin | ~14.6% |
| FY25 Net Margin | ~11.9% |
| FY25 ROE | ~16.7% |
| FY25 ROCE | ~19.5% |
| Annual Lift Capacity | 18,000+ |
| Annual Escalator Capacity | 1,200+ |
| Manufacturing Facilities | 4 |
| Branches | 80+ |
| Service Centres | 200+ |
| Installed Base | 185,000+ |
| Employees | 9,000+ |
| Toshiba JV Holding | >80% |
| Current Exchange Price | Not available |
Financial figures are based on FY25 MCA-linked financial databases; operating footprint figures are from Johnson’s official website.
29. Overall Research Assessment
Johnson Lifts represents an established private Indian vertical-mobility business with a combination of:
Long operating history
Large manufacturing capacity
Strong domestic distribution
Large installed base
Service & modernisation opportunity
Metro/airport/railway exposure
Home elevator opportunity
Premium elevator opportunity through Toshiba
Strong FY25 profitability
The financial trend is particularly notable. Between FY21 and FY25, sales increased from approximately ₹1,468 Cr to ₹2,902 Cr, while PAT increased from approximately ₹123 Cr to ₹355 Cr. At the same time, operating margin expanded from around 12.2% to 14.6%.
The April 2026 Toshiba transaction is another important strategic development. Johnson Lifts increased its ownership in the Toshiba JV to more than 80%, while Toshiba remains the technology partner. This gives Johnson greater control over a premium/high-speed elevator platform while retaining access to Japanese technology.
The key questions for a prospective private-market investor are therefore less about whether the company has a recognised operating franchise and more about the price at which shares can actually be acquired, the latest FY26 financial performance, the valuation multiple being demanded, working-capital quality, debt/charges and the economic impact of the Toshiba transaction.
Because the company is unlisted, entry valuation and eventual liquidity can have a major effect on realised returns, even if the underlying operating business continues to grow.
30. Important Links
Official Website: Johnson Lifts & Escalators
Company Profile: Johnson Lifts – About Us
Products & Catalogues: Johnson Lifts – Product Catalogue
Factories: Johnson Lifts – Manufacturing Facilities
Service Network: Johnson Lifts – Service & Maintenance
Home Elevators: Johnson Lifts – Home Lifts
Toshiba/JLPL New Platform: TJ Elevators India
MCA-linked Company Information: Johnson Lifts – Company Details
Disclaimer
This report is prepared for informational and research purposes only and should not be considered investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Johnson Lifts Private Limited is an unlisted private company and therefore does not have an exchange-traded market price. Financial figures sourced from third-party MCA-linked databases should be independently verified against the latest audited financial statements before making an investment decision.
Any private-market share price should be independently verified through an actual transaction, and investors should conduct due diligence on valuation, share-transferability, liquidity, taxation, debt, litigation and shareholder agreements.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
