
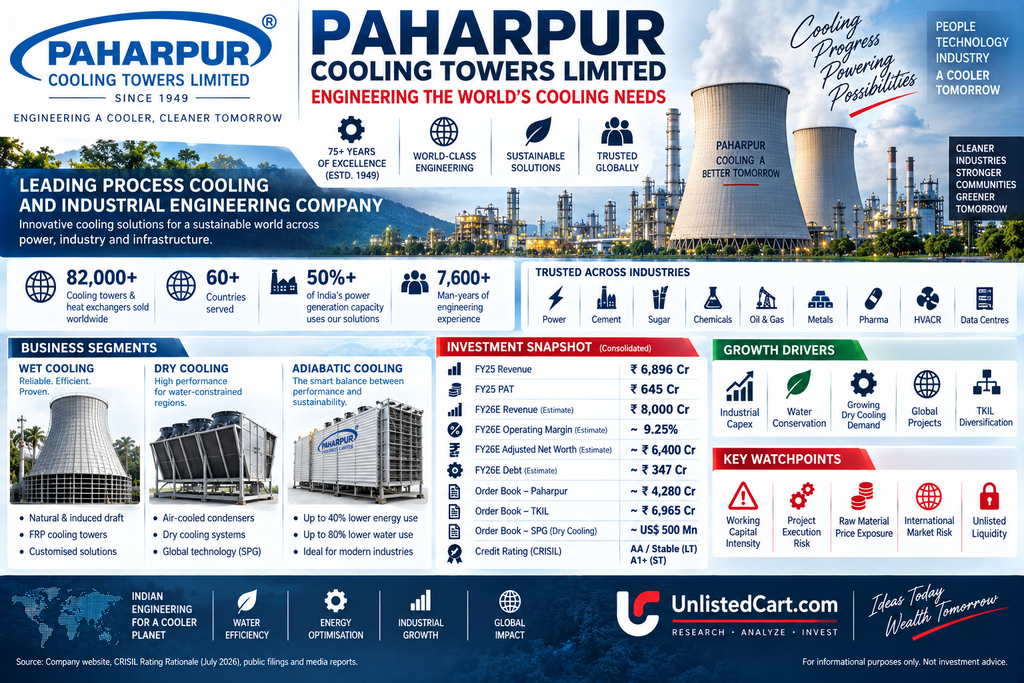
India’s Leading Process Cooling & Industrial Engineering Company
Company: Paharpur Cooling Towers Limited
CIN: U02005WB1949PLC018363
Incorporated: 25 October 1949
Status: Active Public Unlisted Company
Registered Office: Paharpur House, 8/1/B Diamond Harbour Road, Kolkata – 700027
Industry: Industrial Cooling, Dry Cooling, EPC & Engineering
Website: Paharpur Cooling Towers – Official Website
1. Executive Summary
Paharpur Cooling Towers Limited is an established Indian engineering company with more than seven decades of experience in process cooling, cooling towers, dry cooling systems and industrial engineering solutions.
Founded in 1948/1949, Paharpur describes itself as the world’s largest manufacturer of process cooling equipment, with more than 82,000 cooling towers and heat exchangers sold worldwide, exports to 60+ countries, and more than 7,600 man-years of engineering experience. The company states that its products serve more than 50% of India’s power-generation capacity.
The business has expanded substantially beyond conventional cooling towers following the acquisition of the dry-cooling business of SPX Corporation and the acquisition of a controlling stake in TKIL Industries Private Limited, formerly ThyssenKrupp Industries India.
This has transformed Paharpur into a broader industrial-engineering group with exposure to:
- Cooling towers
- Dry cooling systems
- Air-cooled condensers
- Heat exchangers
- EPC
- Sugar plants
- Cement
- Mining
- Material handling equipment
- Energy projects
- Industrial services
CRISIL’s July 2026 rating rationale estimates consolidated FY26 operating income at approximately ₹8,000 Cr, up about 15% from FY25, with operating margin around 9.25%. The combined group had an order book exceeding ₹11,200 Cr, plus approximately US$500 million of SPG dry-cooling orders.
2. Company Overview
Paharpur Cooling Towers was incorporated in Kolkata in 1949 and has built a long operating history in industrial cooling.
Its core business is designing, manufacturing, supplying and servicing equipment used to remove heat from industrial processes.
Its customers span:
- Power plants
- Oil & gas
- Petrochemicals
- Cement
- Steel
- Chemicals
- Fertilisers
- Pharmaceuticals
- Food & beverage
- HVACR
- Data centres
- Infrastructure
- Mining
The company’s official website currently showcases wet cooling, dry cooling and adiabatic cooling technologies.
Company information: Paharpur – About Us
3. What Does Paharpur Cooling Towers Do?
At its core, Paharpur provides equipment and engineering solutions designed to manage industrial heat.
A. Wet Cooling Towers
Paharpur provides several types of wet cooling towers for industrial and commercial applications.
These systems are widely used where large quantities of process heat have to be rejected efficiently.
The company’s portfolio includes:
- Natural draft cooling towers
- Induced draft cooling towers
- Factory-assembled towers
- Field-erected towers
- FRP cooling towers
- HVAC cooling towers
The company states that its cooling solutions are used across power, chemical, fertiliser, oil & gas, pharmaceuticals, food and beverage and other industries.
B. Dry Cooling
Dry cooling has become increasingly important where water availability is constrained.
Paharpur’s SPG dry-cooling business provides:
- Air-cooled condensers
- Air-cooled heat exchangers
- Dry cooling systems
- Auxiliary cooling systems
The dry-cooling business gives the company a global presence and exposure to markets where water conservation is an important consideration.
C. Adiabatic Cooling
Paharpur has also developed adiabatic cooling technology.
Its Infinium adiabatic cooler is positioned as an alternative between conventional wet and dry cooling.
The company states that the system can potentially reduce energy consumption by up to 40% or water usage by up to 80%, depending on operating conditions.
Adiabatic cooling: Paharpur Infinium Adiabatic Coolers
4. Industries Served
Paharpur has exposure to multiple industrial sectors.
Power
Historically, power has been one of Paharpur’s most important markets.
Its cooling equipment is used in thermal and other power-generation applications.
Oil & Gas / Petrochemicals
Cooling systems are required across refineries, petrochemical plants and processing facilities.
Cement
The group has increased its cement exposure through TKIL’s engineering and EPC capabilities.
Sugar
TKIL provides engineering and turnkey solutions for sugar plants.
Mining
Material handling and engineering solutions provide exposure to mining projects.
HVACR
Paharpur also supplies cooling systems for:
- Airports
- Data centres
- Hotels
- Hospitals
- Commercial buildings
- Shopping malls
- Railway & subway systems
The company specifically states that its products serve the cooling requirements of the Delhi, Kolkata, Lucknow and Jaipur metro systems.
5. TKIL Industries Acquisition
One of the most important strategic developments for Paharpur was the acquisition of a controlling stake in TKIL Industries Private Limited, formerly ThyssenKrupp Industries India.
Paharpur acquired an additional 44.64% stake in May 2024, taking its total ownership to approximately 55.64%.
TKIL operates across:
- Sugar
- Cement
- Mining
- Energy
- Material handling equipment
- EPC
- Industrial services
This acquisition significantly diversified Paharpur beyond its traditional cooling-tower business.
CRISIL began consolidating TKIL from FY25 onward.
6. Financial Performance
Consolidated Financials
CRISIL’s financial analysis provides the following consolidated picture:
| ₹ Crore | FY24 | FY25 | FY26E |
|---|---|---|---|
| Revenue / Operating Income | ~3,893 | ~6,896 | ~8,000 |
| PAT | ~344 | ~645 | Not separately disclosed |
| Operating Margin | 10.65% | 9.87% | ~9.25% |
| Adjusted Net Worth | — | ~₹6,100 Cr | ~₹6,400 Cr |
| Debt | — | ~₹573 Cr | ~₹347 Cr |
FY25 was the first full year in which TKIL was consolidated, resulting in a major increase in reported scale.
Important: FY26 revenue of approximately ₹8,000 Cr is a CRISIL estimate, not an audited figure presented here as final reported revenue.
7. FY25 Performance
According to CRISIL:
FY25 Consolidated
Operating income: ₹6,896 Cr
PAT: ₹645 Cr
Operating margin: 9.87%
The sharp increase in revenue was primarily influenced by the first full-year consolidation of TKIL.
Paharpur’s standalone cooling-tower operations also improved materially, while the SPG dry-cooling business showed better performance.
8. FY26 Business Performance
CRISIL’s July 2026 assessment estimates that consolidated operating income increased approximately 15% YoY to around ₹8,000 Cr in FY26.
Segment-level FY26 estimates were:
| Business | FY26 Revenue | Operating Margin |
|---|---|---|
| Paharpur Cooling Tower Business | ~₹2,100 Cr | ~16.6% |
| SPG Dry Cooling | ~₹1,975 Cr | ~10% |
| TKIL Industries | ~₹3,870 Cr | ~5.8% |
| Consolidated | ~₹8,000 Cr | ~9.25% |
CRISIL estimates consolidated OPBDIT above ₹770 Cr for FY26.
This shows that the original cooling-tower business remains the higher-margin component, while TKIL adds significant revenue scale and diversification.
9. Order Book – Major Investment Consideration
One of the strongest measurable indicators for Paharpur is its order book.
As of 31 March 2026, CRISIL reported:
Paharpur Cooling Tower Business
Order backlog: ~₹4,280 Cr
TKIL
Order backlog: ~₹6,965 Cr
SPG Dry Cooling
Order book: ~US$500 million
Combined, Paharpur and TKIL had an order book exceeding ₹11,200 Cr, before considering the separate SPG order book in US dollars.
This provides substantial medium-term revenue visibility, although execution remains important.
10. Order Inflows
During FY26:
Paharpur cooling-tower business order inflow: ~₹3,700 Cr
TKIL fresh orders: ~₹5,700 Cr
SPG dry cooling bookings: >US$300 million
The continued order inflow indicates that the group was not merely executing its existing backlog but also replenishing the pipeline.
11. Global Presence
Paharpur exports its products to more than 60 countries.
Its global dry-cooling operations have expanded its exposure beyond India and provide access to international customers and projects.
The company has subsidiaries and operations across multiple geographies, including:
- Bangladesh
- Singapore
- Europe
- China
- USA
- Italy
- Turkey
- Nigeria
- Australia
CRISIL’s consolidation scope includes multiple Paharpur/SPG entities across these regions.
12. Investment Portfolio
One of the most interesting aspects of Paharpur is its investment portfolio.
CRISIL reported that the company had a quoted investment portfolio worth more than ₹2,000 Cr as of March 2026.
This provides a significant source of financial flexibility in addition to operating cash generation.
Paharpur also owns stakes in other businesses.
For example, as of December 2025, Paharpur held approximately 4.17% of KSB Limited, while its subsidiary Industrial & Prudential Investment Company held another 21.55%.
The investment portfolio therefore needs to be considered separately when assessing Paharpur’s underlying value.
13. Industrial & Prudential Investment Company
Paharpur controls Industrial & Prudential Investment Company Limited, a listed investment company.
The FY26 annual report identifies Paharpur Cooling Towers as the holding company controlling the composition of the board.
For FY26, Industrial & Prudential reported:
Standalone investments: ~₹5,028 Cr
Consolidated investments: ~₹8,758 Cr
Standalone PAT: ~₹204 Cr
Consolidated PAT: ~₹637 Cr
It proposed a ₹120/share dividend for FY26.
This subsidiary/holding-company structure is important when analysing Paharpur because the group’s value includes both operating businesses and investment assets.
14. Financial Risk Profile
Paharpur’s balance sheet remains relatively conservative.
CRISIL estimates:
FY26 adjusted net worth: ~₹6,400 Cr
FY26 total debt: ~₹347 Cr
Adjusted gearing: <0.05x
The company also maintained:
Cash & cash equivalents: >₹1,000 Cr
Investments: >₹1,500 Cr according to CRISIL’s consolidated liquidity assessment
This results in a net cash position at the consolidated level.
15. Credit Rating
CRISIL reaffirmed Paharpur’s ratings in July 2026:
Long-Term
CRISIL AA / Stable
Short-Term
CRISIL A1+
The rated bank facilities total ₹1,700 Cr, including fund-based and non-fund-based facilities.
The rating reflects Paharpur’s established market position, diversified operations, healthy order book, strong liquidity and conservative leverage.
Rating rationale: CRISIL Rating Rationale – July 2026
16. Working Capital
Working capital is one of the major areas investors need to monitor.
The consolidated business is project-based and consequently carries significant receivables and contract assets.
CRISIL reported gross current assets of approximately 244 days as of March 2026, although this improved from around 269 days in the previous fiscal year.
There was, however, improvement in receivable quality:
Paharpur
Receivables outstanding for more than 180 days:
FY25: ~35%
FY26: ~22%
Receivables outstanding for more than three years declined to nil from approximately 3%.
This improvement is important because long receivable cycles can otherwise consume significant working capital.
17. Dry Cooling – Strategic Opportunity
Water availability is becoming an increasingly important consideration for industrial and power projects.
Paharpur’s dry-cooling business provides a technology solution for projects where conventional wet cooling is less suitable.
The company acquired the dry-cooling business of SPX Corporation in 2016 for approximately US$55 million, giving it access to technology, patents, brand and an international customer base.
The business has subsequently become an important part of Paharpur’s international operations.
18. Adiabatic Cooling & Energy Efficiency
Paharpur is also investing in cooling solutions designed around resource efficiency.
Its Infinium adiabatic cooler is marketed as a solution that can reduce:
- Energy consumption by up to 40%, or
- Water consumption by up to 80%
depending on application and operating conditions.
This gives Paharpur exposure to the broader trend toward water-efficient and energy-efficient industrial cooling.
19. Competitive Advantages
1. Seven Decades of Experience
Paharpur has operated since 1949 and has extensive experience in complex cooling applications.
2. Strong Domestic Position
CRISIL describes Paharpur as having an established leadership position in India’s cooling-tower industry.
3. Technology Portfolio
The company offers wet cooling, dry cooling, adiabatic cooling and related heat-exchange solutions.
4. International Presence
Exports to more than 60 countries provide geographic diversification.
5. TKIL Diversification
The TKIL acquisition adds exposure to sugar, cement, mining, energy, material handling and EPC.
6. Strong Order Book
The combined order book exceeded ₹11,200 Cr as of March 2026, with additional SPG dry-cooling orders.
7. Strong Balance Sheet
Low leverage, high liquidity and substantial investments provide financial flexibility.
20. Growth Drivers
Industrial Capex
Growth in power, cement, mining, chemicals and industrial infrastructure can drive demand for cooling and EPC systems.
Power Sector
Cooling infrastructure remains an important component of thermal and other power-generation projects.
Water Conservation
Increasing water scarcity can support demand for dry and adiabatic cooling solutions.
Data Centres
Data-centre expansion requires reliable cooling infrastructure, providing a newer application area for advanced cooling solutions.
Global Expansion
International dry-cooling projects provide access to large industrial and power markets.
TKIL Cross-Selling
Paharpur can potentially cross-sell cooling solutions, EPC capabilities and industrial engineering services across the combined customer base.
Renewable & Energy Transition
The company’s exposure to industrial energy infrastructure and its diversified engineering portfolio provides participation in the evolving energy ecosystem.
21. Key Risks
1. Working Capital Intensity
The business has a long working-capital cycle because of large projects and delayed receivables.
CRISIL continues to identify working capital as a key weakness.
2. Project Execution
Large cooling towers and EPC projects involve complex engineering, procurement, construction and commissioning.
Delays can affect margins and cash flow.
3. Raw Material Prices
TKIL’s fixed-price contracts can expose profitability to increases in steel and other input costs.
4. Capital Expenditure Cyclicality
Exposure to power, cement, mining, sugar and industrial EPC means new order flow can be influenced by the broader private and government capex cycle.
5. Competition
TKIL’s EPC businesses face competition from domestic and international engineering companies.
6. International Risk
SPG’s international operations introduce exposure to:
- Currency movements
- Geopolitical conditions
- Local regulations
- Project execution risks
7. Unlisted Liquidity
Paharpur shares are not traded on NSE or BSE.
An investor acquiring shares privately may face:
- Limited buyers
- Limited price discovery
- Long holding periods
- Difficulty exiting
- Transfer restrictions
- Wide difference between quoted/negotiated prices
22. Recent Legal Developments
Paharpur has been involved in ongoing legal/tender proceedings.
In April 2026, the Delhi High Court dismissed Paharpur’s writ petition concerning a tender where another bidder had been declared technically qualified and L1.
Paharpur subsequently sought review.
On 14 August 2026, the Delhi High Court dismissed the review petition, holding that the grounds raised did not establish an error warranting review. The judgment also recorded that approximately 80% of the relevant awarded work had already been executed by the respondent.
Separately, a 2026 Bombay High Court proceeding concerning the use of the “Hamon” name was referenced in the Delhi proceedings, but the Delhi High Court noted that the relevant Bombay injunction was interlocutory and, as of its 14 August 2026 judgment, was not operative.
These matters should be monitored as part of legal due diligence.
23. Siemens Arbitration Matter
Another historical legal matter involved Siemens and construction of three natural-draft cooling towers at Torrent Energy’s Dahej project.
The Bombay High Court’s June 2026 judgment recorded that the arbitration award resulted in a net amount of approximately ₹20.84 Cr payable by Siemens to Paharpur, and that this amount had been paid.
Therefore, this historical dispute should not simply be treated as an outstanding ₹20.84 Cr liability against Paharpur.
24. Current Unlisted Share Price
No reliable publicly verified current OTC price found
Paharpur Cooling Towers is an unlisted public company.
There is no NSE/BSE market price available, and I have not found a sufficiently reliable recent secondary transaction to publish a current OTC price.
For this reason, this report deliberately does not insert an estimated ₹/share figure.
For an actual transaction, investors should verify:
- Seller’s asking price
- Quantity available
- Latest transaction price
- Number of shares outstanding
- Transferability
- Share certificate/demat status
- Stamp duty and transaction costs
- Applicable tax treatment
25. Valuation Framework
For Paharpur, a simple P/E valuation may not fully capture the economics of the group.
A more appropriate framework can consider:
Operating Business Value
Cooling towers + dry cooling + TKIL EPC businesses
Investment Portfolio
Quoted equity and other investments
Cash
Consolidated cash and equivalents exceeding ₹1,000 Cr according to CRISIL’s FY26 assessment.
Debt
Approximately ₹347 Cr estimated consolidated debt.
Order Book
More than ₹11,200 Cr across Paharpur and TKIL, plus approximately US$500 million SPG order book.
Therefore, a sum-of-the-parts (SOTP) approach may provide a more meaningful valuation framework than simply applying a multiple to consolidated PAT.
26. Key Numbers at a Glance
| Parameter | Latest Available |
|---|---|
| Established | 1949 |
| Status | Unlisted Public Company |
| FY25 Consolidated Revenue | ~₹6,896 Cr |
| FY25 Consolidated PAT | ~₹645 Cr |
| FY26E Revenue | ~₹8,000 Cr |
| FY26E OPBDIT | >₹770 Cr |
| FY26E Operating Margin | ~9.25% |
| FY26E Net Worth | ~₹6,400 Cr |
| FY26E Debt | ~₹347 Cr |
| FY26 Cash | >₹1,000 Cr |
| FY26 Investments | >₹1,500 Cr |
| Paharpur Order Book | ~₹4,280 Cr |
| TKIL Order Book | ~₹6,965 Cr |
| SPG Order Book | ~US$500 Mn |
| Credit Rating | CRISIL AA/Stable / A1+ |
| Current Exchange Price | Not available |
FY26 figures labelled estimates are based on CRISIL’s July 2026 rating rationale.
27. Overall Research View
Paharpur Cooling Towers is an unusual unlisted opportunity because the company combines a long-established industrial franchise with a large investment portfolio and a significantly expanded engineering platform through TKIL.
The business today is much broader than traditional cooling towers.
The key pillars are:
Cooling Towers
Dry Cooling
Heat Exchangers
Industrial EPC
Material Handling
Sugar & Cement Engineering
Mining & Energy
Global Industrial Projects
The FY26 CRISIL assessment indicates approximately ₹8,000 Cr consolidated revenue, more than ₹770 Cr OPBDIT, a ₹11,200 Cr+ Paharpur/TKIL order book, approximately US$500 million SPG order book, low leverage and more than ₹1,000 Cr of cash.
The main areas requiring investor attention are working capital, project execution, raw-material exposure, TKIL integration, international operations and the price at which the unlisted shares can actually be acquired.
The investment case therefore needs to be evaluated on both sides:
Business quality + asset value + order book + balance sheet
versus
Entry valuation + liquidity + working-capital risk + execution risk.
28. Important Links
Official Website: Paharpur Cooling Towers
Company Overview: Paharpur – About Us
Wet Cooling Products: Paharpur Wet Cooling Solutions
Adiabatic Cooling: Paharpur Adiabatic Coolers
HVACR Solutions: Paharpur HVACR Solutions
Repair & Maintenance: Paharpur Repair & Maintenance Services
Latest Credit Rating: CRISIL – Paharpur Cooling Towers Rating Rationale, July 2026
MCA Company Information: Paharpur Cooling Towers – Company Information
Disclaimer
This report is prepared for informational and research purposes only and should not be considered investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Paharpur Cooling Towers Limited is an unlisted company, and there is no exchange-traded share price. Any privately negotiated price can differ materially depending on transaction size, seller, transfer restrictions and market liquidity.
FY26 financial figures identified as estimates are based on CRISIL’s July 2026 rating assessment and should not be confused with audited FY26 financial statements. Investors should independently verify the latest audited financials, cap table, investment portfolio, debt, litigation, share-transferability and actual secondary-market transaction price before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
