
Unlisted Company Research Report | Real Estate, Construction & Materials
Company: Delta Galaxy Engineering Services Limited
Formerly: Delta Galaxy Engineering Services Private Limited
CIN: U45204BR2011PLC017932
ISIN: INE0T0H01020
Incorporated: 27 December 2011
Registered Office: Patliputra Colony, Patna, Bihar
Status: Unlisted Public Company
Face Value: ₹10 per share
Paid-up Equity: 2.66 crore shares
Sector: Real Estate, Construction & Materials / Infrastructure
Website: Delta Galaxy Engineering Services
1. Company Overview
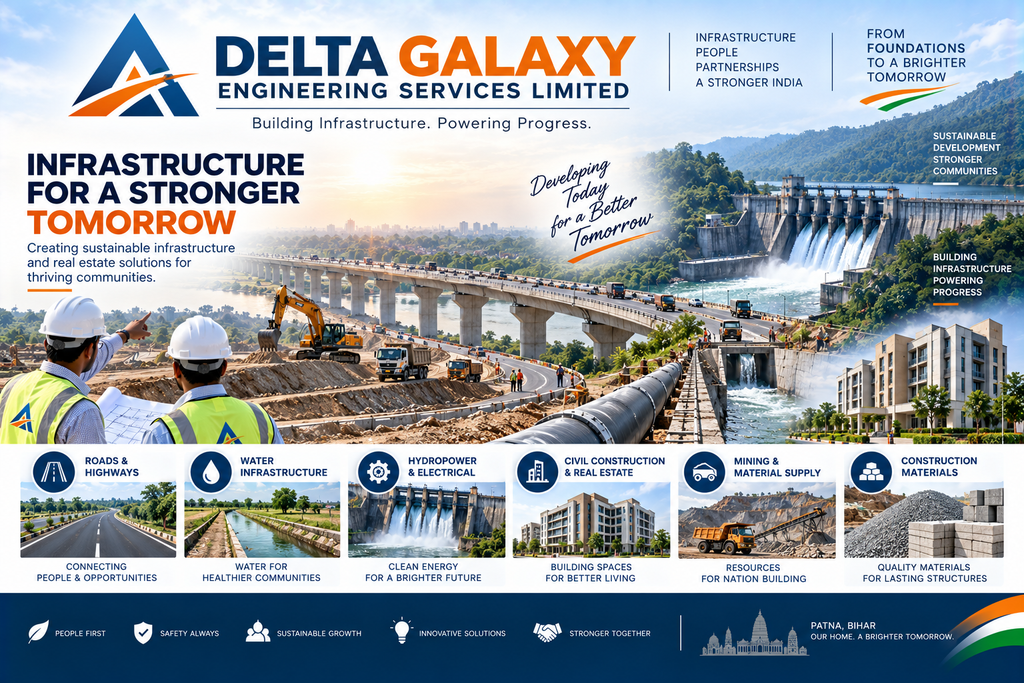
Delta Galaxy Engineering Services Limited is a Patna-based engineering and infrastructure company established in 2011. It has evolved from a relatively small engineering business into a diversified EPC and infrastructure-services company.
The company’s activities span civil construction, water and irrigation infrastructure, hydropower, roads and highways, tunnels, government buildings, real estate-related construction, mining, construction-material supply, electrical systems and industrial project services.
The company was converted from a private limited company into a public limited company in December 2024. Its FY25 financial statements confirm the conversion and the company’s current public-company structure.
2. Business Model
Delta Galaxy operates primarily through an EPC/project-execution model and also undertakes subcontracting and material-supply activities.
Major business areas
| Segment | Activities |
|---|---|
| Water Infrastructure | Water supply, irrigation systems, pipelines, drainage and water-distribution infrastructure |
| Hydropower & Electrical | Hydroelectric projects, electrical systems and power distribution |
| Roads & Civil Infrastructure | Roads, highways, bridges, buildings and civil works |
| Mining | Mining services and supply of minerals/materials |
| Real Estate & Buildings | Government buildings, staff quarters and civil/real-estate construction |
| Construction Materials | Supply/trading/manufacturing of construction-related materials |
| Industrial Services | Equipment, machinery and project-support services |
The company states that it provides infrastructure solutions across multiple industries, while third-party company profiles describe its business as general construction and civil-engineering activities with construction-material trading/manufacturing.
3. Major Project Exposure
The company’s disclosed/market-reported project portfolio includes:
- Ambikapur Water Supply Infrastructure — Chhattisgarh
- Jaunpur Water Supply Infrastructure — Uttar Pradesh
- Kwar Hydroelectric Power Project — Jammu & Kashmir
- Shongtong Karcham Hydroelectric Project — Himachal Pradesh
- Jaunpur Electrification Program
- Road construction projects
- Government buildings
- Mining and mineral projects
Altius reports a much larger current project pipeline, including mining contracts, the Muzaffarpur Bypass/NH-77 project and infrastructure work associated with BHEL’s Sipat thermal power project.
4. Order Book — One of the Key Attractions
CRISIL reported an unexecuted order book of approximately ₹580 crore as of June 2025, to be executed over 12–36 months. This represented roughly 2.5x FY25 revenue and provided medium-term revenue visibility.
More recent unlisted-market data reports an order book of approximately ₹1,791 crore across 19 live projects, with around 72% yet to be executed. Because this later figure is from an unlisted-share intermediary rather than a rating agency or audited filing, it should be treated as indicative rather than independently verified.
Why this matters
If the ₹1,791 crore figure is accurate, the company’s current order-book-to-FY26-revenue ratio would be more than 4.5x, providing substantial potential revenue visibility.
However, execution speed, working-capital availability and project certification/payment cycles will determine how much of this order book converts into revenue and cash flow.
5. Financial Performance
Revenue & Profit Growth
| ₹ Crore | FY23 | FY24 | FY25 | FY26* |
|---|---|---|---|---|
| Revenue | 79.49 | 174.48 | 233.63 | 392.00 |
| PAT | 2.72 | 14.05 | 25.52 | 39.22 |
| PAT Margin | 3.42% | 8.05% | 10.92% | 10.01% |
*FY26 figures reported by unlisted-market sources; final audited numbers should be checked against the company’s FY26 financial statements.
Revenue increased from approximately ₹79.5 crore in FY23 to ₹392 crore in FY26, while PAT increased from ₹2.72 crore to approximately ₹39.22 crore.
The FY25 company financial statement reports revenue of approximately ₹233.63 crore and PAT of approximately ₹26.34 crore, while some market databases show PAT of ₹25.52 crore. The difference appears to arise from the treatment of tax/financial-statement presentation, so investors should use the audited financial statements as the primary reference.
6. FY25 Financial Highlights
According to CRISIL’s July 2025 rating rationale:
- Revenue: ₹233.64 crore
- PAT: ₹26.34 crore
- PAT margin: 11.27%
- Adjusted debt/net worth: 0.41x
- Interest coverage: 14.98x
- Current ratio: 2.6x
- Unexecuted order book: ₹580 crore
CRISIL assigned CRISIL BBB/Stable to ₹30 crore of bank facilities.
This external credit rating is useful because it provides an independent assessment beyond the marketing material commonly available for unlisted companies.
7. Balance Sheet
The FY25 financial statements showed a significant increase in equity following fresh share issuance.
The company had approximately 2.66 crore equity shares outstanding at March 2025, compared with 1.50 crore shares in FY24. The paid-up capital was approximately ₹26.62 crore.
A provisional balance sheet available for January 2026 showed:
| Particulars | Jan 2026 |
|---|---|
| Share Capital | ₹26.62 Cr |
| Reserves & Surplus | ₹112.88 Cr |
| Net Worth | ~₹139.5 Cr |
| Long-term Borrowings | ₹25.60 Cr |
| Short-term Borrowings | ₹36.89 Cr |
| Trade Receivables | ₹139.09 Cr |
| Inventory | ₹62.51 Cr |
| Cash & Equivalents | ₹1.47 Cr |
The January 2026 provisional statement therefore indicates that the business had grown substantially, but also remained working-capital intensive, with receivables and inventory representing significant amounts on the balance sheet.
8. Promoters & Management
Key management includes:
- Rohitash Singh — Managing Director
- Amit Kumar — Director / Co-founder
- Shashank Singh — Whole-time Director
- Other directors include Subhendu Rajan Shukla, Sajal Saxena, Mopuri Krishniah Sateesh and Vijaya E Shahapurkar.
CRISIL notes that the promoters have more than a decade of experience in the civil-construction industry and have developed relationships with suppliers and customers over time.
9. Current Unlisted Share Price
As of September 2026, indicative market quotes vary across unlisted-share platforms.
| Source | Indicative Price |
|---|---|
| UnlistedZone | ₹44 |
| Moneycontrol | ₹41.19 |
| Altius quoted buy price | ₹39 |
| Other market quote | ₹48 |
UnlistedZone reported ₹44 as of 15 September 2026, while Moneycontrol showed ₹41.19. These are indicative unlisted-market levels, not exchange-traded prices.
There is also an important data-quality issue: some market websites still show 15 million shares outstanding, whereas the company’s FY25 financial statements report 2.66 crore shares.
Therefore, valuation should preferably be calculated using the latest company-reported share count.
10. Indicative Valuation
Using approximately 2.66 crore shares and an indicative price of ₹41–₹44:
Implied equity value: approximately ₹109–₹117 crore.
Using FY26 reported PAT of approximately ₹39.22 crore:
Indicative P/E: approximately 2.8x–3.0x
Using FY26 net worth reported by Altius at approximately ₹152.63 crore:
Indicative P/B: approximately 0.71x–0.77x.
This is a relatively low valuation against the company’s recent earnings growth.
However, the low multiple should not automatically be interpreted as undervaluation. The market may be discounting:
- Working-capital intensity
- Execution risk
- Customer/project concentration
- Unlisted-share liquidity
- Lack of an announced IPO/DRHP
- Construction-sector cyclicality
- Differences between reported and market-source financial data
11. IPO / Pre-IPO Status
The company is currently an unlisted public company, but available sources do not show a filed DRHP.
Altius currently identifies the company as “DRHP Not Filed”, while Moneycontrol also shows “DRHP Status: No.”
Therefore, the company should not be presented as having a confirmed IPO timeline.
Conversion from private to public company can be viewed as part of its corporate evolution, but it is not by itself confirmation of an upcoming IPO.
12. Key Growth Drivers
1. Infrastructure spending
Delta Galaxy operates in segments benefiting from India’s continuing infrastructure and public-capex cycle, particularly water, roads, hydropower and civil infrastructure.
2. Large order pipeline
The reported order book provides potential revenue visibility over the coming years, although execution remains the critical variable.
3. Strong historical growth
Revenue grew from ₹79.5 crore in FY23 to around ₹392 crore in FY26 according to current unlisted-market financial data.
4. Improving profitability
PAT margin increased from approximately 3.4% in FY23 to around 10% in FY26, showing significant improvement in reported profitability.
5. Diversified operations
Exposure to water, hydropower, roads, mining, civil construction, electrical infrastructure and construction materials reduces dependence on a single project category.
13. Key Risks
Working Capital
This is one of the most important risks.
CRISIL reported gross current assets of around 301 days as of March 2025 and bank-limit utilisation of approximately 90% over the preceding 12 months. CRISIL therefore classified liquidity as stretched despite a healthy current ratio.
Tender & Execution Risk
The construction business is dependent on winning and executing contracts. CRISIL specifically highlights susceptibility to tender-based operations and intense competition.
Receivables
The January 2026 provisional balance sheet showed trade receivables of approximately ₹139 crore, making timely collections important for sustaining growth.
Unlisted Liquidity
Unlike listed shares, there is no continuous exchange-based market. Buying and selling may involve wider spreads, limited counterparties and longer exit periods.
IPO Uncertainty
There is currently no verified DRHP filing. Therefore, any valuation thesis based on an imminent IPO should be treated cautiously.
Financial-data discrepancies
Different unlisted-market platforms currently report different share counts, prices and FY25/FY26 numbers. The company’s own financial statements and independent credit-rating reports should take precedence over intermediary estimates.
14. Overall Business Snapshot
| Parameter | View |
|---|---|
| Business | EPC / Infrastructure / Construction / Materials |
| Sector | Real Estate, Construction & Materials |
| Revenue Growth | Strong |
| PAT Growth | Strong |
| Order Visibility | Strong, subject to verification |
| Profitability | Improved materially |
| Balance Sheet | Improving but working-capital intensive |
| Debt Risk | Manageable based on CRISIL FY25 assessment |
| Liquidity | Key area to monitor |
| IPO | No DRHP verified |
| Unlisted Liquidity | Limited |
| Valuation | Low on reported earnings/book value, but requires due diligence |
15. UnlistedCart Takeaway
Delta Galaxy Engineering Services stands out primarily as a fast-growing infrastructure/EPC business rather than a conventional real-estate developer.
The key numbers are the substantial increase in revenue, sharp improvement in profitability and expansion of the reported order book.
The most important factor to monitor, however, is cash conversion. Construction companies can report strong revenue and profits while simultaneously consuming significant working capital. CRISIL’s comments on high receivables, inventory and bank-limit utilisation make this particularly important for Delta Galaxy.
At indicative market levels around ₹41–₹44 and using the latest reported share count, the company appears to trade at a low single-digit earnings multiple based on reported FY26 earnings. But the valuation should be considered alongside the company’s unlisted liquidity, working-capital requirements, execution risk and the absence of a confirmed IPO filing.
For an investor evaluating the company, the next major checkpoints should be FY26 audited financials, cash-flow conversion, receivable ageing, order-book execution and any future DRHP/IPO development.
Important Disclaimer
Unlisted-share prices are indicative and may vary significantly between platforms and transactions. There is no continuous exchange-based price discovery, and liquidity can be limited.
Financial figures from intermediary platforms may differ from audited/company filings. Investors should verify the latest audited financial statements, shareholding, liabilities, valuation and transaction terms before investing.
This report is for information and research purposes only and should not be treated as a guaranteed return or a recommendation to buy or sell securities.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
