
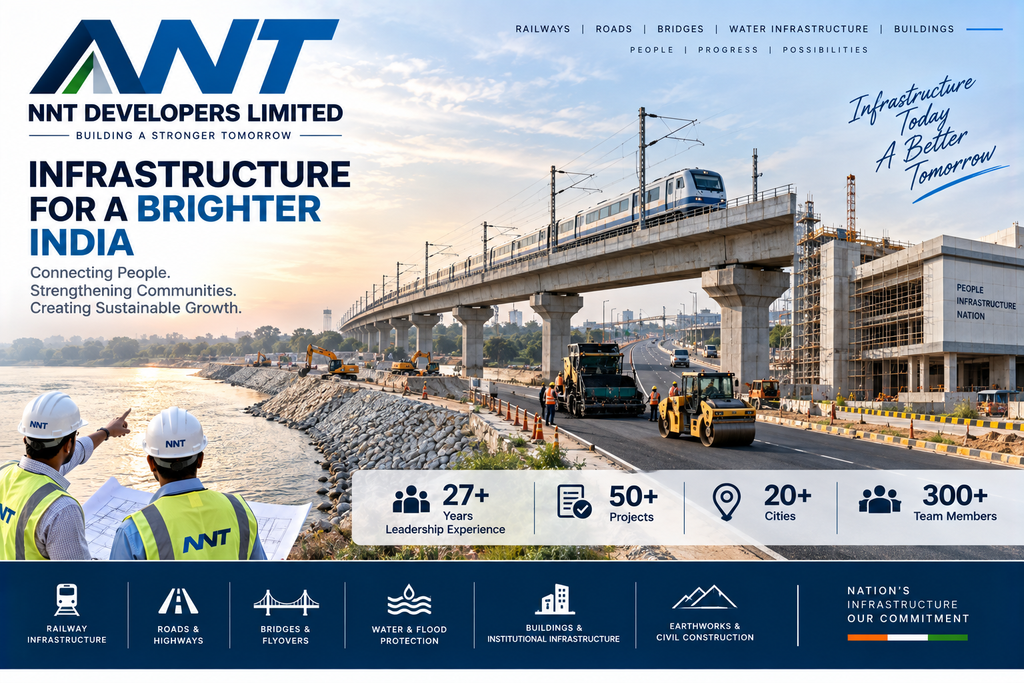
Civil Infrastructure | Railways | Roads | Bridges | Water & Flood Protection | Buildings
NNT Developers Limited is a Patna-based civil infrastructure and EPC company executing projects for government departments and public-sector organisations across railways, roads, bridges, flood protection, water infrastructure, buildings and related civil works.
The company was incorporated on 28 September 2017 and was formerly known as NNT Developers Private Limited. It was converted into a public limited company and remains unlisted on NSE/BSE. (ZaubaCorp)
A significant development is that NNT Developers has filed a Draft Red Herring Prospectus (DRHP) dated 30 September 2025, marking the formal beginning of its proposed public-market journey. The company’s website hosts the DRHP/RHP/prospectus section, although the IPO timetable and final pricing are not confirmed in the sources reviewed.
Company Snapshot
| Particular | Details |
|---|---|
| Company | NNT Developers Limited |
| Former Name | NNT Developers Private Limited |
| CIN | U45309BR2017PLC035873 |
| Incorporated | 28 September 2017 |
| Registered Office | 6th Floor, Sri Ram Tower, Kankarbagh, Patna, Bihar |
| Status | Unlisted Public Company |
| Face Value | ₹10 |
| Paid-up Capital | ~₹40 Cr |
| Equity Shares | ~4 Cr |
| ISIN | INE1C1201011 |
| Industry | Construction & Infrastructure |
| Core Business | EPC / Civil Infrastructure |
| Website | NNT Developers – Official Website |
Public corporate records show authorised capital of approximately ₹60 Cr and paid-up capital of approximately ₹40 Cr.
What Does NNT Developers Do?
NNT Developers is primarily an EPC/civil-construction contractor.
Its official website identifies the following major infrastructure verticals:
1. Railway Infrastructure
Projects include:
- Railway lines
- Gauge-conversion works
- Railway station buildings
- Earthworks
- Railway-associated civil infrastructure
The company has executed projects for East Central Railway and other railway-related organisations.
2. Roads & Highways
NNT undertakes:
- Road construction
- Road widening
- Earthwork
- Civil structures
- Highway-related infrastructure
3. Bridge & Flyover Construction
The company executes:
- Bridges
- Flyovers
- River-crossing infrastructure
- Associated structural and civil works
4. Water & Flood Infrastructure
This is one of NNT’s important areas of specialisation.
Projects include:
- River-bank protection
- Flood-control works
- Drainage
- Water infrastructure
- Deep-tube-well projects
- Earthwork and allied civil construction
The company’s project portfolio includes river-edge protection work in Bihar.
5. Building & Institutional Infrastructure
NNT also executes:
- Government buildings
- Educational institutions
- Hospitals/health infrastructure
- Residential/institutional structures
- Other public infrastructure
6. Real Estate Development
The company also identifies real-estate development among its capabilities, although its core current business is government/public-sector civil infrastructure.
Selected Projects
The company’s official project portfolio includes:
| Project | Client / Department |
|---|---|
| Jhanjharpur–Laukaha Bazar Gauge Conversion | East Central Railway |
| Hajipur–Sugauli New Rail Line | East Central Railway |
| River Ganga Left Edge Protection – Kewala to Baghmara | Flood Control Division, Kursela |
| Rajkiya Ambedkar Residential School, Murliganj | Bihar State Building Construction Corporation |
| Pahleza Station Building Complex | East Central Railway |
| Health Infrastructure, West Champaran | Bihar Medical Services & Infrastructure Corporation |
These examples demonstrate NNT’s exposure to both transport infrastructure and water/flood-management projects.
Government & PSU Customer Base
NNT’s business is predominantly project-based and government/public-sector oriented.
The company states that it works with:
- Central government departments
- State government departments
- Indian Railways
- Public-sector undertakings
- Infrastructure authorities
This creates visibility from government infrastructure spending, while also creating exposure to tender cycles, execution schedules and government receivable periods.
FY25 Financial Performance
FY25 was a major growth year for NNT Developers.
According to Acuité’s December 2025 rating rationale:
| ₹ Cr | FY24 | FY25 |
|---|---|---|
| Operating Income | 144.30 | 207.14 |
| EBITDA | 18.63 | 31.42 |
| EBITDA Margin | 12.91% | 15.17% |
| PAT | 9.97 | 19.95 |
| PAT Margin | 6.91% | 9.63% |
| Total Debt | ~27.4 | 26.15 |
| Tangible Net Worth | 42.19 | 77.67 |
| Debt / TNW | 0.65x | 0.34x |
NNT’s operating income increased approximately 43.6% YoY, while PAT approximately doubled. EBITDA increased from ₹18.63 Cr to ₹31.42 Cr.
Revenue Growth
FY24 revenue:
₹144.30 Cr
FY25 revenue:
₹207.14 Cr
Growth:
~43.6%
This was supported by the company’s execution of its government and infrastructure order book.
EBITDA Growth
FY25 EBITDA:
₹31.42 Cr
versus:
₹18.63 Cr in FY24
Growth was approximately:
68.6%
More importantly, EBITDA margin improved from:
12.91% → 15.17%
Acuité attributed the improvement partly to NNT bidding for higher-margin orders.
PAT Growth
FY25 PAT:
₹19.95 Cr
FY24 PAT:
₹9.97 Cr
Therefore PAT approximately doubled year-on-year.
PAT margin improved from:
6.91% → 9.63%.
FY26 Update
The latest credit-rating information available in the sources reviewed stated that NNT had achieved:
₹91.62 Cr revenue in the first 7 months of FY26
versus:
₹74.37 Cr
during the corresponding period of the previous year.
This represents approximately 23% growth for that seven-month period.
Full-year FY26 audited numbers were not available in the sources reviewed, so FY25 remains the latest fully documented audited financial year used for the core valuation analysis.
Order Book
The order book is one of the most important parts of the NNT story.
As of 30 September 2025, Acuité reported an unexecuted order book of:
₹631.56 Cr
The rating agency stated that these orders were expected to be executed over approximately 1–2 years, providing medium-term revenue visibility.
At ₹631.56 Cr, the order book was approximately:
3.0× FY25 revenue
This is significant for a company with FY25 operating income of ₹207 Cr.
Recent Order Win – NTPC
NNT continues to receive government/PSU project orders.
An NTPC tender-award record dated 8 September 2026 shows NNT Developers receiving a contract for:
₹5.83 Cr
for construction of a Central Park and rainwater-harvesting system at NTPC Barh STPP.
This provides evidence that the company continues to participate in public-sector infrastructure projects.
Management
The company is led by promoters with significant civil-construction experience.
| Person | Position |
|---|---|
| Suyash Kumar | Chairman & Managing Director |
| Jitendra Singh | Whole-Time Director & CEO |
| Shrawan Singh | Whole-Time Director |
| Bimal Kumar | Independent Director |
| Sugan Prasad | Independent Director |
| Raveena Dugar Agarwal | Independent Director |
The company’s official board profile states that the promoter-directors have more than 16 years of experience in project execution, procurement, infrastructure operations and contract management.
Acuité separately noted that the promoters have around two decades of experience in the construction industry.
Financial Risk Profile
NNT’s balance-sheet position improved substantially during FY25.
Tangible Net Worth
FY24:
₹42.19 Cr
FY25:
₹77.67 Cr
This was supported by retained earnings as well as a ₹15 Cr equity infusion during FY25, comprising approximately ₹1 Cr equity capital and ₹14 Cr share premium.
Debt
FY25 total debt:
₹26.15 Cr
Debt/Tangible Net Worth:
0.34×
This was substantially lower than 0.65× in FY24.
Credit Rating
Acuité upgraded NNT Developers’ long-term bank-facility rating to:
ACUITE BBB / Stable
and assigned/upgraded short-term ratings to:
ACUITE A3+
The total rated bank facilities covered by the December 2025 rating action were approximately ₹136.22 Cr.
This is useful for assessing the company’s banking relationships and financial-credit profile, although a credit rating is not an equity investment recommendation.
Raw-Material Risk
Construction companies are exposed to fluctuations in:
- Steel
- Cement
- Bitumen
- Fuel
- Other construction materials
One mitigating feature of NNT’s contracts is that the company has price-escalation clauses for major raw materials in many contracts.
Acuité specifically noted that these clauses provide some protection against raw-material price volatility.
IPO / DRHP Status
This is currently one of the most important developments.
NNT Developers’ official investor-relations website contains a dedicated:
DRHP – RHP – Price Band & AV
section.
The company’s official disclosure states that the Draft Red Herring Prospectus is dated 30 September 2025 and was filed with SEBI, BSE and NSE.
The company therefore has a formal IPO process underway.
However:
DRHP filing ≠ IPO approval
and
DRHP filing ≠ confirmed listing date
The official website itself warns that investors should not rely solely on the DRHP for an investment decision and should review the subsequent RHP/prospectus and risk factors.
You can access the company’s official investor-relations and prospectus section here:
NNT Developers – DRHP / RHP / Prospectus
Bonus Issue
A 3:1 bonus issue has been reported for NNT Developers.
This means:
1 existing share → 3 bonus shares
or:
4 shares after the bonus for every 1 share held before the bonus
Unlisted-market event records identify the NNT Developers bonus as 3:1.
This is important when comparing historical EPS and share prices because the per-share figures need to be adjusted for the enlarged share count.
Current Unlisted Share Price
The latest dated indicative references available in September 2026 show NNT Developers around:
₹88/share
BuyUnlistedShares reported ₹88 as of 17 September 2026, while Planify reported ₹90 as of 12 September 2026.
Moneycontrol also showed ₹90, with an implied market capitalisation of approximately ₹360 Cr.
These are indicative OTC references, not NSE/BSE exchange quotes.
Indicative Valuation
Using approximately:
4 Cr shares
and an indicative price of:
₹88/share
the implied equity value is approximately:
₹352 Cr
At ₹90/share:
~₹360 Cr
UnlistedZone’s September 2026 reference also showed approximately ₹352 Cr market capitalisation.
FY25 Valuation Multiples
Using FY25 PAT of ₹19.95 Cr:
At ₹88/share:
₹352 Cr ÷ ₹19.95 Cr ≈ 17.6× FY25 P/E
At ₹90/share:
₹360 Cr ÷ ₹19.95 Cr ≈ 18.0× FY25 P/E
Unlisted-market sources show approximately 17.4–17.7× P/E depending on the price/reference date.
Important Bonus Adjustment
Because of the 3:1 bonus, investors should ensure that the current price and EPS being compared are on the same post-bonus basis.
The headline P/E shown by different unlisted portals may therefore differ depending on whether their data has been adjusted for the bonus.
Order Book vs Valuation
One useful way to understand NNT is to compare:
FY25 Revenue
₹207 Cr
versus
Order Book
₹631.56 Cr
The order book is approximately 3× FY25 revenue.
This provides substantial execution visibility, but order-book size alone does not guarantee future revenue or profitability. Actual conversion depends on project execution, working capital, government payments and margins.
Business Strengths
1. Strong revenue growth
FY25 operating income grew approximately 44%.
2. Strong profit growth
PAT increased from ₹9.97 Cr to ₹19.95 Cr.
3. Improving margins
EBITDA margin increased to approximately 15.17%.
4. Large order book
₹631.56 Cr unexecuted orders as of September 2025 provide substantial medium-term visibility.
5. Low reported leverage
Debt/TNW improved to 0.34× in FY25.
6. Government infrastructure exposure
Railways, roads, bridges and flood-protection projects give NNT exposure to India’s public infrastructure spending.
7. IPO pathway
The DRHP filing provides a potential future public-market liquidity event, although the timing and outcome remain subject to the IPO process.
Key Risks
1. Working-capital intensity
Acuité specifically identifies working-capital intensity as a constraint.
Civil EPC businesses often require significant funding for:
- Project mobilisation
- Materials
- Labour
- Subcontractors
- Receivables
2. Government payment cycles
A large public-sector order book does not necessarily mean immediate cash collection.
3. Execution risk
A ₹631 Cr order book needs to be converted into actual revenue and cash flow over the project cycle.
4. Construction-sector competition
Acuité identifies stiff competition as a key constraint on the business.
5. Raw-material prices
Steel, cement, fuel and bitumen prices can affect project margins, although escalation clauses mitigate part of the risk.
6. IPO uncertainty
The DRHP is an important milestone, but the eventual:
- IPO size
- Price band
- Issue date
- Listing date
- Final dilution
should not be assumed until formally announced.
7. Unlisted liquidity
Until listing, investors remain dependent on the OTC market for exits.
What Investors Should Track
For NNT Developers, the most important indicators are:
- Order-book growth
- Order-book execution
- Revenue growth
- EBITDA margin
- PAT margin
- Receivable days
- Operating cash flow
- Debt/TNW
- New railway/water/flood-protection orders
- IPO/RHP/price-band developments
Investment Framework
NNT can be viewed through four major drivers:
Infrastructure Spending
Railways + roads + bridges + water/flood protection
PLUS
Large Order Book
₹631.56 Cr as of September 2025
PLUS
Margin Improvement
FY25 EBITDA margin ~15.2%
PLUS
Potential Public-Market Liquidity
DRHP filed
LESS
Working-Capital Requirements
LESS
Execution Risk
LESS
Construction-Cycle & Competition Risk
This provides a more useful framework than looking at the current unlisted price alone.
UnlistedCart Takeaway
NNT Developers has evolved from a relatively small Bihar-based civil contractor into a broader infrastructure EPC company with exposure to railways, roads, bridges, flood protection, water infrastructure and government buildings.
FY25 was particularly strong:
Revenue: ₹207.14 Cr
EBITDA: ₹31.42 Cr
PAT: ₹19.95 Cr
EBITDA Margin: 15.17%
PAT Margin: 9.63%
Debt/TNW: 0.34×
The ₹631.56 Cr order book as of September 2025, equivalent to roughly three times FY25 revenue, is a major source of medium-term execution visibility.
The other major development is the company’s DRHP filing dated 30 September 2025, which places NNT Developers on the IPO pathway. The company remains unlisted today, and the eventual issue timing, price band and listing outcome should be assessed only after the relevant regulatory and offer documents are finalised.
At the latest dated OTC reference of around ₹88–₹90/share, the implied market capitalisation is approximately ₹352–360 Cr, with FY25 P/E around 18× before considering any further adjustment for the 3:1 bonus issue.
The key factors to monitor are order-book execution, cash-flow conversion, working capital, margins and the next stages of the IPO process.
Disclaimer: NNT Developers Limited is currently unlisted and OTC prices are indicative, negotiated references rather than NSE/BSE quotes. The company has filed a DRHP, but a DRHP does not guarantee an IPO, approval, issue date or listing. Historical financial figures and valuation multiples should be adjusted for the reported 3:1 bonus issue before making comparisons. Unlisted shares can have limited liquidity and valuation uncertainty. This report is for informational purposes only and is not investment advice.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
