
Company: Absolute Projects (India) Limited
Formerly: Absolute Projects Private Limited / Absolute Projects (India) Private Limited
CIN: U74999DL1995PLC065160
ISIN: INE0L7001038
Incorporated: 7 February 1995
Registered Office: 4222/1 Laxmi Kunj, Ansari Road, Daryaganj, New Delhi – 110002
Corporate Office: Noida, Uttar Pradesh
Status: Unlisted Public Company / Pre-IPO
Face Value: ₹2 per share
Sector: Power Infrastructure / Engineering & EPC
Website: Absolute Projects (India) Limited – Official Website
1. Company Overview
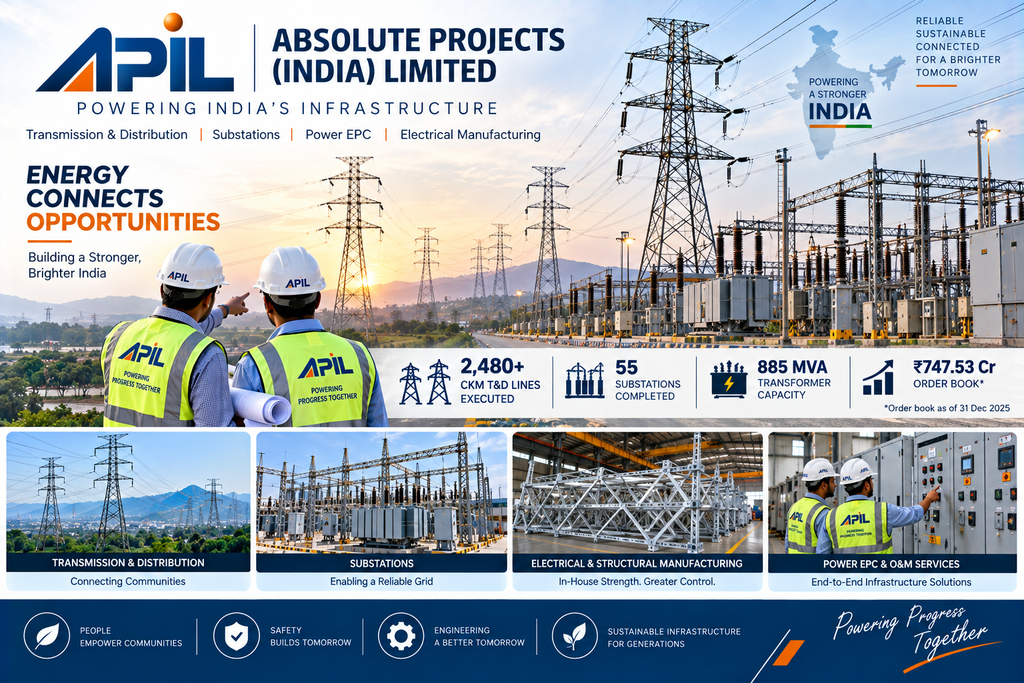
Absolute Projects (India) Limited (APIL) is an established Engineering, Procurement & Construction (EPC) company focused primarily on India’s power transmission and distribution infrastructure.
The company provides end-to-end solutions covering survey, design & engineering, procurement, installation, testing and commissioning of transmission lines, substations and distribution networks.
It also has an important backward-integration component through its own manufacturing facilities, producing electrical and structural components used in power-infrastructure projects.
The company has been operating since 1995 and converted into a public limited company in 2005.
2. What Does Absolute Projects Do?
APIL essentially operates through four major business areas:
| Business | What it does |
|---|---|
| Power EPC | Transmission lines, substations and distribution networks |
| Manufacturing | Electrical & structural components used in power projects |
| O&M Services | Operation & maintenance of transmission infrastructure |
| Civil Construction | Civil works associated with infrastructure projects |
The core revenue engine is Power EPC, which accounted for about 75% of FY25 revenue from operations and approximately 85% of the December 2025 order book.
3. Power EPC Capabilities
As of 31 December 2025, the company reported an execution track record of:
- 2,480+ circuit kilometres of transmission & distribution lines
- 55 substations completed
- Substations ranging from 33 kV to 220 kV
- 885 MVA cumulative power-transformer capacity installed
- 753,682 kVA distribution-transformer capacity
- 43.20 km of 33 kV/66 kV underground cables
- 8,311 km of low-tension distribution lines
The company works across multiple states and union territories and also has a presence in Nepal.
4. Vertically Integrated Business Model
One of APIL’s important characteristics is that it does not operate only as an EPC contractor.
It also manufactures several electrical and structural components internally, including:
- Electrical control panels
- HT switchgear
- Isolators
- Drop-out fuse sets
- Horn-gap fuse sets
- Galvanised transmission towers
- Substation structures
- Transmission-line structures
- Aerial bundled cable accessories
Its manufacturing facilities are located in Roorkee, Uttarakhand. Manufacturing Facility I has an installed capacity of approximately 6,520 MTPA.
This vertical integration can help the company control procurement, quality and project execution, while also allowing it to sell certain manufactured components to third parties.
5. Geographic Presence
APIL has executed projects across multiple Indian states and union territories, with its project footprint including regions such as:
- Rajasthan
- Punjab
- Haryana
- Uttarakhand
- Ladakh
- Other parts of India
The company also operates a branch office in Lalitpur, Nepal for power-transmission and distribution projects.
6. Client Base
The company has worked with government utilities, public-sector entities, electricity boards and private-sector infrastructure companies.
The disclosed client universe includes names such as:
- Power Grid Corporation of India
- NTPC
- Tata Power
- L&T
- Siemens
- ABB
- BSES
- State electricity utilities
- Nepal Electricity Authority
The business remains substantially dependent on a relatively concentrated customer base, which is discussed in the risk section below.
7. Order Book
The order book is one of the most important aspects of the APIL story.
According to the DRHP, the company had:
₹747.53 crore order book as of 31 December 2025
This represented more than 4x revenue from operations based on the company’s recent operating scale.
Approximately 85.35% of the order book was related to Power EPC projects, while the balance came from civil construction, O&M and supply-related contracts.
The top five projects accounted for approximately 67.94% of the total order book.
Order-book trend
| Period | Order Book |
|---|---|
| FY23 | ₹688.83 Cr |
| FY24 | ₹775.50 Cr |
| FY25 | ₹663.16 Cr |
| Dec. 2025 | ₹747.53 Cr |
The December 2025 figure indicates that the order book had recovered from the FY25 level.
8. Financial Performance
Revenue & Profit
| ₹ Crore | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue from Operations | 140.99 | 248.24 | 306.67 |
| EBITDA | 6.78 | 23.54 | 34.43 |
| PAT | 2.90 | 14.65 | 21.00 |
| PAT Margin | ~2.1% | ~5.9% | ~6.9% |
Revenue increased from approximately ₹141 crore in FY23 to ₹306.67 crore in FY25, while PAT increased from ₹2.90 crore to ₹21 crore.
This represents a substantial improvement in both scale and profitability.
9. H1 FY26 Performance
For the six months ended 30 September 2025:
| Particular | H1 FY26 |
|---|---|
| Revenue from Operations | ₹135.80 Cr |
| EBITDA | ₹14.27 Cr |
| EBITDA Margin | ~10.5% |
| PAT | ₹9.36 Cr |
| PAT Margin | ~6.9% |
The company therefore continued to remain profitable in the first half of FY26.
The DRHP’s restated financial information reports revenue from operations of ₹135.80 crore for H1 FY26 and PAT of ₹12.36 crore under its consolidated/restated presentation; investors should therefore use the DRHP’s restated financial statements as the primary reference when comparing reported numbers across databases.
10. Financial Growth
From FY23 to FY25:
Revenue: ₹141 Cr → ₹307 Cr
PAT: ₹2.9 Cr → ₹21 Cr
The improvement in profitability has been particularly significant.
The company reported an EBITDA margin of approximately 4.3% in FY23, rising to approximately 9.5% in FY25.
This reflects operating leverage and increased scale, although EPC margins remain sensitive to project execution and input costs.
11. Balance Sheet
According to the DRHP/industry data:
| Particular | FY23 | FY24 | FY25 |
|---|---|---|---|
| Net Worth | ₹41.59 Cr | ₹56.76 Cr | ₹103.26 Cr |
| Debt/Equity | 0.57x | 0.55x | 0.86x |
| Operating Cash Flow | -₹6.96 Cr | ₹11.68 Cr | -₹70.40 Cr |
The sharp increase in net worth is positive from a capital-base perspective.
However, the negative operating cash flow in FY25 is an important point to monitor, particularly because EPC businesses can require substantial working capital while executing large contracts.
12. Working Capital
Working capital is arguably one of the key areas requiring attention.
The industry report shows debtor days rising materially:
| Metric | FY23 | FY24 | FY25 |
|---|---|---|---|
| Debtor Days | 86.67 | 25.92 | 80.18 |
| Working Capital Cycle | -16.89 days | -21.07 days | 53.10 days |
The H1 FY26 data indicates that debtor days increased further.
This matters because large infrastructure contracts can involve milestone-based billing, retention amounts, certification delays and government/utility payment cycles.
13. Promoters & Management
The promoter group comprises:
- Ranjeet Singh Ola
- Deependra Singh Ola
- Monika Bhukar Ola
- Sunita Ola Dhaka
- Vaishali Ola
- Kamla Devi Ola
Ranjeet Singh Ola has more than four decades of professional experience, including more than 31 years in EPC power projects.
Deependra Singh Ola holds a Bachelor of Engineering degree and has more than two decades of experience in power EPC projects.
As of March 2025, the promoter group held approximately 89.15% of the company. The DRHP subsequently reflects changes in share count/shareholding ahead of the proposed IPO.
14. IPO Status — Major Development
This is currently one of the most important developments for APIL.
The company filed its Draft Red Herring Prospectus (DRHP) in 2026.
SEBI’s filing page records the Absolute Projects India Limited DRHP filing dated 16 April 2026, while the DRHP itself is dated 30 March 2026.
The company subsequently received SEBI observations in July 2026, according to reported regulatory-processing data.
Proposed IPO structure
The DRHP proposes:
Fresh Issue: Up to 2 crore equity shares
Offer for Sale: None
Face Value: ₹2/share
Proposed Listing: NSE & BSE
Book Running Lead Manager: Cumulative Capital Private Limited
Registrar: MUFG Intime India Private Limited
The final IPO price band, issue dates and issue size in rupee terms had not been fixed in the sources reviewed as of 22 September 2026.
15. IPO Fund Utilisation
The proposed fresh issue proceeds are intended to be used for:
1. Manufacturing expansion
Modernisation of Manufacturing Facility I.
2. New manufacturing facility
Procurement of machinery for commencing operations at Manufacturing Facility II.
3. Power EPC equipment
Purchase of equipment and machinery required for executing Power EPC projects.
4. Debt repayment
Repayment/prepayment of certain borrowings.
5. Working capital
Funding the company’s increasing working-capital requirements.
6. General corporate purposes
The exact rupee allocation will depend on the final offer document and issue size.
16. Why the IPO Matters
The proposed IPO is not simply an exit transaction for existing shareholders.
The DRHP proposes a 100% fresh issue, meaning the new capital is intended to come into the company rather than being an OFS by existing shareholders.
The stated objectives directly address three areas important for an EPC company:
Capacity → Equipment → Working Capital
This could strengthen the company’s ability to execute its existing order book if the proceeds are raised and deployed as planned.
17. Current Unlisted Share Price
As of 22 September 2026, different unlisted-market platforms were quoting slightly different indicative prices:
| Source | Indicative Price |
|---|---|
| Planify | ₹72.70 |
| Moneycontrol | ₹73.33 |
| WWIPL | ~₹75 |
| Altius / partner references | ~₹76 |
These are OTC/unlisted indicative prices and not exchange-traded prices.
Current reference valuation
Using ₹72.70 and approximately 4.30 crore outstanding shares:
Indicative market capitalisation ≈ ₹313 crore
Planify’s current data also shows market cap of approximately ₹312.71 crore.
18. Indicative Valuation
At approximately ₹72–₹73:
P/E: roughly 12.5–15x depending on the earnings/share-count methodology used by the data provider.
P/B: approximately 1.5–3x depending on whether the provider uses the latest restated book value/share count.
Moneycontrol currently displays approximately:
- P/E: 12.50x
- P/B: 2.92x
- EPS: ₹6.39
- Book Value: ₹24.99
Planify displays P/E of approximately 14.89x based on its reported earnings data.
Because the company has undergone changes in share capital and has DRHP restated financial information, investors should use the DRHP-derived post-issue capital structure rather than relying blindly on a single unlisted-market platform’s ratios.
19. Sector Opportunity
Absolute Projects operates in an area linked to India’s long-term electricity infrastructure expansion.
The company’s industry report highlights significant expected investment in India’s transmission and distribution network under the National Electricity Plan.
The company’s own DRHP identifies continued expansion of transmission infrastructure, increasing renewable-energy integration and private-sector participation in transmission projects as structural opportunities.
This creates potential demand for:
- Transmission lines
- Substations
- Distribution infrastructure
- Grid modernisation
- Renewable-energy evacuation
- Underground cabling
- Rural electrification
- Power-system upgrades
20. Key Growth Drivers
1. Large existing order book
₹747.53 crore order book at December 2025 provides substantial project visibility relative to current revenue.
2. Power infrastructure spending
India’s electricity network requires continued investment for transmission expansion, renewable integration and grid modernisation.
3. Vertical integration
In-house manufacturing gives APIL greater control over components required for EPC projects.
4. Execution track record
More than 2,480 CKM of T&D lines and 55 substations provide a meaningful operating history.
5. IPO capital
The proposed fresh issue could provide capital for manufacturing expansion, EPC equipment, debt reduction and working capital.
21. Key Risks
Customer Concentration
The top 10 customers contributed approximately 90.20% of FY25 revenue from operations.
This means the company’s revenue remains highly dependent on a relatively small group of customers.
Order-book Concentration
Approximately 85.35% of the December 2025 order book was related to Power EPC projects.
The top five projects represented approximately 67.94% of the total order book.
A delay or disruption in a major project could therefore have a meaningful impact on revenue execution.
Raw Material Exposure
Raw materials, components and stock-in-trade represented approximately 84.59% of total expenses in FY25.
This makes margins sensitive to steel, electrical components and other input-price movements.
Working Capital
FY25 operating cash flow was negative at approximately ₹70 crore, while the working-capital cycle increased significantly.
This is an important metric to monitor as the order book grows.
Competitive Tendering
Power EPC projects are often won through competitive bidding/L1-based processes.
This can put pressure on margins and exposes contractors to cost-overrun risk.
Contingent Liabilities
As of September 2025, the company reported contingent liabilities of approximately ₹47.09 crore, primarily related to bank guarantees issued for project execution and contractual commitments.
Legal/Regulatory Matters
The DRHP discloses various outstanding legal, tax and statutory proceedings involving the company, promoters and directors. These should be reviewed directly in the final offer document before making an investment decision.
22. Key Numbers at a Glance
| Parameter | Absolute Projects |
|---|---|
| Incorporation | 1995 |
| FY23 Revenue | ₹141 Cr |
| FY24 Revenue | ₹248 Cr |
| FY25 Revenue | ₹307 Cr |
| FY23 PAT | ₹2.9 Cr |
| FY24 PAT | ₹14.7 Cr |
| FY25 PAT | ₹21 Cr |
| Dec. 2025 Order Book | ₹747.5 Cr |
| Transmission Lines Executed | 2,480+ CKM |
| Substations | 55 |
| Transformer Capacity | 885 MVA |
| FY25 Debt/Equity | ~0.86x |
| FY25 Operating Cash Flow | -₹70 Cr |
| Current Indicative Price | ~₹73 |
| Indicative Market Cap | ~₹313 Cr |
| DRHP | Filed |
| IPO | 2 Cr fresh shares proposed |
| Proposed Exchanges | NSE & BSE |
23. UnlistedCart Takeaway
Absolute Projects (India) Limited is essentially a power-infrastructure EPC company with an integrated manufacturing capability.
The investment story is built around three major elements:
Power infrastructure demand + ₹747 crore order book + proposed IPO/capital expansion
The company has demonstrated significant growth in revenue and profitability between FY23 and FY25, while its execution track record includes more than 2,480 CKM of transmission/distribution lines and 55 substations.
The proposed IPO is particularly relevant because it is structured as a 100% fresh issue of up to 2 crore shares, with proceeds intended for manufacturing expansion, EPC equipment, debt reduction and working capital.
At an indicative unlisted price around ₹73, the company is being valued at roughly ₹313 crore based on current outstanding shares. The valuation therefore needs to be assessed against the company’s FY25 earnings, order-book execution and the eventual IPO valuation.
The biggest items to monitor are working-capital conversion, customer concentration, project concentration, raw-material costs and the final IPO price band.
The IPO is a meaningful potential catalyst, but the eventual listing valuation and market price cannot be known until the final offer documents and price discovery process are completed.
Important Disclaimer
Unlisted-share prices are indicative OTC references and can vary between intermediaries. They are not equivalent to NSE/BSE market prices and may have limited liquidity.
Financial figures and valuation ratios can differ between databases because of restated financials, changes in share capital and different calculation methodologies. The DRHP and audited financial statements should be treated as the primary documents.
IPO price band, subscription dates and listing date were not finalized in the sources reviewed as of 22 September 2026.
Investors should independently verify the latest DRHP/RHP, financial statements, shareholding, legal proceedings, valuation and transaction terms before investing.
This report is for information and research purposes only and should not be treated as a guaranteed return or a recommendation to buy or sell securities.
Key documents:
- Company Website – Absolute Projects (India) Limited
- SEBI – Absolute Projects India Limited DRHP filing
- NSE-hosted DRHP
- Draft Abridged Prospectus
- FY24–25 Annual Report / financial documents
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
