
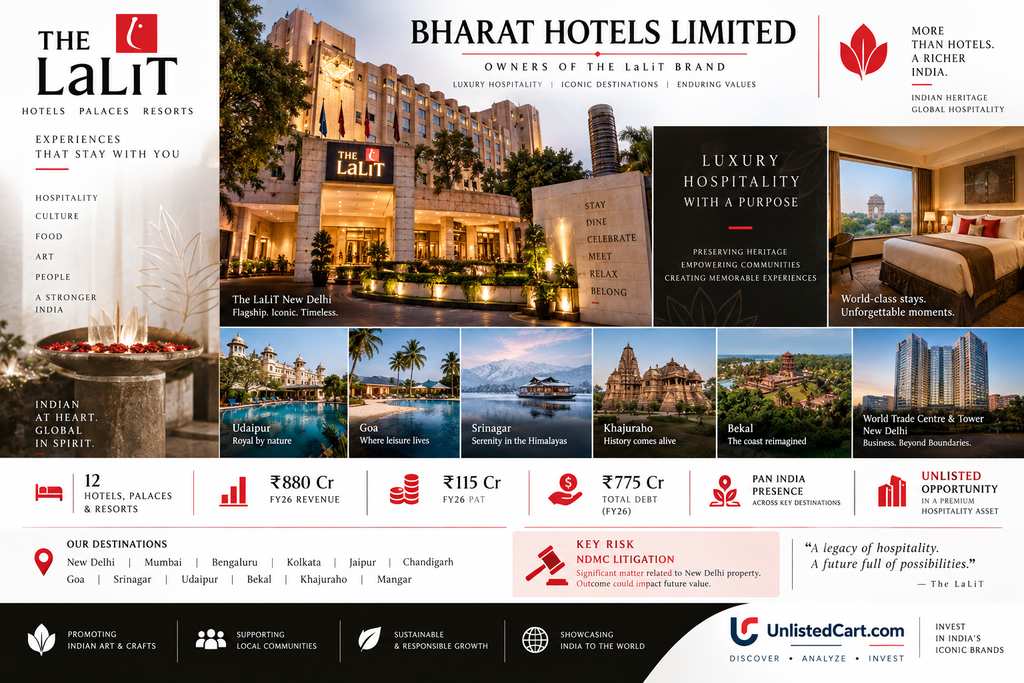
The LaLiT — Luxury Hospitality, Strategic Real Estate & Unlisted Value Opportunity
Company: Bharat Hotels Limited
Brand: The LaLiT Hotels, Palaces & Resorts
Sector: Hospitality & Hotels
Headquarters: New Delhi, India
CIN: U74899DL1981PLC011274
ISIN: INE466A01015
Incorporated: 22 January 1981
Status: Active, Unlisted Public Company
Face Value: ₹10
Shares Outstanding: 7,59,91,199
Chairperson & Managing Director: Dr. Jyotsna Suri
CEO: Vivek Shukla
Official Website – The LaLiT
Bharat Hotels Investor Relations
FY26 Annual Report – Bharat Hotels Limited
Executive Summary
Bharat Hotels Limited is the company behind The LaLiT Suri Hospitality Group, one of India’s established privately owned luxury hospitality businesses.
The company operates hotels, palaces and resorts under The LaLiT brand across major business and leisure destinations including New Delhi, Mumbai, Bengaluru, Kolkata, Jaipur, Chandigarh, Goa, Bekal, Khajuraho, Mangar, Srinagar and Udaipur. The group also has two mid-segment properties under The LaLiT Traveller brand and holds exclusive management consultancy rights for The LaLiT London.
Bharat Hotels is an interesting unlisted hospitality business because its investment proposition is not purely about hotel earnings. The company also owns/controls significant commercial and hospitality assets, including the World Trade Centre and World Trade Tower in New Delhi, while its flagship New Delhi property sits on long-term licensed land.
FY26 was a mixed year.
Consolidated revenue declined from ₹901.29 Cr to ₹879.94 Cr, largely because disturbances in Kashmir affected tourism and the performance of The Lalit Grand Palace Srinagar. However, consolidated PAT increased from ₹85.11 Cr to ₹114.86 Cr, helped primarily by lower finance costs following refinancing.
The company also completed a major fast-track amalgamation of PCL Hotels Limited, Eila Holding Limited and Kujjal Hotels Private Limited into Bharat Hotels, effective from the appointed date of 1 April 2025, with Central Government confirmation received on 7 August 2026. Management expects the restructuring to generate cost rationalisation, operational synergies and more efficient asset utilisation.
At the latest indicative unlisted price of approximately ₹367.80 per share as of 14 September 2026, Bharat Hotels carries an implied market capitalisation of approximately ₹2,795 Cr.
On FY26 consolidated earnings, this translates into approximately 24x P/E, while the stock trades at roughly 2.6x book value.
The valuation is not distressed, but it is also not excessive compared with some listed premium-hospitality companies. The major reason for the valuation discount is the company’s unlisted nature, leverage, leasehold-heavy asset base and the unresolved NDMC litigation surrounding its flagship New Delhi property.
Company Overview
Bharat Hotels Limited was incorporated in 1981 by the late Lalit Suri.
Following his death in 2006, Dr. Jyotsna Suri took over leadership of the company and subsequently developed The LaLiT into a significant domestic luxury hospitality group.
Dr. Jyotsna Suri currently serves as Chairperson & Managing Director.
The senior management team includes:
- Dr. Jyotsna Suri – Chairperson & Managing Director
- Divya Suri Singh – Executive Director
- Deeksha Suri – Executive Director
- Keshav Suri – Executive Director
- Vivek Shukla – Chief Executive Officer
- Rakesh Mitra – Chief Financial Officer
The FY26 Annual Report confirms this management structure.
The LaLiT Hospitality Portfolio
The company has built a diversified portfolio across business travel, leisure, weddings, MICE, luxury tourism and destination hospitality.
City Hotels
Major city properties include:
- The LaLiT New Delhi
- The LaLiT Mumbai
- The LaLiT Ashok Bengaluru
- The LaLiT Great Eastern Kolkata
- The LaLiT Jaipur
- The LaLiT Chandigarh
Palaces & Heritage Properties
- The LaLiT Grand Palace Srinagar
- The LaLiT Laxmi Vilas Palace Udaipur
Resorts
- The LaLiT Golf & Spa Resort Goa
- The LaLiT Resort & Spa Bekal
- The LaLiT Temple View Khajuraho
- The LaLiT Mangar
The official website currently lists these destinations and hotel formats.
Diversified Hospitality Revenue Model
Bharat Hotels does not depend exclusively on room revenue.
Its revenue streams include:
Room Revenue
Revenue from hotel rooms remains the core business.
Food & Beverage
Restaurants, bars and other F&B outlets contribute a significant portion of revenue.
Banquets & Events
Weddings, conferences, corporate events and MICE are important contributors.
Commercial Rental Income
The company earns rental and maintenance income from its Delhi commercial towers.
Management & Consultancy
The company also generates management and consultancy fees.
Membership Programmes
The group operates membership-related hospitality services.
This diversified model is valuable because hotels can generate multiple revenue streams from the same underlying property.
FY26 Financial Performance
The latest FY26 Annual Report provides the most reliable financial picture.
Consolidated Financial Performance
| Particulars | FY25 | FY26 | Change |
|---|---|---|---|
| Revenue from Operations | ₹901.29 Cr | ₹879.94 Cr | -2.4% |
| Other Income | ₹10.91 Cr | ₹10.29 Cr | — |
| Total Income | ₹912.20 Cr | ₹890.23 Cr | -2.4% |
| EBITDA | ₹390.06 Cr | ₹357.61 Cr | -8.3% |
| Finance Cost | ₹188.60 Cr | ₹135.08 Cr | -28.3% |
| PBT | ₹152.18 Cr | ₹180.68 Cr | +18.7% |
| PAT | ₹85.11 Cr | ₹114.86 Cr | +35.0% |
The official Annual Report reports FY26 consolidated revenue of ₹879.94 Cr and PAT of ₹114.86 Cr.
The Most Important FY26 Observation
At first glance, FY26 PAT growth of approximately 35% looks very strong.
However, investors should look beneath the headline number.
EBITDA actually declined from approximately:
₹390.06 Cr → ₹357.61 Cr
while finance costs declined sharply from:
₹188.60 Cr → ₹135.08 Cr
Therefore, a significant part of the improvement in bottom-line profitability came from lower finance costs rather than stronger operating performance.
This distinction is extremely important.
The company needs to demonstrate that EBITDA and hotel-level operating performance can recover rather than relying primarily on financial-cost savings.
Revenue Mix
FY26 standalone revenue included:
| Segment | FY26 Revenue |
|---|---|
| Room Rentals | ₹452.76 Cr |
| Food & Beverage | ₹235.21 Cr |
| Liquor & Wine | ₹36.22 Cr |
| Rent & Maintenance – Towers | ₹29.54 Cr |
| Banquet & Equipment Rentals | ₹27.33 Cr |
| Other Services | ₹25.94 Cr |
| Management & Consultancy Fees | ₹4.78 Cr |
| Membership Programme | ₹3.29 Cr |
Room revenue remains the largest contributor, while F&B is the second-largest component.
This diversification provides the company with multiple monetisation opportunities across its properties.
Impact of Kashmir Disruption
One of the major reasons for FY26 revenue weakness was the performance of the Srinagar property.
The company’s Annual Report states that disturbances in Kashmir adversely affected tourism for most of the year.
The impact was partially offset by better performance from other hotels, but consolidated revenue still declined.
This demonstrates both a risk and an opportunity.
Risk
Destination hotels can be affected disproportionately by geopolitical events, security issues, weather and tourism disruptions.
Opportunity
If tourism normalises, Srinagar could provide meaningful earnings recovery without requiring the company to add substantial new capacity.
Debt Reduction & Refinancing
One of the strongest developments in FY26 was balance-sheet improvement.
The company repaid its outstanding debentures to Kotak Investment Advisors Limited in January 2026 and refinanced part of its debt through public financial institutions at lower interest rates.
This resulted in a substantial reduction in finance costs.
Consolidated borrowings declined from:
₹921.89 Cr in FY25
to:
₹775.30 Cr in FY26.
At the same time, consolidated equity increased from approximately:
₹944.59 Cr → ₹1,059.10 Cr.
This reduced the approximate debt-to-equity ratio from around 0.98x to 0.73x.
Balance Sheet
FY26 Consolidated Balance Sheet
| Particular | FY26 |
|---|---|
| Property, Plant & Equipment | ₹1,523.57 Cr |
| Capital Work-in-Progress | ₹291.38 Cr |
| Goodwill | ₹84.25 Cr |
| Cash & Bank Balances | ₹78.40 Cr |
| Total Assets | ₹2,244.42 Cr |
| Total Borrowings | ₹775.30 Cr |
| Total Equity | ₹1,059.10 Cr |
The asset base demonstrates the capital-intensive nature of the hospitality business.
Capital Work-in-Progress – Ahmedabad
One area requiring close monitoring is the Ahmedabad hotel project.
The FY26 Annual Report states that a significant portion of CWIP relates to the hotel property under construction in Ahmedabad.
Construction was not completed within the stipulated period under the original land allotment terms.
Approximately ₹291 Cr of consolidated CWIP was reported at FY26.
This creates a capital-allocation question:
Can the company complete the Ahmedabad project and generate adequate returns on the capital already invested?
If the project is successfully completed, it could become a future growth asset.
If delays continue, capital remains tied up without producing operating earnings.
Commercial Real Estate Exposure
An interesting feature of Bharat Hotels is its ownership of commercial properties in New Delhi.
The company operates:
- World Trade Centre
- World Trade Tower
Together these provide more than 286,000 sq. ft. of commercial office space, according to the latest unlisted-market research.
This gives Bharat Hotels an additional annuity-like revenue stream beyond hotels.
However, FY26 revenue from rent and maintenance of the towers was only around ₹29.54 Cr, so investors should not value the company purely as a commercial real-estate business.
Major Legal Risk – NDMC Dispute
This is arguably the single biggest risk in the Bharat Hotels investment thesis.
Bharat Hotels obtained the New Delhi land from NDMC on a 99-year licence beginning in 1981.
The company constructed its hotel and two commercial towers on this land.
In February 2020, NDMC issued a demand of approximately:
₹1,063.75 Cr
for arrears of increased licence fees, interest, service tax and related amounts.
The company challenged the demand.
The Delhi High Court’s Single Judge Bench had earlier ruled in favour of the company in December 2023.
However, the Division Bench of the Delhi High Court overturned that decision on 22 April 2026.
Bharat Hotels subsequently filed a Special Leave Petition before the Supreme Court.
On 20 May 2026, the Supreme Court directed the parties to maintain status quo and Bharat Hotels to continue paying licence fees according to the licence deed.
The matter remains sub-judice.
Why This Matters
The ₹1,063.75 Cr claim is roughly comparable to the company’s entire FY26 consolidated equity.
Therefore, although management believes no liability will ultimately devolve on the company based on legal advice, investors cannot ignore the issue.
This is one of the primary reasons why a discount to asset value may be appropriate.
Other New Delhi Property Dispute
There is another matter concerning alleged unauthorised construction at the New Delhi hotel and commercial towers.
The company has challenged NDMC’s demolition-related actions before the Delhi High Court, where proceedings have been stayed.
The company states, based on legal advice, that no liability should devolve on it.
There is also a separate provisional demand involving L&DO/NDMC relating to alleged misuse/damage charges of approximately ₹543.36 Cr.
This matter is also under litigation and the company states that the relevant actions have been stayed.
For investors, these claims should be treated as material contingent risks, even though the company has not recognised them as liabilities based on its legal assessment.
Major Corporate Restructuring – 2026 Amalgamation
Bharat Hotels completed a major corporate restructuring in FY26/2026.
The following companies were amalgamated into Bharat Hotels:
- PCL Hotels Limited
- Eila Holding Limited
- Kujjal Hotels Private Limited
The transaction was completed under the Fast Track Merger route under Section 233 of the Companies Act, 2013.
Central Government confirmation was received on 7 August 2026, with an appointed date of 1 April 2025.
Why This Matters
Management expects the amalgamation to provide:
- Cost rationalisation
- Simplification of group structure
- Operational synergies
- Better asset utilisation
- Lower administrative overhead
- More efficient capital deployment
This could become an important medium-term catalyst.
Management Quality
The business has remained under the leadership of the Suri family for decades.
Dr. Jyotsna Suri has been associated with Bharat Hotels since its inception and took over as Chairperson & Managing Director in 2006.
The company has also strengthened professional management, with Vivek Shukla serving as CEO and Rakesh Mitra as CFO.
The combination of promoter continuity and professional operating management is positive for a long-duration hospitality asset business.
Industry Opportunity
India’s hospitality sector has attractive structural growth drivers.
Domestic Tourism
Rising disposable incomes and increasing domestic travel support hotel demand.
Business Travel
India’s expanding corporate economy continues to generate demand for business hotels.
MICE
Meetings, incentives, conferences and exhibitions provide high-value room and F&B opportunities.
Weddings
India’s premium wedding market is becoming increasingly organised and destination-oriented.
Luxury Tourism
India’s heritage, wellness and cultural tourism offer opportunities for premium hotels and palace properties.
International Tourism
Growing international connectivity and India’s increasing attractiveness as a business and tourism destination can support higher occupancy and room rates.
Bharat Hotels itself identifies business travellers, MICE, leisure travellers and premium weddings as key demand segments.
Competitive Advantages
1. Established Luxury Brand
The LaLiT has developed a recognisable domestic luxury hospitality brand.
2. Strategic Locations
The company operates in major business and leisure destinations.
3. Heritage Properties
Properties such as Udaipur and Srinagar offer differentiated experiences that are difficult for new entrants to replicate.
4. Diversified Revenue
Revenue comes from rooms, F&B, banquets, rentals and other services.
5. Commercial Real Estate
The Delhi commercial towers provide additional income outside conventional hotel operations.
6. Long Operating History
Bharat Hotels has operated for more than four decades.
7. Professional Management
The company combines promoter leadership with professional hospitality management.
Current Indicative Unlisted Share Price
Bharat Hotels is not listed on NSE or BSE.
The latest private-market references available in September 2026 show prices around:
₹355–₹368 per share.
Planify reported approximately ₹367.80 per share as of 14 September 2026, while UnlistedZone reported approximately ₹355 per share around the same period. These are indicative OTC/private-market levels and are not exchange-traded prices or firm offers.
Bharat Hotels – Planify Research Page
Bharat Hotels – UnlistedZone Indicative Price
Indicative Valuation
Using ₹367.80 as the reference price:
Shares outstanding: 7.599 Cr
Implied market capitalisation: approximately ₹2,795 Cr
FY26 consolidated PAT: ₹114.86 Cr
Therefore:
Approximate P/E
₹2,795 Cr ÷ ₹114.86 Cr
= ~24.3x FY26 earnings
Book Value
FY26 consolidated equity is approximately ₹1,059 Cr.
Approximate book value per share:
₹139–140
At ₹367.80:
P/B ≈ 2.6x
Enterprise Value
Approximate net debt:
₹775 Cr − ₹78 Cr cash
= ~₹697 Cr
Approximate EV:
₹2,795 Cr + ₹697 Cr
= ~₹3,492 Cr
Against FY26 EBITDA of approximately ₹358 Cr:
EV/EBITDA ≈ 9.8x
These calculations are approximate and should be updated using the actual executable unlisted price at the time of transaction.
Valuation Interpretation
At approximately 24x FY26 earnings, Bharat Hotels is not a deep-value hotel stock.
However, the valuation becomes more interesting when considering the underlying asset base.
The company owns/controls:
- Luxury hotels
- Heritage properties
- Resorts
- Commercial towers
- Development assets
- Strategic land/property interests
Therefore, a pure P/E comparison may not fully capture the investment case.
SOTP Approach
A better approach would be:
Value mature hotels
Value commercial towers
Value development assets
Value strategic land/property interests
−
Net debt
−
Potential contingent liabilities
−
Holding-company/unlisted liquidity discount
This could produce a more meaningful intrinsic-value framework.
Investment Positives
1. Established luxury hospitality franchise
The LaLiT has a meaningful domestic brand presence.
2. Diversified property portfolio
City hotels, resorts and heritage properties reduce dependence on a single destination.
3. Debt reduction
Consolidated borrowings declined by approximately ₹147 Cr in FY26.
4. Lower finance cost
Refinancing materially reduced interest expense.
5. Strong PAT recovery
FY26 consolidated PAT increased to approximately ₹115 Cr.
6. Corporate restructuring
The 2026 amalgamation should simplify the group structure and potentially improve asset utilisation.
7. Commercial real-estate income
The Delhi commercial towers provide diversification.
8. Tourism recovery potential
A normalisation of Kashmir tourism could provide additional upside.
9. Hospitality industry tailwinds
India’s domestic and international tourism opportunity remains structurally attractive.
Key Risks
1. NDMC Litigation
The ₹1,063.75 Cr licence-fee claim is the biggest balance-sheet/legal risk.
2. Additional Property Claims
The company faces other disputes concerning the New Delhi property.
3. Leverage
Although debt declined, ₹775 Cr of consolidated borrowings remains significant.
4. Operating Performance
FY26 revenue and EBITDA declined.
PAT growth was driven substantially by lower finance costs.
5. Geographic/Political Risk
Properties such as Srinagar can be disproportionately affected by regional disruptions.
6. Ahmedabad Project
Capital remains tied up in the Ahmedabad development, with delays creating execution and capital-efficiency risks.
7. Unlisted Liquidity
There is no continuous exchange market.
Finding a buyer can take time and transaction prices can vary substantially.
8. No Assured IPO Catalyst
Investors should not assume that Bharat Hotels will necessarily undertake an IPO simply because it is an attractive unlisted hospitality business.
There is no confirmed IPO date identified in the current research.
Key KPIs to Monitor
For future annual reports, investors should track:
Occupancy
Average Room Rate (ARR)
RevPAR
Revenue per available room
F&B revenue
EBITDA margin
Finance cost
Net debt
Hotel-level ROCE
Cash flow from operations
Same-property growth
Commercial rental income
Development asset utilisation
Kashmir property performance
NDMC litigation developments
Potential Re-Rating Triggers
The major catalysts could include:
- Successful resolution of the NDMC dispute
- Recovery in Srinagar tourism
- Continued debt reduction
- Lower finance costs
- EBITDA recovery
- Successful completion of Ahmedabad project
- Improved occupancy and ARR
- Higher RevPAR
- Strong wedding/MICE demand
- Benefits from the 2026 amalgamation
- Better asset utilisation
- Potential strategic investment or future listing announcement
What Could Go Wrong?
The most important risk is that investors may value Bharat Hotels based on the gross value of its properties without sufficiently adjusting for:
Debt + lease obligations + litigation + development risk + unlisted liquidity.
The New Delhi property is particularly important.
A favourable resolution of the NDMC dispute could materially improve investor confidence.
An adverse outcome, on the other hand, could have a very significant impact because the disputed amount is large relative to the company’s equity.
Therefore, investors should apply a material holding-company/legal-risk discount when conducting an asset-based valuation.
Investment View
Bharat Hotels is an interesting asset-backed hospitality business with a recognised luxury brand, but it is not a straightforward high-growth story.
The FY26 numbers tell a nuanced story.
Positive
PAT increased strongly.
Debt declined.
Finance costs declined.
Corporate restructuring was completed.
The company has valuable hospitality and commercial assets.
Negative
Revenue declined.
EBITDA declined.
Srinagar remained affected by regional disruption.
The Ahmedabad project remains delayed.
The NDMC dispute remains unresolved.
The company remains unlisted and relatively illiquid.
At around ₹355–₹368 per share, the company trades at approximately 24x FY26 earnings and 2.6x book value based on the latest available consolidated numbers.
That valuation is reasonable only if investors believe that:
hotel operating performance will recover + debt will continue falling + asset utilisation will improve + legal risks will remain manageable.
Overall Assessment
Business Quality: ★★★★½
Brand Strength: ★★★★½
Asset Quality: ★★★★½
Growth Potential: ★★★½
Financial Improvement: ★★★★
Balance Sheet: ★★★½
Management: ★★★★½
Legal Risk: ★★
Liquidity: ★★
Valuation Comfort: ★★★½
Long-Term Opportunity: ★★★★
Overall Investment View: Quality Hospitality Asset Platform — High Legal & Liquidity Risk
Bharat Hotels Limited represents a differentiated opportunity in India’s unlisted hospitality market.
The LaLiT brand, strategic hotel locations, heritage properties and commercial real-estate exposure provide a meaningful asset base.
FY26 also showed that the balance sheet can improve: debt declined, refinancing reduced finance costs and PAT increased despite lower revenue.
However, investors should not overlook the fact that operating EBITDA declined in FY26.
The biggest variable is therefore not simply whether Bharat Hotels can report higher PAT next year, but whether the underlying hotel business can generate sustainable growth in:
Occupancy → ARR → RevPAR → EBITDA → Free Cash Flow.
The NDMC litigation is the key valuation overhang. Until there is greater clarity around the New Delhi property, investors should apply a meaningful risk discount to any SOTP valuation.
At the current indicative private-market valuation, Bharat Hotels appears more suitable for investors who are comfortable with unlisted liquidity, long holding periods and legal/asset-level complexity, rather than investors looking purely for near-term earnings momentum.
The most attractive scenario would be a combination of:
resolution of the NDMC matter + recovery in Srinagar + continued deleveraging + successful asset utilisation + operating margin recovery.
That combination could create meaningful value for long-term shareholders.
Disclaimer: This report is for educational and informational purposes only and should not be considered investment advice. Unlisted-share prices are indicative and may vary materially between platforms and transactions. Investors should independently verify the latest annual report, share availability, transferability, valuation, litigation status and executable buy/sell price before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
