
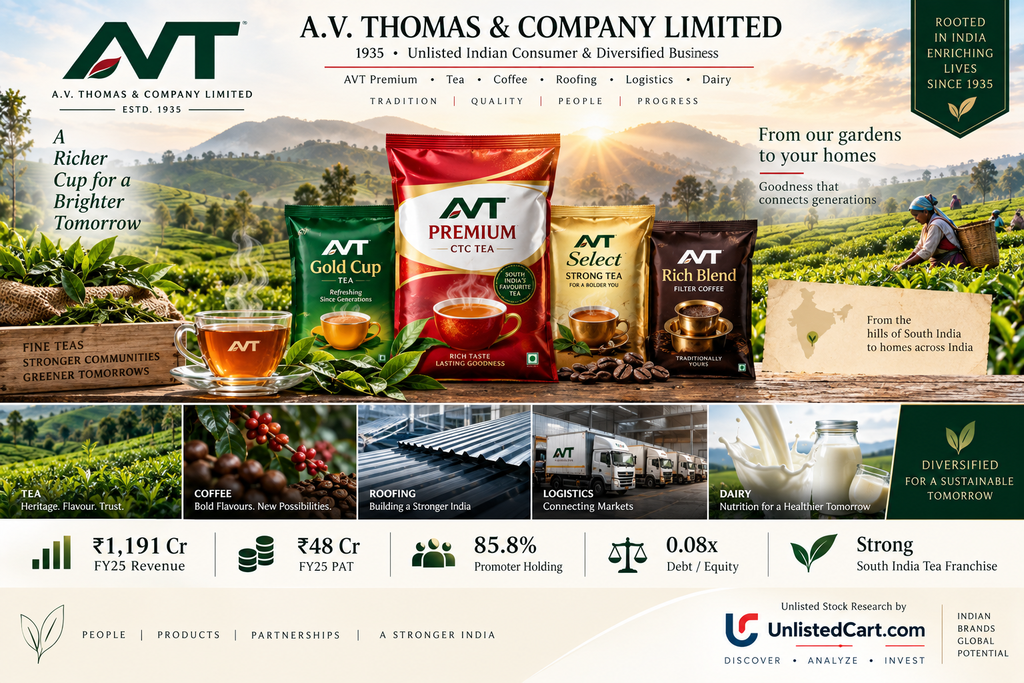
Company: A.V. Thomas and Company Limited
CIN: U51109KL1935PLC000024
ISIN: INE944K01010
Incorporated: 21 January 1935
Registered Office: Alappuzha, Kerala
Face Value: ₹10 per share
Shares Outstanding: 4,56,540
Listing Status: Unlisted
Industry: FMCG, Tea, Coffee, Agribusiness, Roofing & Logistics
Latest Financial Year Analysed: FY2024-25
Executive Summary
A.V. Thomas and Company Limited, popularly known as AV Thomas, is one of the oldest Indian business houses in the tea and consumer-products ecosystem, with roots going back to the plantation business established by A.V. Thomas. The company today operates through multiple business divisions including consumer products, roofing, logistics and dairy, while also having exposure to associate companies and investments.
The company’s strongest business remains its consumer-products division, particularly AVT Premium, which the company states continues to be the market leader in Kerala. During FY2024-25, consumer-products turnover increased by 11%, although profitability declined by 14% because of a sharp increase in tea costs. The roofing division returned to profitability, logistics volumes improved and the dairy division remained profitable despite competitive pressure.
Financially, FY2024-25 was a mixed year. Revenue from operations increased from ₹1,078.87 Cr to ₹1,190.83 Cr, while consolidated profit after tax declined from approximately ₹63.77 Cr to ₹48.07 Cr. The decline was largely due to higher tea costs and losses/negative contribution from associates.
At an indicative unlisted price of around ₹26,000 per share, the company is valued at approximately ₹1,187 Cr, equivalent to around 24.7x FY25 consolidated earnings and 3.0x book value. However, another unlisted-market source currently shows an indicative ask of around ₹12,500, highlighting the very high price dispersion and illiquidity that can exist in unlisted shares.
Company Overview
A.V. Thomas and Company Limited was incorporated in 1935 and is part of the broader A.V.T. Group.
The business has evolved from plantation-related activities into a diversified operating company with exposure to consumer products, tea, coffee, dairy, roofing materials, logistics and investments.
The company’s principal operating divisions are:
- Consumer Products
- Roofing
- Logistics
- Dairy
The company also consolidates/recognises its interests in associate companies including:
- AVT Gavia Foods Private Limited
- A.V. Thomas Investments Company Limited
- Grover Zampa Vineyards Limited
The FY2024-25 annual report confirms that the company prepared consolidated financial statements incorporating these associate companies.
Business Model
1. Consumer Products – Core Business
The consumer-products division is the most important part of AV Thomas.
The portfolio includes:
- Packaged tea
- Bulk tea
- Coffee
- Tea and coffee premixes
- Other consumer products
The flagship brand is AVT Premium.
The company reported that its consumer-products division achieved an 11% increase in turnover during FY2024-25, supported by higher volumes and realisations. However, profitability declined by 14% because of an exceptional increase in tea costs.
AVT also reported continued leadership for AVT Premium in Kerala and improved market share for AVT Gold Cup in Tamil Nadu. Sales in Andhra Pradesh, Karnataka, Odisha and exports were relatively steady.
This gives the company a particularly strong regional position in South Indian tea markets.
2. Roofing Division
AV Thomas also operates a roofing-related business involving products such as aluminium and GI sheets.
FY2024-25 was a significant improvement for this division.
According to the annual report:
- Value increased by approximately 8%
- Volume increased by approximately 22%
- The division returned to profitability
This suggests that the roofing business could provide additional earnings diversification beyond tea.
3. Logistics Division
The company operates logistics and clearing & forwarding-related activities.
The annual report specifically notes improvement in logistics operations, particularly in sea cargo volumes during FY2024-25.
This business can benefit from increasing movement of consumer goods and commodities, although margins are typically lower than branded FMCG businesses.
4. Dairy Division
The dairy business operates in a competitive environment.
During FY2024-25, sales were affected by:
- Competitive market conditions
- Supplier-related issues
Despite these challenges, overall profitability remained satisfactory and showed marginal improvement.
Associate Companies and Investment Exposure
One of the more interesting aspects of AV Thomas is that the company is not purely a tea/FMCG business.
Its consolidated accounts include interests in:
AVT Gavia Foods Private Limited
AVT Gavia operates in the food and beverage space and is associated with products including ready-to-eat/processed foods and snack products.
FY2025 revenue was approximately ₹27.84 Cr, up around 7% from the previous year. However, profitability remained weak, with FY2025 PAT reported at approximately -₹1.63 Cr by public financial databases.
This is currently more of an optionality business than a major earnings contributor.
Grover Zampa Vineyards Limited
AV Thomas also has an interest in Grover Zampa Vineyards, an Indian wine business.
Grover Zampa reported FY2025 revenue of approximately ₹64.64 Cr, a significant increase over FY2024. However, profitability remained negative and the company continued to require capital support.
An important development was a substantial equity infusion from the AV Thomas Group in FY2025. Infomerics reported that ₹99.10 Cr was infused by the AV Thomas Group, while promoter loans of ₹25.17 Cr were converted into equity. This strengthened Grover Zampa’s capital structure but also demonstrates that the associate can require meaningful capital allocation.
A.V. Thomas Investments Company Limited
The company also has an interest in A.V. Thomas Investments Company Limited, further increasing the investment/holding-company characteristics of the business.
FY2024-25 Financial Performance
Consolidated Profit & Loss
| Particular | FY2024 | FY2025 |
|---|---|---|
| Revenue from Operations | ₹1,078.87 Cr | ₹1,190.83 Cr |
| Other Income | ₹15.50 Cr | ₹18.88 Cr |
| Total Income | ₹1,094.37 Cr | ₹1,209.80 Cr |
| PBT before associate impact | ₹87.01 Cr | ₹74.06 Cr |
| Associate/JV impact | -₹0.85 Cr | -₹7.55 Cr |
| Consolidated PBT | ₹86.16 Cr | ₹66.51 Cr |
| Consolidated PAT | ₹63.77 Cr | ₹48.07 Cr |
| EPS | ₹1,388.84 | ₹1,052.85 |
Figures are based on FY2024-25 consolidated financial statements.
Revenue Growth
Revenue increased approximately:
₹1,078.87 Cr → ₹1,190.83 Cr
This represents growth of roughly 10.5%.
However, earnings moved in the opposite direction.
PAT Growth
Consolidated PAT declined:
₹63.77 Cr → ₹48.07 Cr
This represents a decline of approximately 24.6%.
Therefore, the major issue in FY2024-25 was not topline growth but profit conversion.
Why Did Profitability Decline?
The company’s own commentary provides an important explanation.
The consumer-products division experienced an exceptional increase in tea costs, which reduced profitability despite an 11% increase in turnover.
Additionally, the consolidated financial statements show a significantly higher negative contribution from associates.
This means investors should distinguish between:
Operating business performance
and
Consolidated reported earnings after associate contributions.
That distinction is important when valuing AV Thomas.
Balance Sheet Analysis
FY2025 consolidated assets stood at approximately ₹499.74 Cr, compared with ₹426.67 Cr in FY2024.
Major Assets – FY2025
| Asset | Approx. Value |
|---|---|
| Property, Plant & Equipment | ₹86.58 Cr |
| CWIP | ₹4.82 Cr |
| Investments – Non-current | ₹45.62 Cr |
| Inventories | ₹159.46 Cr |
| Current Investments | ₹130.69 Cr |
| Trade Receivables | ₹43.88 Cr |
| Cash & Cash Equivalents | ₹2.05 Cr |
| Total Assets | ₹499.74 Cr |
The company therefore has a meaningful investment portfolio alongside its operating assets.
Debt Position
AV Thomas remains relatively conservatively leveraged.
FY2025 consolidated borrowings were approximately:
- Non-current borrowings: ₹1.94 Cr
- Current borrowings: ₹24.93 Cr
Total borrowings were therefore approximately ₹26.87 Cr.
The reported debt-equity ratio was approximately 0.08x.
This is a significant positive from a balance-sheet perspective.
The company therefore does not appear to be heavily dependent on debt financing.
Liquidity
The current ratio declined from approximately 6.02x to 3.55x, but remains comfortable.
The decline was largely associated with increased short-term borrowings, working-capital requirements and lower cash balances.
Cash and cash equivalents fell from approximately ₹15.97 Cr to ₹2.05 Cr.
This deserves monitoring because the company simultaneously increased capital expenditure and investment activity.
Cash Flow Analysis
Operating cash flow remained positive at approximately:
₹37.75 Cr in FY2025
versus:
₹69.59 Cr in FY2024.
The decline was significant and was driven partly by higher working-capital requirements.
Inventory absorbed approximately ₹19.49 Cr of cash while receivables absorbed another ₹9.76 Cr.
At the same time, the company invested heavily.
Capital expenditure on PPE was approximately ₹64.53 Cr during FY2025 compared with only ₹5.70 Cr in FY2024.
This is an important point for investors.
The company was not simply distributing cash; it was also deploying capital toward assets and investments.
Dividend Track Record
AV Thomas has demonstrated a strong dividend-paying history.
For FY2024-25, the company paid:
₹150 per share interim dividend
and recommended:
₹150 per share final dividend
for an aggregate dividend of:
₹300 per share
This represents a 3,000% dividend on the ₹10 face value.
At an indicative ₹26,000 share price, the ₹300 dividend represents a yield of only around 1.15%.
Therefore, while the dividend is very high relative to face value, the actual yield at the current unlisted valuation is relatively modest.
Shareholding Pattern
As of 31 March 2025:
| Category | Shares | Holding |
|---|---|---|
| Promoters | 3,91,747 | 85.81% |
| Public | 64,793 | 14.19% |
| Total | 4,56,540 | 100% |
The promoter holding of approximately 85.8% indicates very high ownership concentration.
This provides strong promoter control but also contributes to limited free float and poor liquidity.
Competitive Advantages
1. Strong regional tea franchise
AVT Premium has a strong presence in Kerala and the company has been improving its position in Tamil Nadu with AVT Gold Cup.
2. Long operating history
The company has been operating since 1935, giving it considerable experience in tea, consumer products and related businesses.
3. Strong promoter ownership
Promoters hold approximately 85.8%, aligning promoter interests with long-term ownership.
4. Low financial leverage
Debt-equity of around 0.08x provides significant financial flexibility.
5. Diversified earnings base
Unlike a pure tea company, AV Thomas has exposure to:
- FMCG
- Tea
- Coffee
- Dairy
- Roofing
- Logistics
- Investments
- Food products
- Wine through an associate
6. Significant investment portfolio
The company holds meaningful financial investments, which adds another layer to the valuation.
Key Growth Drivers
Branded FMCG expansion
Growth in packaged tea, coffee and value-added beverage products could support future revenue growth.
Tamil Nadu expansion
Management specifically highlighted improvement in market share for AVT Gold Cup in Tamil Nadu. Further expansion beyond Kerala could increase the addressable market.
Tea price normalisation
FY2025 profitability was affected by unusually high tea costs.
If input costs normalise while selling prices remain stable, operating margins could recover.
Roofing recovery
The roofing division returned to profitability and recorded strong volume growth.
Logistics growth
Improving sea-cargo volumes could provide another source of incremental revenue.
Associate-company optionality
AVT Gavia and Grover Zampa provide exposure to processed foods and wine.
However, these should currently be considered optionality rather than the core investment thesis.
Key Risks
1. Tea commodity-price volatility
This is perhaps the most important operational risk.
FY2025 demonstrates that higher tea procurement costs can materially reduce profitability even when revenue grows.
2. Low consolidated earnings conversion
Revenue grew more than 10% in FY2025, but consolidated PAT fell nearly 25%.
This demonstrates the sensitivity of earnings to margins and associate-company performance.
3. Associate-company losses
AVT Gavia remained loss-making, while Grover Zampa also remained under profitability pressure.
Continued capital requirements could reduce the value created for shareholders.
4. Working-capital intensity
Inventory and receivables consumed significant cash during FY2025.
5. Cash reduction
Cash fell sharply during the year while capital expenditure and investment activity increased.
6. Unlisted-market liquidity
The shares are not traded on NSE/BSE.
This means investors may face:
- Limited buyers
- Wide bid-ask spreads
- Long exit periods
- Price discrepancies between dealers
- Difficulty establishing a real-time market price
7. Valuation risk
At certain unlisted-market quotes, AV Thomas can trade at a substantial premium to book value and at a relatively demanding earnings multiple.
The investment case therefore depends heavily on the entry price.
Current Unlisted Share Price
There is a significant discrepancy in current unlisted-market quotes.
One unlisted-market source reports:
₹26,000 per share
with:
- Market capitalisation: ~₹1,187 Cr
- EPS: ₹1,052.85
- P/E: ~24.69x
- Book value: ₹8,591.53
- P/B: ~3.03x
The source also reports a lot size of 100 shares.
Another unlisted-share price list dated 14 September 2026 shows AV Thomas at approximately ₹12,500 per share, with a minimum lot of 10 shares. It explicitly describes these figures as indicative off-market asks rather than exchange-traded prices.
This is an extremely important observation.
Indicative Price Range
₹12,500 – ₹26,000 per share
The difference demonstrates why investors should not value an unlisted company purely based on a single dealer quotation.
Valuation Analysis
With approximately 4.565 lakh shares outstanding and FY2025 consolidated PAT of approximately ₹48.07 Cr, the valuation can be analysed through earnings multiples.
Earnings-Based Valuation
| P/E Multiple | Implied Equity Value | Approx. Value/Share |
|---|---|---|
| 15x | ₹721 Cr | ₹15,800 |
| 20x | ₹961 Cr | ₹21,100 |
| 25x | ₹1,202 Cr | ₹26,300 |
| 30x | ₹1,442 Cr | ₹31,600 |
The calculation uses FY2025 consolidated PAT of approximately ₹48.07 Cr and 4,56,540 shares.
At around ₹26,000 per share, the market is effectively assigning approximately 25x consolidated FY2025 earnings.
That is not an inexpensive valuation for a business whose consolidated earnings declined during FY2025.
However, the valuation also reflects:
- Strong brand equity
- Low leverage
- Long operating history
- Investment assets
- Regional market leadership
- High promoter ownership
- Potential margin recovery
Book Value Perspective
FY2025 consolidated other equity was approximately ₹391.78 Cr and equity share capital was approximately ₹0.46 Cr.
This gives total equity of roughly ₹392.24 Cr, or approximately ₹8,591 per share.
At ₹26,000 per share:
P/B ≈ 3.0x
At ₹12,500:
P/B ≈ 1.45x
Therefore, the investment attractiveness changes dramatically depending on the actual acquisition price.
What Makes AV Thomas Interesting?
The interesting part of AV Thomas is that it should not be looked at simply as a tea company.
It is better viewed as:
Branded FMCG + tea franchise + diversified operating businesses + investment assets
The consumer-products business provides the primary operating engine, while the other businesses and investments provide diversification and potential optionality.
Investment View
Positive Factors
- Established business dating back to 1935
- Strong AVT Premium brand
- Market leadership in Kerala
- Improving presence in Tamil Nadu
- Double-digit consumer-products revenue growth in FY2025
- Roofing division returned to profitability
- Logistics volumes improved
- Very low debt
- Strong promoter ownership
- Consistent dividend distribution
- Significant investment portfolio
- Potential margin recovery if tea costs normalise
Concerns
- FY2025 consolidated PAT declined approximately 25%
- Consumer-product profitability declined despite revenue growth
- Associate companies remain a drag
- Grover Zampa requires capital support
- Operating cash flow declined materially
- Cash balance reduced sharply
- Working capital increased
- Unlisted liquidity is limited
- Current market quotations vary substantially
- At ₹26,000, valuation is not obviously cheap
Overall Assessment
Business Quality: ★★★★☆
Brand Strength: ★★★★☆
Balance Sheet: ★★★★☆
Growth Potential: ★★★½☆
Profitability: ★★★½☆
Cash Flow: ★★★☆☆
Valuation at ₹26,000: ★★½☆☆
Unlisted Liquidity: ★★☆☆☆
Final Verdict
A.V. Thomas & Company is an interesting heritage South Indian consumer/FMCG business with a strong tea franchise and a diversified asset base.
The most attractive part of the story is the combination of:
AVT Premium + regional brand strength + low leverage + dividend history + diversified businesses + investment assets.
However, investors should not overlook the fact that FY2025 showed a decline in consolidated earnings despite strong revenue growth. Tea-cost inflation, associate-company losses and working-capital requirements affected profitability and cash generation.
The valuation therefore becomes the key factor.
At around ₹12,500, the valuation appears considerably more attractive relative to FY2025 earnings and book value.
At around ₹26,000, the stock is closer to a 25x earnings valuation, leaving less margin of safety unless earnings recover meaningfully.
For a long-term investor, the ideal approach would be to monitor:
- Recovery in consumer-product margins
- Tea procurement costs
- Growth of AVT Premium and AVT Gold Cup
- Performance of the roofing division
- Cash-flow conversion
- Capital allocation toward associates
- Profitability improvement at Grover Zampa
- Future dividend/buyback activity
- Actual transaction prices in the unlisted market
- Any future IPO/listing or corporate restructuring plans
Overall: AV Thomas is a quality legacy business with attractive underlying assets, but the investment thesis is highly price-sensitive. At a reasonable entry valuation, it can be an interesting long-term unlisted opportunity; at an aggressive valuation, the margin of safety becomes much lower.
Important Information for Investors
The unlisted share quotations mentioned above are indicative off-market prices, not NSE/BSE traded prices. Different intermediaries may quote substantially different prices depending on inventory, lot size, liquidity and buyer/seller demand.
Investors should verify the latest financial statements, share availability, transfer process, taxation, corporate actions and actual executable price before entering into any transaction.
Disclaimer: This report is prepared for informational and research purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns. Unlisted securities involve higher liquidity, valuation and exit risks compared with listed securities. Investors should conduct their own due diligence and consult a SEBI-registered investment professional where appropriate.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
