
Company: Roots Multiclean Limited
CIN: U36999TZ1992PLC003662
ISIN: INE01LF01013
Face Value: ₹10
Incorporated: 24 February 1992
Registered Office: R.K.G. Industrial Estate, Ganapathy, Coimbatore, Tamil Nadu
Status: Active Unlisted Public Company
Industry: Industrial Cleaning Equipment / Industrial Machinery
Official Company Website: Roots Multiclean Limited
Official Annual Reports: Roots Multiclean Annual Reports
Investor Contact: Roots Multiclean Investor Contact
Executive Summary
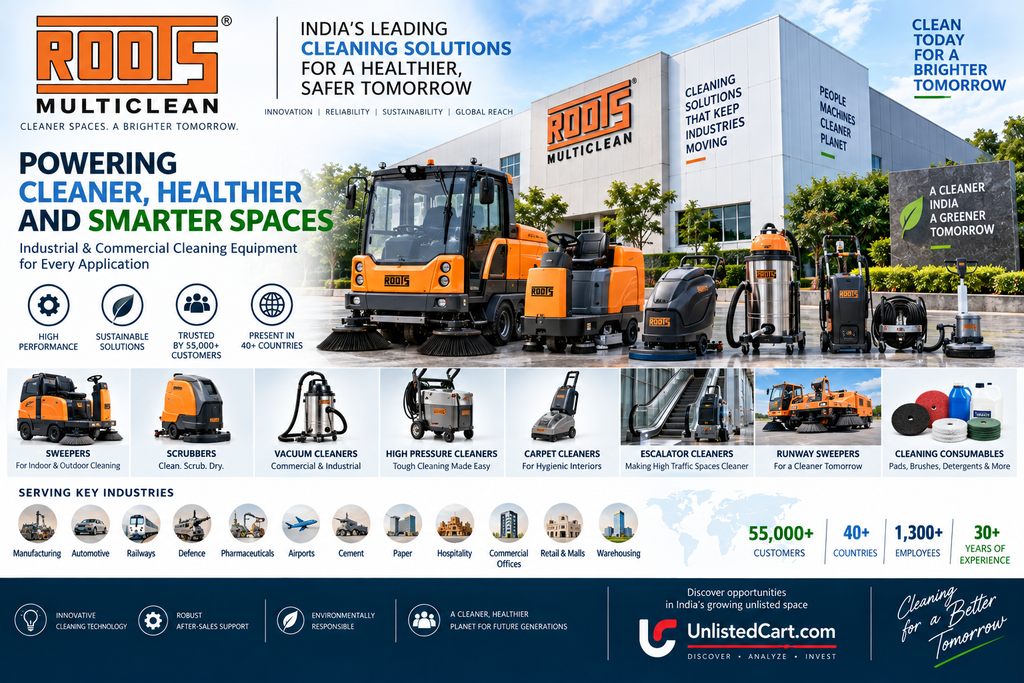
Roots Multiclean Limited is an Indian manufacturer of mechanised industrial and commercial cleaning equipment, with operations dating back to 1992.
Its product portfolio covers:
- Sweepers
- Scrubbers and scrubber-driers
- Commercial vacuum cleaners
- Industrial vacuum cleaners
- High-pressure cleaning equipment
- Carpet cleaners
- Escalator/travelator cleaners
- Steam cleaners
- Runway sweepers
- Janitorial products
- Cleaning pads and detergents
The company says it serves 55,000+ customers across India and global markets, has a presence in 40+ countries, and employs 1,300+ people. It also states that its solutions are used across manufacturing, railways, defence, pharmaceuticals, automobiles, airports, cement, paper, hospitality and other industries.
Financially, FY25 was strong:
- Revenue from operations: ₹506.38 Cr
- Total income: ₹509.95 Cr
- EBITDA: approximately ₹85.63 Cr
- PAT: ₹47.67 Cr
- EPS: ₹238.34
- Operating cash flow: ₹42.26 Cr
- Net worth: approximately ₹330.82 Cr
- Total borrowings: approximately ₹95.82 Cr
Revenue increased around 15.4% from FY24, while PAT increased around 5.7%.
The latest ICRA rating, reaffirmed in January 2026, is [ICRA]A+ (Stable) for long-term facilities and [ICRA]A1 for short-term non-fund-based facilities. ICRA highlights the company’s established brand, diversified customer base, healthy profitability and comfortable financial risk profile.
Company Overview
Roots Multiclean describes itself as India’s first mechanised cleaning-equipment manufacturer. The business started with basic sweepers and has expanded into a broad range of mechanised cleaning machines.
The company’s manufacturing and engineering capabilities are supported by its Roots Group ecosystem.
The company states that its machines are designed for challenging Indian operating conditions and that quality control is carried out from raw materials through assembly and final testing.
Business Reach
According to the company’s website:
- 55,000+ satisfied customers
- 40+ countries
- 1,300+ employees
- 30+ years of experience
- 75+ business-development executives
- 200+ service engineers
The extensive after-sales network is strategically important because cleaning equipment generates recurring requirements for service, spare parts, consumables and maintenance.
Business Model
Roots Multiclean follows a B2B/B2G industrial-equipment model with exposure to commercial and institutional customers.
Revenue comes primarily from:
1. Machine Sales
The company manufactures and sells cleaning equipment such as sweepers, scrubbers and industrial vacuum systems.
2. Industrial Cleaning Solutions
Customers can require customised equipment depending on factory size, floor type, dust load and operating environment.
3. After-Sales Service
Cleaning equipment requires regular maintenance, spare parts and servicing.
The company has more than 200 service engineers according to its website.
4. Consumables
Cleaning pads, detergents and related products provide an additional revenue stream.
5. Export Business
Roots Multiclean serves customers across 40+ countries, giving the company an opportunity to diversify beyond the Indian market.
Product Portfolio
Sweepers
The company offers:
- Walk-behind sweepers
- Ride-on sweepers
- Truck-mounted sweepers
Scrubbers
Its scrubber portfolio includes:
- Mini scrubbers
- Single-disc machines
- Walk-behind scrubber-driers
- Ride-on scrubber-driers
The company’s scrubber systems use mechanical scrubbing combined with water/detergent and suction for immediate drying.
Vacuum Cleaners
Products include:
- Commercial vacuum cleaners
- Industrial vacuum cleaners
- Compact industrial models
- Medium-duty models
- Heavy-duty models
- Fixed vacuum systems
- Oil-recycling units
- ATEX vacuum systems
- Truck-mounted vacuum systems
Specialised Cleaning Equipment
The company also offers:
- High-pressure jets
- Carpet cleaners
- Escalator/travelator cleaners
- Steam cleaners
- Runway sweepers
- Janitorial products
- Pads and detergents
Industries Served
Roots Multiclean’s website lists a broad customer-industry base:
- Manufacturing
- Automobile
- Railways
- Defence
- Pharmaceuticals
- Airports
- Cement
- Paper
- Foundries
- Commercial offices
- Retail malls
- Hospitality
This diversification reduces dependence on any single end market.
Industry Opportunity
India’s industrial cleaning-equipment market is benefiting from increasing mechanisation and higher hygiene standards.
Historically, industrial cleaning in India relied heavily on manual labour. Increasing labour costs, larger factories, stricter hygiene requirements and demand for productivity are encouraging mechanised cleaning.
Research coverage identifies Roots Multiclean among the significant players in India’s industrial cleaning-equipment ecosystem alongside international companies such as Kärcher, Nilfisk, Tennant and others.
Structural Drivers
Industrialisation
More factories, warehouses and manufacturing facilities increase demand for industrial cleaning.
Healthcare & Pharma
Hospitals and pharmaceutical facilities require higher standards of hygiene and contamination control.
Airports & Railways
Large public infrastructure facilities require mechanised cleaning because of their scale.
Warehousing & Logistics
The growth of warehouses and organised logistics increases demand for industrial floor-cleaning equipment.
Labour Productivity
Mechanised equipment can reduce dependence on manual cleaning and improve consistency.
Hygiene Awareness
The post-pandemic environment increased awareness of professional cleaning and hygiene standards.
Competitive Landscape
The market contains a combination of domestic manufacturers, importers and global OEMs.
Major international/global brands include:
- Kärcher
- Nilfisk
- Tennant
- Comac
- Hako
- NSS
Domestic manufacturers and distributors compete on:
- Price
- Local service
- Customisation
- Spare-part availability
- Delivery time
Recent industry research describes Roots Multiclean as a domestic participant competing with global industrial-cleaning-equipment manufacturers.
Roots’ Potential Differentiation
The company’s potential advantages include:
Local manufacturing
Can provide cost advantages and shorter delivery times.
Indian-condition product design
The company specifically highlights products designed for challenging Indian operating conditions.
Service network
200+ service engineers provide an important competitive advantage.
Broad product portfolio
The company is not dependent on a single cleaning-equipment category.
Roots Group ecosystem
The Roots Group provides engineering and manufacturing relationships that can support the business.
Financial Performance
Consolidated Financials
| ₹ Crore | FY24 | FY25 |
|---|---|---|
| Revenue from Operations | 439.01 | 506.38 |
| Other Income | 1.74 | 3.57 |
| Total Income | 440.75 | 509.95 |
| EBITDA* | ~74.0 | ~85.63 |
| PBT | 60.35 | 63.21 |
| PAT | 45.08 | 47.67 |
| EPS | ₹225.38 | ₹238.34 |
*EBITDA is calculated approximately as PBT + finance costs + depreciation and amortisation from the reported financial statements.
FY25 revenue increased approximately 15.4%, while PAT increased approximately 5.7%.
Margin Analysis
FY25 EBITDA calculation:
PBT: ₹63.21 Cr
Finance Cost: ₹10.04 Cr
Depreciation: ₹12.39 Cr
Therefore:
Approx. EBITDA = ₹85.63 Cr
Approximate EBITDA margin:
16.8%
PAT margin:
9.4%
This is a healthy profitability profile for a specialised industrial-equipment manufacturer.
However, the slower PAT growth relative to revenue growth indicates that investors should monitor:
- Employee costs
- Raw-material costs
- Finance costs
- Product mix
- Operating leverage
Balance Sheet
FY25 consolidated balance sheet:
| Particulars | FY25 |
|---|---|
| Total Assets | ₹515.71 Cr |
| Equity | ₹330.82 Cr |
| PPE | ₹131.02 Cr |
| Inventory | ₹156.51 Cr |
| Trade Receivables | ₹83.94 Cr |
| Cash | ₹6.90 Cr |
| Other Bank Balances | ₹25.58 Cr |
| Investments | ₹57.67 Cr |
| Borrowings | ₹95.82 Cr |
| Lease Liabilities | ₹5.75 Cr |
Debt Position
Reported borrowings increased from approximately:
₹65.63 Cr → ₹95.82 Cr
between FY24 and FY25.
However, shareholders’ equity increased to approximately ₹330.82 Cr, resulting in a reported debt/equity ratio of approximately 0.14x.
This is still a relatively comfortable leverage level.
Liquidity
Current ratio:
2.26x
Debt-equity:
0.14x
DSCR:
10.80x
ROE:
17.08%
ROCE:
15.74%
These ratios indicate a relatively healthy financial structure.
Cash Flow Analysis
FY25 operating cash flow:
₹42.26 Cr
FY24 operating cash flow:
₹40.85 Cr
Therefore, operating cash generation remained positive and broadly stable.
However, investing cash flow was:
-₹54.90 Cr
because of:
- ₹26.18 Cr addition to PPE
- ₹35.04 Cr investment additions
- ₹10.65 Cr increase in restricted/non-cash-equivalent bank balances
This indicates that the company was deploying significant capital while continuing to generate healthy operating cash flow.
Capital Expenditure
FY25 additions to PPE were approximately:
₹26.18 Cr
This indicates continued investment in manufacturing capacity and infrastructure.
For an industrial-equipment company, capex can be positive if it results in:
- Higher capacity
- Better automation
- New products
- Improved productivity
- Export growth
The key monitorable is therefore return on incremental capital.
Credit Rating
One of the strongest external indicators is the company’s current ICRA rating.
As of January 2026:
Long Term: [ICRA]A+ (Stable)
Short Term: [ICRA]A1
ICRA reaffirmed the ratings and cited:
- Established brand presence
- Diversified customer base
- Healthy profitability
- Comfortable capital structure
- Strong debt-protection metrics
ICRA Rating Details: ICRA – Roots Multiclean Rating
Shareholding
Available shareholding data indicates a concentrated ownership structure.
One reported FY24 pattern was:
| Shareholder | Approx. Holding |
|---|---|
| Hako GmbH | 26.00% |
| Roots Industries India Pvt Ltd | 18.00% |
| R. Varun Karthikeyan | 17.97% |
| K. Ramasamy | 11.75% |
| Roots Auto Products Pvt Ltd | 7.50% |
| R. Yokanayaki | 5.02% |
| Others | 13.76% |
The strategic relationship with Hako GmbH is noteworthy because Hako is an international cleaning-equipment company. The relationship also provides an international technology/business connection.
Management
Key management names reported by current unlisted-market sources include:
- R. Varun Karthikeyan – Vice Chairman & Managing Director
- K. Ramasamy – Whole-Time Director
- Jayaraman Krishnakumar – Whole-Time Director
- Ravi Kumar R – CFO
International Presence
Roots Multiclean states that it serves 40+ countries across six continents.
The company also has a wholly owned US subsidiary, Roots Multiclean Inc., which is included in the consolidated financial statements. ICRA confirms that the US subsidiary is fully consolidated.
International expansion can potentially provide:
- Geographic diversification
- Higher export volumes
- Access to international customers
- Product/technology opportunities
However, export businesses also face:
- Currency risk
- Customer concentration
- International competition
- Logistics costs
Current Unlisted Share Price
There is significant variation between available OTC references.
Reference 1 — Planify
As of 7 September 2026:
₹3,119/share
Market capitalisation:
₹623.8 Cr
Shares:
20 lakh
Current reference: Planify – Roots Multiclean Research Report
Reference 2 — Buy Unlisted Shares
As of 14 September 2026:
₹4,000/share
Indicative market capitalisation:
₹625 Cr
The platform explicitly states that this is an OTC reference price and not a stock-exchange quote or offer to deal.
Current reference: Buy Unlisted Shares – Roots Multiclean
Reference 3 — WWIPL
Current page displays approximately:
₹3,124/share
This demonstrates the price-discovery issue associated with unlisted shares.
Valuation
Using FY25 consolidated PAT:
₹47.67 Cr
and 20 lakh shares:
FY25 EPS = ₹238.34
At ₹3,124
P/E:
₹3,124 ÷ ₹238.34 ≈ 13.1x
Market capitalisation:
~₹625 Cr
At ₹4,000
P/E:
₹4,000 ÷ ₹238.34 ≈ 16.8x
Market capitalisation:
~₹800 Cr
Therefore, the difference between ₹3,124 and ₹4,000 materially changes the valuation.
Valuation Sensitivity
Based on FY25 EPS of ₹238.34:
| P/E | Implied Price |
|---|---|
| 10x | ₹2,383 |
| 12x | ₹2,860 |
| 14x | ₹3,337 |
| 15x | ₹3,575 |
| 16x | ₹3,813 |
| 18x | ₹4,290 |
| 20x | ₹4,767 |
| 22x | ₹5,244 |
This gives a useful framework for evaluating different OTC prices.
EV / EBITDA
Approximate FY25 EBITDA:
₹85.63 Cr
At ₹3,124/share:
Market cap ≈ ₹625 Cr
After considering borrowings and cash/investments, enterprise value is approximately in the ₹665–670 Cr range, depending on treatment of investments and lease liabilities.
Approximate EV/EBITDA:
~7.8x
At ₹4,000/share:
EV/EBITDA is approximately:
~9.8x
Therefore, the stock moves from a relatively moderate industrial-equipment valuation at ₹3,100–3,200 to a considerably fuller valuation around ₹4,000.
Book Value
FY25 consolidated equity:
~₹330.82 Cr
Shares:
20 lakh
Approximate book value:
₹1,654/share
Therefore:
At ₹3,124
P/B ≈ 1.89x
At ₹4,000
P/B ≈ 2.42x
This is important because some unlisted websites display different book-value/P/B calculations. For valuation work, the latest audited balance sheet and confirmed share count should take precedence.
Growth Drivers
1. Industrial Automation
As Indian factories become more automated, cleaning operations can also become more mechanised.
2. Manufacturing Expansion
Growth in manufacturing capacity across India increases the addressable market for industrial cleaning equipment.
3. Railways & Airports
Large infrastructure facilities require mechanised cleaning systems.
4. Defence & Pharma
Higher hygiene and operational standards support demand for specialised cleaning solutions.
5. Warehousing
Large warehouses and logistics facilities require efficient floor-cleaning equipment.
6. Export Expansion
40+ countries provide a significant international addressable market.
7. After-Sales Revenue
Service, spare parts and consumables can improve customer lifetime value.
8. New Product Development
Roots continues to introduce new products. Its website currently highlights recent launches including the RD120 and RB550.
Competitive Advantages
Established Brand
More than three decades of operating history.
Broad Product Portfolio
The company covers multiple cleaning categories rather than relying on a single machine type.
Service Network
200+ service engineers provide an important customer-retention advantage.
Global Presence
40+ countries.
Customer Diversification
Exposure to manufacturing, defence, railways, pharma, automobiles, airports, hospitality and other sectors.
Technology Partnerships
Historical relationships with international players such as Hako have helped strengthen product capabilities. ICRA has previously highlighted Roots’ product portfolio and foreign-player tie-ups as a strength.
Key Risks
1. Competition
The company competes with global brands including Kärcher, Nilfisk and Tennant as well as domestic manufacturers and importers.
2. Margin Pressure
Revenue grew faster than PAT in FY25.
This needs monitoring.
3. Working Capital
Inventory increased to approximately ₹156.5 Cr and receivables to approximately ₹83.9 Cr.
The company needs to ensure that growth does not consume excessive working capital.
4. Capex Requirement
Industrial manufacturing requires continuing investment in machinery and facilities.
5. Export Risk
International business introduces foreign-exchange and customer-concentration risks.
6. Unlisted Liquidity
There is no continuous NSE/BSE trading mechanism.
Exit can therefore depend on finding a buyer/dealer.
7. Price Discovery
Current references range from approximately ₹3,124 to ₹4,000, demonstrating significant OTC price dispersion.
IPO / Listing Status
Roots Multiclean is currently an unlisted public company.
There is no confirmed IPO date that should be assumed as a near-term catalyst.
The company continues to publish investor-related information and annual reports on its website.
Investors should therefore evaluate the business on its fundamentals rather than assuming an IPO will automatically provide an exit.
Investment Framework
Business
Roots Multiclean has a differentiated position in India’s mechanised industrial-cleaning-equipment market, supported by:
- 30+ years of operating history
- 40+ countries
- 55,000+ customers
- Broad product portfolio
- Service network
- Industrial customer base
- International relationships
Financial Quality
FY25 demonstrates:
- ₹506 Cr revenue
- ₹86 Cr approximate EBITDA
- ₹48 Cr PAT
- ₹42 Cr operating cash flow
- 17% ROE
- 15.7% ROCE
- 0.14x debt/equity
This represents a reasonably strong financial profile.
Valuation
At approximately ₹3,100–₹3,200, the company trades around:
13x FY25 P/E
and approximately:
1.9x FY25 book value
At ₹4,000, valuation rises to approximately:
16.8x P/E
and:
2.4x P/B
Therefore, the exact entry price becomes particularly important.
Overall Assessment
Roots Multiclean is an interesting industrial machinery and cleaning-equipment opportunity rather than a conventional consumer vacuum-cleaner company.
Its strongest characteristics are:
Established franchise
The company has been operating since 1992.
Strong customer base
55,000+ customers and presence across multiple industries.
International reach
40+ countries.
Diversified product portfolio
Sweepers, scrubbers, industrial vacuums, pressure washers and specialised cleaning systems.
Strong financial profile
₹47.7 Cr PAT, ₹42.3 Cr operating cash flow, 0.14x debt/equity and 17% ROE in FY25.
Credit strength
ICRA A+/Stable and A1 ratings were reaffirmed in January 2026.
The Main Things to Monitor
For an investor, the next few years should focus on:
Revenue growth
Can the company maintain double-digit growth?
EBITDA margin
Can the business maintain or improve its ~17% FY25 calculated EBITDA margin?
Operating cash flow
Does cash generation continue to track PAT?
Working capital
Inventory and receivables should remain under control.
ROCE
Returns on the increasing asset base should remain attractive.
Export growth
International expansion should translate into profitable growth.
Valuation
The difference between ₹3,100 and ₹4,000 materially changes the risk/reward framework.
Valuation Summary
| Parameter | At ₹3,124 | At ₹4,000 |
|---|---|---|
| Market Cap | ~₹625 Cr | ~₹800 Cr |
| FY25 EPS | ₹238.34 | ₹238.34 |
| FY25 P/E | ~13.1x | ~16.8x |
| FY25 Book Value | ~₹1,654 | ~₹1,654 |
| P/B | ~1.9x | ~2.4x |
| Approx. EV/EBITDA | ~7.8x | ~9.8x |
| Liquidity | Unlisted | Unlisted |
Final Conclusion
Roots Multiclean presents a relatively mature industrial franchise with a strong balance sheet, positive cash generation and a broad product portfolio.
The business benefits from long-term themes such as:
industrialisation + mechanisation + hygiene + infrastructure + automation + organised facility management.
The company’s 40+ country footprint, 55,000+ customer base, broad product range and 200+ service-engineer network provide meaningful competitive strengths.
The main concern is not the underlying business quality but the combination of:
- Unlisted liquidity
- OTC price dispersion
- Working-capital intensity
- Competition from global players
- Requirement for continuing capex
- Slower PAT growth relative to revenue in FY25
From a valuation perspective, ₹3,100–₹3,200 and ₹4,000 represent materially different propositions. At approximately ₹3,124, FY25 valuation is around 13x earnings; at ₹4,000 it is closer to 17x.
Therefore, a proper investor analysis should focus on future earnings growth and return on incremental capital, rather than simply extrapolating historical revenue growth.
Important Due-Diligence Checklist Before Buying
Before executing any transaction, verify:
- Latest audited financial statements
- Current shareholding
- Current share certificate / demat status
- Exact ISIN
- Current executable OTC price
- Transfer process
- Latest debt position
- Current FY26/FY27 earnings
- Dividend history
- Any proposed IPO/listing plans
- Related-party transactions
- Current customer concentration
Official investor/contact page: Roots Multiclean Investor Contact
Official annual-report page: Roots Multiclean Annual Reports
Latest ICRA rating: ICRA Roots Multiclean Rating Details
Current indicative market reference: Roots Multiclean – Planify Research
Disclaimer
This report is prepared for research and informational purposes only and should not be considered investment advice, a recommendation to buy or sell securities, or a guarantee of future returns.
Unlisted shares involve higher liquidity, valuation, disclosure and exit risks than listed securities. OTC prices are indicative and may differ substantially between intermediaries.
Financial figures should be independently verified against the latest audited company filings before making an investment or publishing a final valuation.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
