
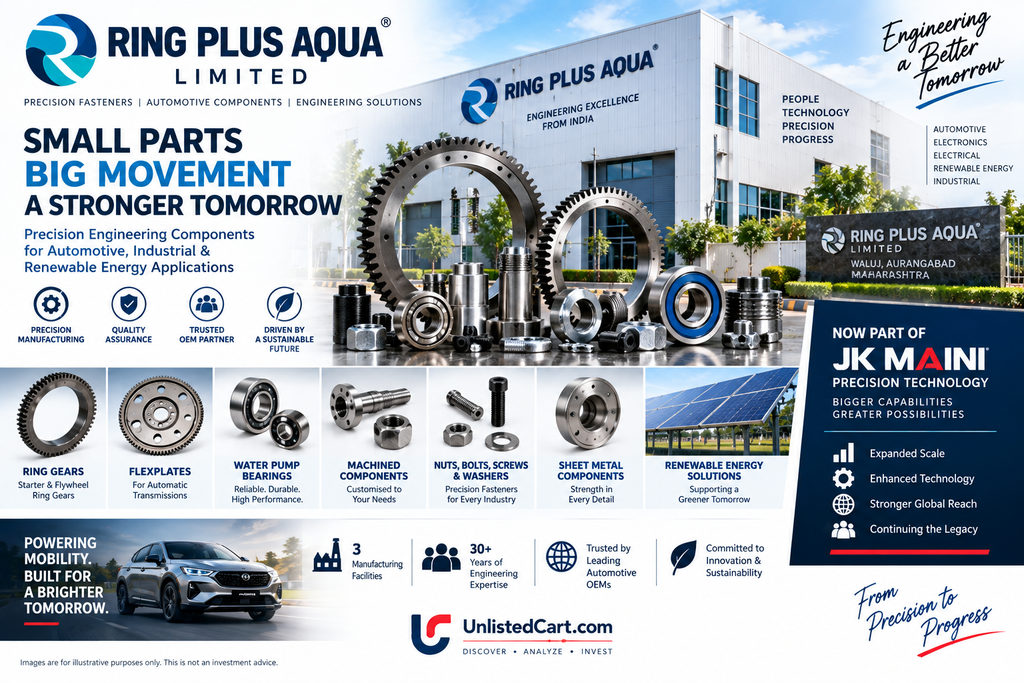
Legal Name: Ring Plus Aqua Limited
CIN: U99999MH1986PLC040885
ISIN: INE093H01012
Face Value: ₹10
Incorporated: 11 September 1986
Registered Office: Sinnar, Nashik, Maharashtra
Historical Status: Unlisted Public Company
Current Status: Amalgamated / ceased as a standalone entity
Successor Entity: JK Maini Precision Technology Limited
Executive Summary
Ring Plus Aqua Limited (RPAL) was a long-established Indian automotive-component manufacturer specialising in ring gears, flexplates, water-pump bearings and machined components.
The company was historically part of the Raymond Group’s engineering ecosystem through JK Files & Engineering and had developed a strong position in precision automotive components.
However, Ring Plus Aqua is no longer an independent company.
Under a Composite Scheme of Arrangement involving JK Files & Engineering Limited, Ring Plus Aqua Limited, Maini Precision Products Limited, JK Maini Precision Technology Limited and JK Maini Global Aerospace Limited, the Ring Plus Aqua business was transferred to JK Maini Precision Technology Limited. The NCLT Mumbai Bench approved the scheme on 4 July 2025, and the scheme became effective in July/August 2025.
The NCLT order specifically states that Ring Plus Aqua would cease to exist, with its engineering business—ring gears, flexplates, water-pump bearings and machined components—moving into the successor structure.
Therefore, this report should be viewed as a historical analysis of Ring Plus Aqua and an analysis of the business now housed within JK Maini Precision Technology, rather than as a recommendation to purchase old Ring Plus Aqua shares.
The Most Important Update for Investors
Ring Plus Aqua Has Been Amalgamated
The Composite Scheme was designed to consolidate several engineering businesses.
The resulting structure is:
JK Maini Precision Technology Limited
combining:
- JK Files & Engineering’s engineering/tool-related business
- Ring Plus Aqua’s automotive-component business
- Maini Precision Products’ precision-engineering/auto-component business
The aerospace business was separately transferred to JK Maini Global Aerospace Limited.
JK Maini Precision Technology itself describes the transaction as bringing together the expertise of JK Files, Ring Plus Aqua and Maini Precision Products into one precision-engineering platform.
Historical Company Overview
Ring Plus Aqua was incorporated in 1986 and operated from Nashik, Maharashtra.
The company manufactured specialised automotive and industrial components including:
- Starter ring gears
- Flywheel ring gears
- Flexplates
- Water-pump bearings
- Integral shaft bearings
- Sheet-metal pulleys
- Machined components
- Precision stampings
Its products were used across passenger vehicles, commercial vehicles, tractors and industrial applications.
The company’s manufacturing operations were concentrated around three facilities in the Nashik industrial region.
Business Model
RPAL’s business was primarily B2B automotive-component manufacturing.
The company supplied engineered components to vehicle manufacturers and Tier-1 suppliers.
Its competitive positioning was based on:
- Precision manufacturing
- Automotive-quality standards
- Product customisation
- Long customer relationships
- Manufacturing scale
- Engineering capabilities
The company was particularly known for ring gears, which are critical components used with engine flywheels and starter systems.
Product Portfolio
1. Starter Ring Gears
Ring gears are fitted around the flywheel and interact with the starter motor during engine ignition.
This historically formed one of RPAL’s core product categories.
2. Flexplates
Flexplates connect the engine crankshaft to automatic transmissions and are exposed to substantial mechanical stresses.
3. Water-Pump Bearings
These components are used in automotive cooling systems.
4. Integral Shaft Bearings
These provide support for rotating shafts in automotive applications.
5. Sheet-Metal Components
The company also manufactured pulleys and other precision sheet-metal components.
6. Machined Components
RPAL had capabilities in precision machining for automotive and engineering applications.
The company’s historical product portfolio is also retained within JK Maini Precision Technology’s current business platform.
Historical Financial Performance
The last standalone financial period before the merger provides the most useful picture of RPAL’s operating performance.
| ₹ Crore | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue | 374.81 | 431.12 | 429.06 |
| PAT | 39.11 | 51.47 | 5.63 |
| Revenue Growth | — | ~15% | -0.5% |
| FY24 PBT | 51.81 | 51.47 | — |
FY24 was a particularly strong year, with revenue of approximately ₹431 Cr and PAT of ₹51.47 Cr.
However, FY25 was a major deterioration in profitability.
Revenue remained broadly stable at approximately ₹429 Cr, but PAT collapsed to approximately ₹5.63 Cr.
This is an important warning for investors because simply using FY24 earnings to value the company would give a misleading picture of sustainable profitability.
FY24 Financial Analysis
FY24 revenue from operations:
₹431.12 Cr
Other income:
₹10.38 Cr
Total income:
₹441.50 Cr
Profit before exceptional items and tax:
₹80.20 Cr
Exceptional items:
₹13.87 Cr
Profit before tax:
₹66.33 Cr
PAT:
₹51.48 Cr
EPS:
₹66.37
The company therefore demonstrated that the underlying business could generate substantially higher profitability in a favourable operating environment.
FY25 Profitability Collapse
FY25 tells a very different story.
Gross revenue fell only marginally:
₹441.50 Cr → ₹429.06 Cr
But PAT fell from approximately:
₹51.47 Cr → ₹5.63 Cr
That is a decline of almost 89%.
This means that the major issue was not simply revenue growth.
The critical issue was profitability and earnings quality.
For any valuation analysis, FY25 should therefore be treated cautiously.
Balance Sheet & Capital Structure
The historical business had substantial borrowings and working-capital requirements.
MCA-related records show that RPAL had significant charges registered against its assets, although many of these charges were subsequently satisfied or transferred as part of the restructuring.
FY24 also saw a major financing event associated with the acquisition of Maini Precision Products.
RPAL acquired 59.25% of Maini Precision Products Limited for approximately ₹682 Cr, which significantly changed its balance-sheet and strategic profile before the eventual merger.
The Maini Precision Products Acquisition
One of the most important events in RPAL’s history was the acquisition of a majority stake in Maini Precision Products.
RPAL acquired:
59.25% of MPPL
for approximately:
₹682 Cr
The strategic objective was to create a larger engineering platform with exposure to:
- Precision engineering
- Automotive components
- Aerospace
- Defence
- EV components
This acquisition ultimately became part of the broader restructuring that created JK Maini Precision Technology.
Why Was the Merger Done?
The strategic logic was straightforward:
1. Scale
Combining businesses creates a much larger engineering platform.
2. Customer Diversification
The combined entity serves automotive, industrial, tools and precision-engineering markets.
3. Technology
Maini brings precision-engineering capabilities, while RPAL brings automotive-component manufacturing expertise.
4. Cross-Selling
The businesses can potentially cross-sell capabilities to existing customers.
5. Better Capital Allocation
A consolidated entity can allocate capital across businesses more efficiently.
6. Value Creation
Raymond described the restructuring as a way to create focused businesses and improve long-term value creation.
Share Exchange Ratio
Under the scheme, shareholders of Ring Plus Aqua were entitled to shares in JK Maini Precision Technology based on the approved exchange mechanism.
The reported ratio was:
607 JK Maini Precision Technology shares for every 1,000 Ring Plus Aqua shares
or approximately:
0.607 JKMPTL share for each RPAL share.
This is particularly important for historical RPAL shareholders because the old RPAL shares should not be treated as if they continue to represent an independent company.
Current Successor: JK Maini Precision Technology
The successor entity is:
JK Maini Precision Technology Limited (JKMPTL)
CIN:
U25933MH2024PLC417852
It is currently an active unlisted public company.
JKMPTL now houses the core precision-engineering and automotive-component business that includes the former RPAL operations.
Current Scale of the Successor Business
JK Maini Precision Technology reported FY26 standalone gross revenue of approximately:
₹1,672.74 Cr
and PAT of approximately:
₹39.34 Cr
FY26 consolidated gross revenue was approximately:
₹1,666.77 Cr
with consolidated PAT of approximately:
₹40.37 Cr.
The figures reflect the post-scheme structure and therefore should not be compared mechanically with historical standalone RPAL numbers.
Raymond has also indicated that JKMPTL operates at approximately 85–90% capacity utilisation, demonstrating a substantially larger engineering platform following the restructuring.
Segment Performance
The Precision Technology & Auto Components business showed encouraging momentum during FY26.
For 9M FY26:
Revenue: ₹1,225 Cr
EBITDA: ₹156 Cr
EBITDA growth: ~38%
EBITDA margin: ~12.7%
This was substantially better than the earlier profitability profile of RPAL alone.
The improvement was attributed to:
- Higher sales volumes
- Better product mix
- Operating leverage
- Integration benefits
A one-time land-sale gain also contributed during the period and should not be treated as recurring operating earnings.
Industry Opportunity
Automotive Components
India’s automotive industry continues to expand its manufacturing base.
Demand is supported by:
- Passenger vehicles
- Commercial vehicles
- Tractors
- EVs
- Export-oriented manufacturing
- Increasing localisation
RPAL’s historical products remain relevant to the broader automotive ecosystem.
Precision Engineering
The combination with Maini significantly increases exposure to precision-engineering applications.
EV Opportunity
The larger JKMPTL platform has exposure to EV-related component opportunities.
Export Opportunity
The combined engineering business has significant export exposure and operates across multiple international markets. Raymond’s investor presentation highlighted operations across 25+ countries and a substantial export contribution.
Competitive Advantages
Tata/Global OEM-Type Customer Relationships
The business has historically supplied automotive and industrial customers requiring high quality and precision.
Manufacturing Know-How
Ring Plus Aqua had decades of experience in precision automotive components.
Engineering Capabilities
The combination with Maini expands the technological capabilities of the group.
Scale
The merger creates a substantially larger engineering business compared with standalone RPAL.
Raymond Group Backing
The business remains part of the Raymond Group’s engineering structure.
Key Risks
1. RPAL Is No Longer a Standalone Investment
This is the most important point.
An investor cannot evaluate the current opportunity solely by looking at Ring Plus Aqua’s historical numbers.
2. FY25 Profit Collapse
PAT fell from approximately ₹51.5 Cr to ₹5.6 Cr in FY25.
The sustainability of earnings needs to be assessed.
3. Integration Risk
The merger combines multiple businesses with different customers, products and operating structures.
4. Capital Intensity
Auto-component and precision-engineering manufacturing require continuing investments in machinery, technology and capacity.
5. Cyclicality
Automotive-component demand is linked to vehicle production and broader economic cycles.
6. Customer Concentration
Large OEM/Tier-1 relationships can create customer-concentration risk.
7. Unlisted Liquidity
JK Maini Precision Technology remains unlisted.
There is no regular NSE/BSE price discovery for the successor company.
8. Valuation Transparency
Because JKMPTL is unlisted, investors have limited real-time price discovery and financial disclosure compared with listed peers.
Historical RPAL Unlisted Share Price
Several unlisted-share platforms still display Ring Plus Aqua prices.
For example, one platform recently quoted approximately:
₹687.90/share
with a 52-week range shown as ₹687–₹1,108.
Another platform currently shows approximately:
₹695/share
and market capitalisation of around ₹539 Cr.
⚠️ Important
These prices should not be interpreted as the current market value of an independent Ring Plus Aqua business.
The company has already been amalgamated and ceased to exist as a standalone entity.
Therefore, before any transaction, an investor must verify:
- Whether the seller is offering old RPAL shares or successor shares
- Whether the shares are legally transferable
- The exact post-merger entitlement
- Current depository records
- The successor company’s capital structure
- Applicable transaction documentation
IPO / Listing Status
Historically, the Raymond Group had explored an IPO route for JK Files & Engineering, including an OFS-based DRHP.
However, that earlier IPO process was deferred and the DRHP eventually became time-barred.
There is currently no basis to assume that Ring Plus Aqua itself will have an IPO, because the company has already been amalgamated.
The relevant entity for any future listing discussion is now JK Maini Precision Technology Limited.
Investment View
Historical Ring Plus Aqua Business
Business Quality: ★★★★☆
Historical Growth: ★★★★☆
Historical Profitability: ★★★★☆
Balance Sheet: ★★★☆☆
Valuation Visibility: ★★☆☆☆
Current JKMPTL Opportunity
The investment case is now significantly broader than Ring Plus Aqua alone.
The combined platform offers exposure to:
Precision Engineering + Auto Components + Tools + EV + Industrial Manufacturing
The scale-up is meaningful, with JKMPTL reporting FY26 revenue of roughly ₹1,673 Cr and strong capacity utilisation.
What Investors Should Track
For an investor evaluating the successor business, the following metrics are more important than old RPAL P/E ratios:
1. Revenue Growth
Can JKMPTL sustain double-digit growth?
2. EBITDA Margin
The 12%+ margin seen in 9M FY26 is an important benchmark.
3. ROCE
The business should generate adequate returns on the substantial manufacturing asset base.
4. Free Cash Flow
Growth should increasingly translate into cash generation.
5. Debt
Integration and expansion should not create excessive leverage.
6. Auto-Component Growth
Former RPAL businesses should continue to expand within the larger platform.
7. EV/Advanced Components
Exposure to EV and advanced precision components could become a significant future growth driver.
8. IPO / Listing Catalyst
A future listing of the engineering business could potentially create price discovery and unlock value, but no confirmed listing date should be assumed.
Overall Assessment
Ring Plus Aqua was a strong historical automotive-component business, but the investment story has fundamentally changed.
The most important conclusion from this research is:
Do not analyse Ring Plus Aqua today as though it were still an independent company.
The business has been consolidated into JK Maini Precision Technology Limited along with other engineering businesses.
Historically, RPAL demonstrated:
- ₹400+ Cr revenue scale
- Strong automotive relationships
- Precision manufacturing capabilities
- Ring gear leadership
- Flexplate manufacturing
- Water-pump bearing expertise
- Export potential
However, FY25 also demonstrated significant earnings volatility, with PAT falling sharply despite broadly stable revenue.
The merger potentially creates a much stronger platform because Ring Plus Aqua’s capabilities are now combined with Maini Precision Products and the relevant JK Files engineering operations.
Our View
Historical RPAL: Attractive business, but historical standalone valuation should no longer be used directly.
Current opportunity: Evaluate JK Maini Precision Technology rather than Ring Plus Aqua.
Key thesis: Scale + precision engineering + automotive components + EV opportunity + exports + potential future value unlocking.
Key risks: Unlisted liquidity, integration, capital intensity, valuation transparency and the absence of a confirmed listing catalyst.
Key Numbers
| Metric | Ring Plus Aqua |
|---|---|
| FY24 Revenue | ₹431.12 Cr |
| FY24 PAT | ₹51.47 Cr |
| FY25 Revenue | ₹429.06 Cr |
| FY25 PAT | ₹5.63 Cr |
| FY24 EPS | ₹66.37 |
| Historical Promoter Holding | ~89.07% |
| Historical Indicative Price | ~₹688–₹695 |
| Current Standalone Status | Amalgamated |
| Successor | JK Maini Precision Technology Ltd |
| NCLT Approval | 4 July 2025 |
| Scheme Effective | 2025 |
| RPAL Share Exchange | 607 JKMPTL shares / 1,000 RPAL shares |
| Current Listing | Unlisted |
| IPO Status | No confirmed IPO |
Final Conclusion
Ring Plus Aqua is a good example of why investors must check corporate actions before buying an unlisted share.
A historical unlisted price may still appear on several websites, but the company itself has ceased to exist as a standalone legal entity.
The business has moved into JK Maini Precision Technology Limited, which is now the more relevant entity for investors seeking exposure to the former Ring Plus Aqua automotive-component operations.
For an investment decision today, the next step should therefore be a JK Maini Precision Technology valuation, including its FY26 financials, capital structure, shareholding, implied valuation and comparison with listed auto-component/precision-engineering peers.
Disclaimer
This report is prepared for research and informational purposes only and should not be considered investment advice or a recommendation to buy or sell any security.
Unlisted securities carry substantial liquidity, valuation, disclosure and exit risks. Historical unlisted prices can remain displayed on intermediary websites even after significant corporate restructuring.
Investors should independently verify the latest share certificates/depository records, merger consideration, current shareholding, audited financial statements and transaction documentation before undertaking any purchase or sale.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
