
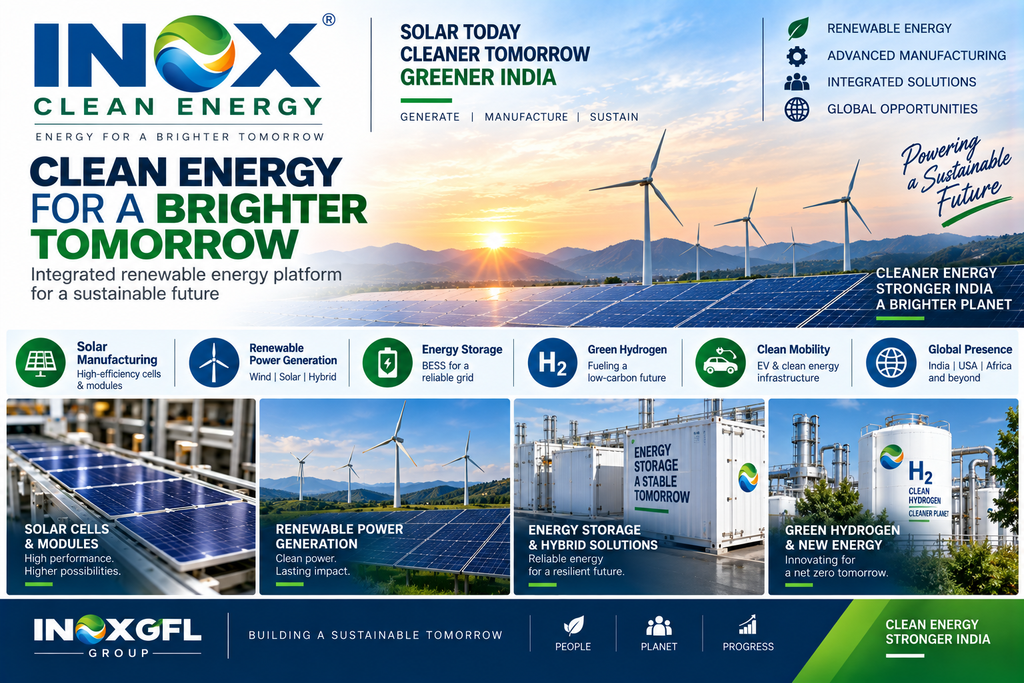
Integrated Renewable Energy Platform | Solar Manufacturing | Renewable Power Generation
CIN: U40300GJ2017PLC099852
ISIN: INE0H7K01023
Face Value: ₹1
Status: Unlisted Public Company
Group: INOXGFL Group
Registered Office: Vadodara, Gujarat
Corporate Office: Noida, Uttar Pradesh
Sector: Renewable Energy / Solar Manufacturing / Power Generation
1. Company Overview
Inox Clean Energy Limited (ICEL) is the renewable-energy platform of the INOXGFL Group, combining solar manufacturing with renewable power generation.
The company operates primarily through two businesses:
- Inox Solar – solar cell and module manufacturing
- Inox Neo Energies – renewable independent power producer (IPP)
The company’s strategy is to create an integrated renewable-energy ecosystem in which solar cells/modules can be used for its own renewable projects while power is supplied to captive users, C&I customers, third parties and power exchanges.
Inox Clean Energy – Official Website
2. Business Model
Inox Clean is different from a pure-play solar manufacturer because it is building an integrated platform across manufacturing + generation.
| Business | What it does |
|---|---|
| Solar Cells | Manufacturing high-efficiency solar cells |
| Solar Modules | Manufacturing PV modules |
| Renewable IPP | Owns/develops wind, solar & hybrid projects |
| Hybrid Power | Wind + solar combinations |
| BESS | Battery Energy Storage Systems |
| EPC | Renewable project execution |
| C&I Power | Supplies renewable power to commercial & industrial customers |
| Captive Power | Renewable power for captive consumers |
The company’s official positioning is to combine solar manufacturing with captive hybrid renewable-power generation.
3. INOXGFL Group Advantage
Inox Clean sits inside a larger renewable-energy ecosystem.
The broader INOXGFL renewable platform includes:
- Inox Wind – wind-turbine manufacturing
- Inox Green Energy Services – renewable O&M
- Inox Renewable Solutions – renewable EPC
- Inox Neo Energies – renewable IPP
- Inox Solar – solar cells/modules
- Inox Clean Energy – holding platform for the renewable IPP and solar manufacturing businesses
This gives the group exposure across manufacturing, EPC, O&M and power generation.
INOXGFL Group – Official Website
4. Renewable Energy Portfolio
According to the information disclosed around the proposed IPO, Inox Clean’s earlier portfolio consisted of:
- 157 MW operational renewable capacity
- 107 MW wind
- 50 MW solar
- 400 MW under construction
- 350 MW hybrid
- 50 MW solar
- 2.2+ GW project pipeline
These figures were reported by CareEdge in 2025 and formed part of the company’s IPO documentation.
The platform has since expanded its ambitions considerably.
Current group disclosures describe an integrated renewable platform spanning India, the US and Africa, with a significantly larger IPP and manufacturing pipeline.
5. Solar Manufacturing Expansion
This is becoming one of the biggest parts of the Inox Clean story.
Inox Solar had earlier planned:
- 4.8 GW solar-cell capacity
- 7.2 GW solar-module capacity
with phased commissioning.
The company has now substantially increased its ambitions.
Boviet Solar acquisition
In May 2026, Inox Clean announced the acquisition of assets of Boviet Solar Technology LLC in the United States.
The transaction gives Inox Clean:
3 GW operational TOPCon solar-module manufacturing capacity
and a binding agreement to acquire:
3 GW TOPCon cell manufacturing capacity, expected to be commissioned by December 2026.
Boviet Solar has historically been ranked among the leading global PV module manufacturers and has appeared in BNEF Tier-1 rankings since 2017.
This transaction also gives InoxGFL a manufacturing presence in the US market at a time when US policy is encouraging domestic solar manufacturing.
6. Long-Term Capacity Target
Inox Clean has stated an ambitious target of:
11 GW integrated solar manufacturing capacity
and
10 GW operating IPP capacity
by FY2028 across India and selected international markets including the US and Africa.
The company’s long-term objective therefore goes well beyond being a conventional solar-cell manufacturer.
It is attempting to create a vertically integrated renewable platform:
Solar Cells → Solar Modules → Renewable Power → Storage → C&I/Captive Customers
7. Financial Performance
Because Inox Clean is currently a holding/platform company undergoing rapid expansion, its standalone financial statements do not fully represent the eventual economics of the underlying renewable projects and manufacturing subsidiaries.
Available FY25 financial data shows:
₹ Crore
| Particular | FY25 |
|---|---|
| Revenue | ₹81.9 Cr |
| Other Income | ₹9.5 Cr |
| Total Income | ₹91.4 Cr |
| Operating Profit | ₹79.1 Cr |
| Interest Cost | ₹29.3 Cr |
| Depreciation | ₹13.8 Cr |
| PBT | ₹36.0 Cr |
| PAT | ₹26.7 Cr |
| EPS | ₹0.29 |
| Shareholder Funds | ₹481.2 Cr |
| Debt | ₹346.2 Cr |
The key point is that the current standalone earnings base is still relatively small compared with the valuation being assigned to the future platform.
8. Valuation
Current private-market quotes vary considerably.
Recent indicative sources show:
- Moneycontrol: approximately ₹795/share
- UnlistedGain: approximately ₹825/share
- Neoma Capital: approximately ₹842/share
These are indicative OTC/private-market quotes, not NSE/BSE prices.
Indicative valuation
At around ₹795–₹840/share, the implied equity value is approximately:
₹73,000–₹78,000 Cr
Moneycontrol’s current data shows a market capitalisation of approximately ₹73,120 Cr.
A July 2026 transaction involving Rising Sun Holdings, associated with the Adar Poonawalla family office, was reported at approximately ₹700 Cr for a 1% stake, implying a valuation of roughly ₹70,000 Cr.
This provides an additional private-market valuation reference.
Important valuation observation
At these valuations, the investment thesis is heavily dependent on future capacity, acquisitions, renewable assets and IPO potential, rather than simply FY25 reported earnings.
9. Institutional / Strategic Capital
Inox Clean has attracted significant capital from financial investors.
In July 2026, Rising Sun Holdings was reported to have invested approximately ₹700 Cr for a 1% stake.
In August 2026, the Motilal Oswal Group committed approximately ₹1,500 Cr through a structured private-credit transaction to support acquisitions and expansion of renewable generation and solar manufacturing.
This is important because the company’s expansion requires substantial capital before the new capacity becomes fully productive.
10. IPO Status
Inox Clean Energy has been preparing for a potential public listing.
In July 2025, the company filed a pre-filed Draft Red Herring Prospectus for a proposed main-board IPO with SEBI and the stock exchanges.
Media reports at the time indicated a proposed IPO of more than ₹6,000 Cr, with fresh capital expected to support solar manufacturing and renewable-power expansion.
However, the IPO process subsequently went through changes and should not be treated as having a confirmed listing date as of September 2026.
Therefore:
Current status: Unlisted
IPO: Proposed / under process
Confirmed listing date: Not available
Price band: Not announced
Exchange: Proposed NSE/BSE main board
Inox Clean Energy – Investor Relations
11. Latest Strategic Development – US Solar Manufacturing
The Boviet transaction is potentially one of the most important developments for the company.
Inox Clean gains access to:
3 GW module manufacturing capacity
and a further:
3 GW cell manufacturing facility
in the United States.
This could give the group exposure to the US domestic solar-manufacturing ecosystem in addition to India.
The company specifically highlighted the economic benefits available from the US government’s domestic-manufacturing push.
12. Growth Drivers
☀️ 1. India’s renewable-energy expansion
India continues to add large amounts of solar and wind capacity, creating demand for both renewable generation and domestic manufacturing.
🏭 2. Solar manufacturing localisation
India’s policy push toward domestic solar manufacturing creates an opportunity for companies with large domestic cell and module capacity.
⚡ 3. Integrated business model
Manufacturing + IPP can create internal demand for solar equipment while allowing the company to capture economics across multiple stages of the value chain.
🇺🇸 4. US manufacturing opportunity
The Boviet Solar transaction provides exposure to the US solar-manufacturing market and its domestic-manufacturing incentives.
🔋 5. Hybrid + BESS
The company’s strategy includes hybrid renewable projects and energy storage, potentially allowing higher utilisation and more reliable renewable power delivery.
💰 6. Strong institutional backing
Recent capital commitments from investors provide funding support for the company’s expansion strategy.
🌍 7. International expansion
The company is targeting India, the US and Africa rather than remaining solely an Indian renewable platform.
13. Key Risks
1. Very high valuation
At approximately ₹73,000–₹78,000 Cr implied valuation, the company is being valued primarily on future growth, rather than current reported earnings.
2. Massive capital expenditure
The expansion into multi-GW manufacturing and IPP projects requires substantial capital.
CareEdge previously estimated approximately ₹6,500 Cr of capex for under-construction renewable and manufacturing capacities, with funding expected through project debt, cash accruals and equity.
3. Execution risk
The company is simultaneously expanding:
- Solar cells
- Solar modules
- Renewable generation
- Hybrid projects
- BESS
- US manufacturing
- International operations
Execution complexity therefore increases significantly.
4. Solar-module price volatility
Global solar manufacturing has experienced periods of significant oversupply and price pressure. Falling module/cell prices can negatively affect manufacturers.
5. Technology risk
Solar technology is evolving rapidly from PERC toward TOPCon and potentially newer technologies.
Continuous capex will be required to remain competitive.
6. IPO risk
The potential IPO could be delayed, restructured or launched at a valuation different from today’s private-market valuation.
7. Unlisted liquidity
Private-market shares can have:
- Low liquidity
- Wide bid/ask spreads
- Limited price discovery
- Long exit periods
The quoted ₹795–₹840 range should therefore not be interpreted as an exchange-traded market price.
14. Competitive Positioning
| Factor | Inox Clean Energy |
|---|---|
| Renewable Generation | ✅ |
| Solar Cell Manufacturing | ✅ |
| Solar Module Manufacturing | ✅ |
| Wind Exposure | ✅ |
| Hybrid Projects | ✅ |
| BESS | ✅ |
| C&I Renewable Power | ✅ |
| Captive Power | ✅ |
| US Manufacturing | ✅ |
| Africa Opportunity | ✅ |
| INOXGFL Ecosystem | ✅ |
| Potential IPO | ✅ |
The company’s distinctive feature is the combination of solar manufacturing and renewable power generation rather than focusing on only one part of the renewable-energy value chain.
15. Investment Snapshot
| Parameter | Inox Clean Energy |
|---|---|
| Sector | Renewable Energy |
| Group | INOXGFL |
| Status | Unlisted |
| Core Businesses | Solar Manufacturing + IPP |
| Earlier Operational RE Capacity | 157 MW |
| Earlier Under Construction | 400 MW |
| Earlier Pipeline | 2.2+ GW |
| Solar Manufacturing Expansion | Multi-GW |
| Boviet Module Capacity | 3 GW |
| Boviet Cell Capacity | 3 GW planned |
| FY25 Revenue | ₹81.9 Cr |
| FY25 PAT | ₹26.7 Cr |
| FY25 Debt | ₹346.2 Cr |
| Recent Private Valuation Reference | ~₹70,000 Cr |
| Current Indicative OTC Price | ~₹795–₹840 |
| Proposed IPO | Yes |
| IPO Size Reported | ₹6,000+ Cr |
| Long-Term Target | 11 GW manufacturing + 10 GW IPP |
| Key Theme | Integrated Renewable Energy |
16. UnlistedCart Takeaway
Inox Clean Energy is evolving from a relatively small renewable-energy platform into an integrated clean-energy business spanning solar manufacturing and renewable power generation.
The Boviet Solar acquisition, multi-GW manufacturing plans, renewable IPP pipeline, US expansion and potential IPO make it a company to watch within India’s unlisted renewable-energy space.
However, the current private-market valuation is already substantial compared with the company’s FY25 standalone earnings.
The key variables going forward will be:
Capacity commissioning → Utilisation → Renewable project additions → EBITDA growth → Capital requirements → IPO valuation
If the company successfully executes its stated FY2028 ambitions, the earnings profile could look very different from the current standalone financials. But that outcome depends on substantial execution and capital deployment, so the current valuation should be assessed against future capacity and cash-flow potential rather than FY25 PAT alone.
Official & Research Sources
Inox Clean Energy – Official Website
Inox Clean Energy – Investor Relations
INOXGFL Group – Official Website
Moneycontrol – Inox Clean Energy Unlisted Shares
Economic Times – Inox Clean Energy IPO
Inox Clean Energy – UnlistedGain Research
Disclaimer: This report is for informational and educational purposes only. Unlisted-share prices are indicative private-market references and may differ materially between buyers and sellers. Unlisted investments involve liquidity, valuation, regulatory, execution and listing risks. Investors should independently verify company filings and conduct their own due diligence before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
