
India’s Gas Trading Exchange | Energy Market Infrastructure | IPO-Bound
CIN: U74999DL2019PLC357145
ISIN: INE0BI301012
Face Value: ₹10
Incorporated: 6 November 2019
Trading Platform Launched: June 2020
PNGRB Authorisation: December 2020
Corporate Office: Noida, Uttar Pradesh
Status: Unlisted Public Company / IPO-bound
Promoter: Indian Energy Exchange Limited (IEX)
1. Company Overview
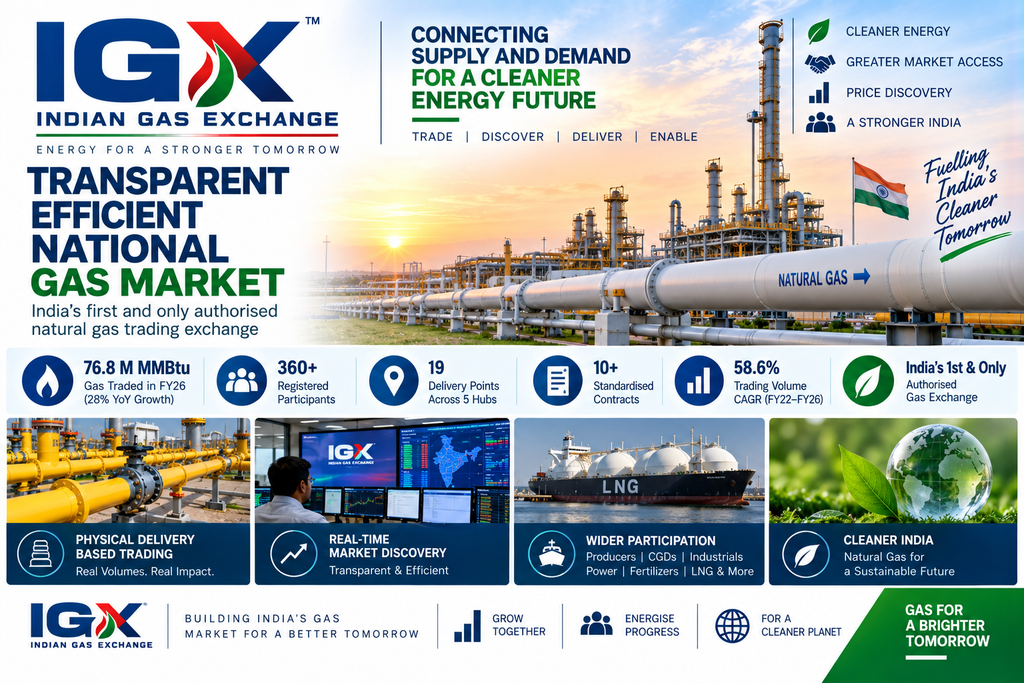
Indian Gas Exchange Limited (IGX) is India’s first and only authorised national-level physical delivery-based gas trading exchange.
It provides an electronic marketplace where buyers and sellers trade natural gas through standardised contracts, with actual physical delivery taking place through designated delivery points connected to India’s gas pipeline network. IGX operates under the regulatory framework of the Petroleum and Natural Gas Regulatory Board (PNGRB).
Unlike a conventional gas distributor or producer, IGX does not primarily make money by owning gas assets. Its business is closer to an exchange/platform model, where revenue is linked largely to trading activity, transaction fees, memberships and related services.
Official IGX Website
IGX – Company Overview
2. How IGX Makes Money
The company’s platform connects different participants in the natural-gas ecosystem.
Major participants
- Gas producers
- Gas marketing companies
- City gas distribution companies
- Power generators
- Fertiliser companies
- Refineries
- LNG terminal operators
- Industrial consumers
- Energy traders
IGX offers both spot and forward contracts, with delivery-based contracts extending to longer tenures.
Revenue model
The principal source of operating revenue is transaction fees charged on gas traded through the exchange.
For FY26, transaction fees were approximately ₹57.57 Cr, representing about 67.86% of total income.
This creates an important operating characteristic:
Higher trading volume → Higher transactions → Higher fee income → Higher profitability
Because IGX is an exchange rather than a capital-intensive gas producer, incremental trading volumes can potentially translate into significant operating leverage.
3. Products & Contracts
IGX currently provides multiple natural-gas trading products.
Spot / short-duration contracts
- Intraday
- Day Ahead
- Daily
- Weekday
- Weekly
- Fortnightly
- Monthly
- Balance of Month
Longer-duration contracts
- 3-month
- 6-month
- Benchmark-linked contracts
Small-scale LNG
IGX also provides small-scale LNG (ssLNG) contracts for physical delivery.
As of March 31, 2026, the exchange offered 10 standardised natural-gas contracts and four ssLNG contracts.
4. Geographic Reach
IGX’s trading ecosystem covers 19 delivery points across five regional gas hubs, connected to India’s national pipeline network.
This allows participants to trade gas based on different delivery locations and market conditions.
The exchange also facilitates delivery through designated hubs where pipeline capacity and settlement arrangements are integrated into the trading process.
5. Trading Volume Growth
One of the most important indicators for IGX is gas traded through the exchange.
FY26
IGX traded a record:
76.8 million MMBtu
equivalent to approximately 1,935 MMSCM.
This represented:
28% YoY growth
The exchange executed 1,924 trades during FY26.
More importantly, IGX’s traded volumes recorded a 58.6% CAGR between FY22 and FY26.
Volume trend
| Financial Year | Trading Volume |
|---|---|
| FY22 | Base period |
| FY24 | 40.84 million MMBtu |
| FY26 | 76.8 million MMBtu |
IGX therefore more than doubled traded volume between FY24 and FY26.
6. FY26 Contract Mix
Monthly contracts were the largest contributor to FY26 traded volumes.
| Contract | Approx. Share |
|---|---|
| Monthly | 64% |
| Fortnightly | 14% |
| Day Ahead | 6% |
| Weekly | 5% |
| Daily | 5% |
| Intraday | 3% |
| Balance of Month | 1% |
| 3M & 6M | 1% |
The Gadimoga delivery point accounted for approximately 41% of FY26 traded volume, followed by Dahej at 22%.
7. GIXI – Gas Index of India
One of IGX’s strategically important products is GIXI® — Gas Index of India.
GIXI is a benchmark price index based on exchange transactions and provides a market-based reference for Indian natural-gas prices.
The development of a domestic gas benchmark can become increasingly important as India’s gas market becomes more transparent and market-driven.
For March 2026, IGX reported GIXI at approximately ₹998/MMBtu, or about $10.8/MMBtu.
8. FY26 Financial Performance
IGX has been showing strong growth in profitability.
₹ Crore
| Particulars | FY24 | FY25 | FY26 |
|---|---|---|---|
| Total Income | 54.62 | 69.08 | 84.84 |
| Revenue from Operations | ~48.8 | ~48.8* | 61.01 |
| EBITDA | 33.92 | 46.09 | 58.61 |
| PAT | 23.05 | 30.79 | 42.02 |
| Net Worth | 116.66 | 147.71 | 179.03 |
Reported figures can differ depending on whether total income or revenue from operations is being presented.
FY26 total income increased by roughly 23%, while PAT increased approximately 36% YoY.
The business therefore continues to demonstrate the characteristics of an asset-light exchange model, where rising volumes can support earnings growth without a proportionate increase in physical infrastructure.
9. Participant Base
As of March 31, 2026, IGX had approximately:
360 registered participants
compared with 343 a year earlier.
The participant base covers a broad section of the Indian natural-gas ecosystem.
The expansion of participants is important because greater participation can improve:
- Liquidity
- Price discovery
- Trading volumes
- Contract diversity
- Network effects
10. Shareholding Pattern
IGX was originally established as a wholly owned subsidiary of Indian Energy Exchange Limited (IEX).
Due to regulatory restrictions around ownership of gas exchanges, IEX has been required to reduce its stake.
Pre-IPO shareholding
| Shareholder | Approx. Holding |
|---|---|
| Indian Energy Exchange Ltd (IEX) | 47.28% |
| NSE Investments Ltd | 24.75% |
| ONGC | Part of public shareholding |
| GAIL (India) | Part of public shareholding |
| Indian Oil Corporation | Part of public shareholding |
| Adani Total Gas | Part of public shareholding |
| Torrent Gas | Part of public shareholding |
| IGX ISOS Trust | Part of public shareholding |
IEX remains the largest shareholder, while NSE Investments is another major shareholder.
11. Parent Company – Indian Energy Exchange
The association with Indian Energy Exchange (IEX) is strategically important.
IEX already operates India’s largest electricity trading exchange, giving IGX access to:
- Exchange technology expertise
- Energy-market experience
- Institutional relationships
- Trading infrastructure knowledge
- Regulatory experience
The gas exchange can therefore be viewed as an extension of India’s organised energy-market infrastructure.
12. Natural Gas Opportunity in India
India’s government has set a policy objective of increasing the share of natural gas in the country’s energy mix to approximately 15% by 2030.
IGX’s own corporate material identifies this transition toward a larger gas economy as one of the structural drivers behind organised gas trading.
Potential growth areas include:
City Gas Distribution
Expansion of PNG and CNG networks could increase gas consumption.
Fertiliser
Gas remains an important feedstock for fertiliser production.
Power
Gas-fired generation can provide flexibility to the electricity system.
Industrial consumers
Industries can increasingly use exchange-based procurement to supplement long-term contracts.
LNG
Greater LNG availability can expand the addressable market for exchange-based trading.
13. Important Regulatory Opportunity
A significant factor for IGX is how much domestic natural gas becomes available for market-based trading.
A large portion of India’s domestic gas supply remains governed by allocation mechanisms and administered pricing.
Greater liberalisation of domestic gas trading could potentially increase the amount of gas available through exchanges.
This is one of the major long-term variables for IGX’s trading-volume growth.
14. IPO Status
This is currently one of the most important developments for IGX.
DRHP filed with SEBI
IGX filed its Draft Red Herring Prospectus (DRHP) with SEBI in July 2026. SEBI’s public-issue filing page records the IGX DRHP filing.
Proposed issue structure
The IPO is proposed to be:
100% Offer for Sale (OFS)
for up to:
1.671 crore equity shares
The selling shareholder is:
Indian Energy Exchange Limited
There is no fresh issue of shares.
Therefore:
IGX itself will not receive IPO proceeds.
The money raised will go to the selling shareholder, IEX.
Why is IEX selling?
IEX currently owns approximately 47.28% of IGX.
The proposed sale would reduce IEX’s stake to approximately 25%, aligning with the regulatory ownership limit applicable to a shareholder that is not itself a member of the gas exchange.
IPO status as of September 2026
| Particular | Status |
|---|---|
| DRHP | Filed |
| Fresh Issue | Nil |
| OFS | Up to 1.671 Cr shares |
| Selling Shareholder | IEX |
| Price Band | Not announced |
| IPO Dates | Not announced |
| Final Issue Size | Not announced |
| Listing | Proposed |
| Expected Exchange | BSE mentioned in reporting/DRHP |
The listing timetable and valuation will depend on subsequent regulatory approvals and offer documents.
SEBI – Indian Gas Exchange DRHP
15. Current Unlisted Share Price
Indian Gas Exchange remains unlisted as of September 2026.
Moneycontrol’s latest available unlisted-market data shows an indicative price around:
₹425/share
with a reported 52-week range of approximately ₹396.57–₹428.20.
Moneycontrol explicitly states that its unlisted-share prices are indicative rates derived from partners and are not intended as exchange-traded prices.
Other unlisted-market platforms are currently quoting around the same broad range, roughly ₹425–₹440/share.
Indicative market capitalisation
Using:
₹425 × 7.5 Cr shares
gives an implied equity value of approximately:
₹3,190 Cr
Moneycontrol similarly reports approximately ₹3,191 Cr market capitalisation at ₹425.23/share.
16. Valuation
At approximately ₹425/share:
- Implied market cap: ~₹3,190 Cr
- FY26 PAT: ~₹42 Cr
- Approximate P/E: ~76x FY26 earnings
The P/E calculation uses FY26 PAT and approximately 7.5 crore shares.
This is a high earnings multiple, meaning the private-market valuation already reflects significant expectations for future trading-volume growth, gas-market development and the eventual listing.
The DRHP-reported FY26 diluted EPS is approximately ₹5.66.
17. Key Growth Drivers
1. Rising gas consumption
India’s push toward a larger role for natural gas provides a structural opportunity for organised gas trading.
2. Market liberalisation
Greater availability of market-priced gas could increase exchange volumes.
3. Increasing participants
A growing participant base can improve liquidity and price discovery.
4. More LNG availability
Additional LNG supply can increase the amount of gas available for market-based trading.
5. New contracts
Long-duration contracts and ssLNG products can broaden IGX’s addressable market.
6. GIXI benchmark
A widely used Indian gas benchmark could strengthen IGX’s position within the gas ecosystem.
7. Operating leverage
Exchange businesses can scale transaction volumes without requiring proportional physical infrastructure investment.
18. Key Risks
1. Regulatory risk
Gas trading in India remains heavily influenced by PNGRB and government policies.
Changes in gas allocation, pricing or exchange regulations could directly affect IGX.
2. Domestic gas restrictions
A substantial portion of domestic gas remains subject to allocation and price controls. Greater restrictions can reduce freely tradable volumes.
3. Participant concentration
The top 10 participants accounted for approximately 66.47% of revenue from operations in FY26, creating customer/participant concentration risk.
4. Trading-volume risk
IGX earns primarily from transactions.
If trading volumes decline, revenue can decline accordingly.
5. Pipeline infrastructure
Physical delivery depends on India’s gas-pipeline infrastructure and access to delivery points.
6. Competition from bilateral markets
A significant amount of gas continues to be traded through bilateral contracts and other mechanisms.
7. Technology / cybersecurity
An exchange is heavily dependent on reliable IT infrastructure. System outages or cyber incidents could disrupt trading.
8. High valuation
At approximately ₹425/share and ~76x FY26 earnings, substantial future growth appears to be embedded in the private-market valuation.
9. IPO pricing risk
The eventual IPO price could be materially different from the current unlisted-market price.
19. Current IGX Gas Market Snapshot
The exchange’s market data showed the following indicative September 2026 prices as of 17 September 2026:
| Contract / Hub | Approx. Price |
|---|---|
| Sep-26 East | ₹2,550/MMBtu |
| Sep-26 Central | ₹2,400/MMBtu |
| Sep-26 West | ₹2,800/MMBtu |
| Sep-26 GIXI | ₹2,800/MMBtu |
| Oct-26 Central | ₹2,870/MMBtu |
| Oct-26 East | ₹2,520/MMBtu |
These are gas-market prices, not IGX share prices.
20. Investment Snapshot
| Parameter | Indian Gas Exchange |
|---|---|
| Industry | Energy Exchange |
| Core Business | Natural Gas Trading |
| Incorporated | 2019 |
| Operations Started | 2020 |
| Regulator | PNGRB |
| Promoter | IEX |
| FY26 Trading Volume | 76.8m MMBtu |
| FY26 Volume Growth | 28% |
| FY22–FY26 Volume CAGR | 58.6% |
| FY26 Total Income | ₹84.84 Cr |
| FY26 PAT | ₹42.02 Cr |
| FY26 Net Worth | ₹179.03 Cr |
| Participants | 360 |
| Delivery Points | 19 |
| Indicative Unlisted Price | ~₹425 |
| Implied Market Cap | ~₹3,190 Cr |
| Approx. FY26 P/E | ~76x |
| IPO | DRHP Filed |
| IPO Type | 100% OFS |
| OFS Shares | Up to 1.671 Cr |
| Selling Shareholder | IEX |
| Fresh Capital to IGX | Nil |
21. UnlistedCart Takeaway
Indian Gas Exchange is essentially an energy-market infrastructure play rather than a conventional gas company.
The core story is:
India’s gas consumption ↑
→ organised gas trading ↑
→ IGX trading volumes ↑
→ transaction revenue ↑
→ operating leverage ↑
FY26 provides evidence of strong volume and earnings growth, with 76.8 million MMBtu traded and ₹42 Cr PAT.
The proposed IPO is another major catalyst because it could transition IGX from an unlisted energy-market infrastructure company into a publicly traded exchange.
However, the current unlisted valuation around ₹3,200 Cr already represents a substantial multiple of current earnings.
Therefore, the key variables to monitor are:
Gas-market liberalisation → Trading volumes → Participant growth → Revenue per unit traded → Margin → IPO valuation
The company has a relatively asset-light business model, but its growth ultimately depends on the development of India’s organised natural-gas market and the regulatory environment governing gas trading.
Important Sources
Official Indian Gas Exchange Website
IGX Official Press Releases & Gas Market Updates
Moneycontrol – IGX Unlisted Share Information
Disclaimer: This report is for informational and educational purposes only and is not investment advice. Unlisted-share prices are indicative private-market references and may differ between buyers and sellers. Unlisted investments involve liquidity, valuation, regulatory, market, technology and execution risks. Investors should independently verify the latest DRHP, company filings and regulatory disclosures before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
