
Sector: Automotive Components & Mobility Technology
Industry: Powertrain Solutions, EV Components, Gears & Transmissions
Status: Unlisted / IPO Open
CIN: U29299PB1998PLC039602
ISIN: INE012G01022
Face Value: ₹10 per share
Incorporated: 30 April 1998
Registered Office: Hero Nagar, G.T. Road, Ludhiana, Punjab
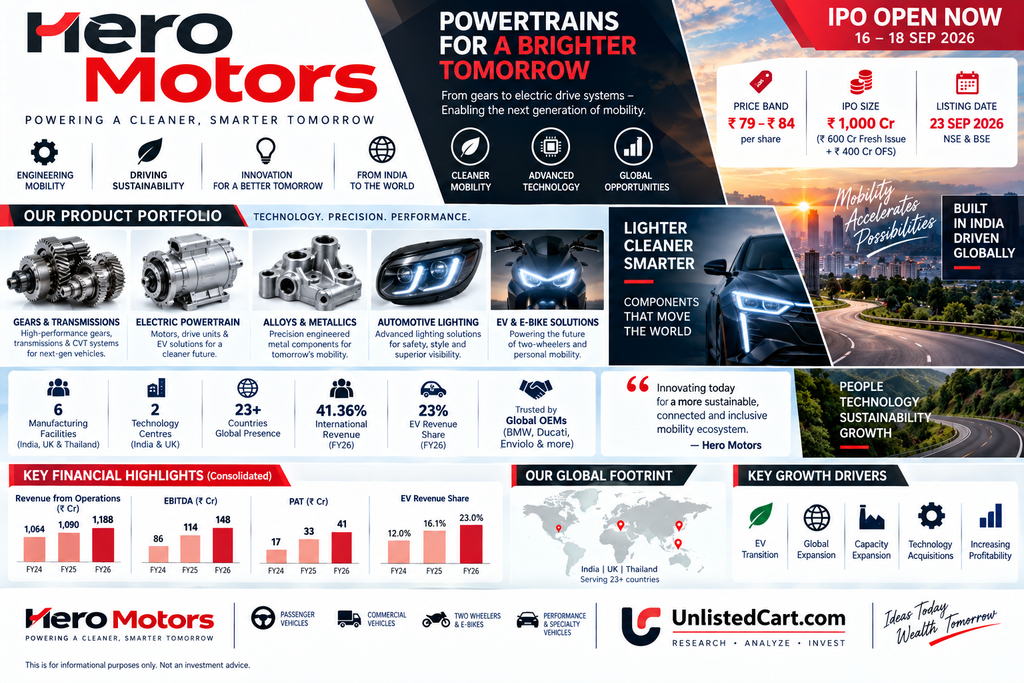
IPO Price Band: ₹79–₹84 per share
IPO Size: ₹1,000 Cr
IPO Opening: 16 September 2026
IPO Closing: 18 September 2026
Proposed Listing: NSE & BSE
Lot Size: 178 shares
Maximum IPO Price: ₹84
1. Executive Summary
Hero Motors Limited is an automotive technology and components company belonging to the HMC Group and led by the Munjal family.
The company develops and manufactures powertrain systems, gears, transmissions, electric motors, integrated electric drive units, CVT systems, alloy components and metallic assemblies for both electric and conventional vehicles.
Its business is broader than a conventional auto-component manufacturer. Hero Motors supplies products across:
- Two-wheelers
- E-bikes
- Electric vehicles
- Hybrid vehicles
- Performance automobiles
- Commercial vehicles
- Off-road vehicles
- Motorsport
- Specialty mobility
- eVTOL applications
The company operates across India, the UK and Thailand, with six manufacturing facilities and two technology centres. International customers contributed approximately 41.36% of FY26 revenue, while EV-related revenue increased to 23% of FY26 revenue from 12.03% in FY24.
Hero Motors has now moved from the unlisted market into the IPO stage.
The company is raising ₹1,000 Cr, consisting of:
₹600 Cr fresh issue + ₹400 Cr offer for sale.
The fresh issue proceeds are primarily intended for debt repayment, capacity expansion and strategic/inorganic growth.
2. Current IPO Status
The most important update is that Hero Motors’ IPO is currently open.
IPO structure
| Particular | Details |
|---|---|
| IPO Size | ₹1,000 Cr |
| Fresh Issue | ₹600 Cr |
| Offer for Sale | ₹400 Cr |
| Price Band | ₹79–₹84 |
| Face Value | ₹10 |
| Lot Size | 178 shares |
| Minimum Investment | ₹14,952 at ₹84 |
| Opening Date | 16 Sep 2026 |
| Closing Date | 18 Sep 2026 |
| Proposed Listing | 23 Sep 2026 |
| Exchanges | NSE & BSE |
| Registrar | KFin Technologies |
The company’s official IPO page contains the DRHP, RHP and related offer documents.
Hero Motors Official IPO / Offer Documents
As of September 16, the issue was reported as fully subscribed on its first day of bidding. This is a subscription-status observation, not an assessment of investment quality.
3. Company Overview
Hero Motors was incorporated in 1998 and has evolved into an integrated automotive technology company.
Its core proposition is not simply manufacturing individual components; the company provides integrated solutions covering:
Design → Engineering → Prototyping → Validation → Manufacturing
This allows it to participate earlier in the product-development cycle with global OEM customers.
The company operates through three broad business areas:
1. Gears & Transmissions
Products include:
- Transmission systems
- Gears
- CVT systems
- Transmission components
- High-performance gear systems
- EV transmission solutions
2. Bike Powertrain
Focused entirely on electric mobility.
Products include:
- Electric motors
- Electric drive units
- CVT systems
- Integrated electric powertrain systems
3. Alloys & Metallics
Products include:
- Sheet-metal components
- Tubular components
- Machined components
- Alloy components
- Welded assemblies
- Painted components
The company’s FY25 annual report describes these businesses and its global manufacturing footprint.
4. Business Segmentation – FY26
FY26 revenue mix was approximately:
| Business | FY26 Revenue | Share |
|---|---|---|
| Gears & Transmissions | ₹488.7 Cr | ~41.1% |
| Bike Powertrain | ₹148.9 Cr | ~12.5% |
| Alloys & Metallics | ₹550.6 Cr | ~46.3% |
| Total | ₹1,188.4 Cr | 100% |
The Powertrain Solutions business therefore contributed slightly more than half of consolidated revenue when Gears & Transmissions and Bike Powertrain are combined.
5. Powertrain Solutions
Powertrain Solutions is strategically important because it moves Hero Motors towards higher-value engineered products.
The company supplies transmission and powertrain solutions for:
- Motorcycles
- E-bikes
- Passenger vehicles
- Commercial vehicles
- Off-road vehicles
- Performance vehicles
- EVs
- Hybrid vehicles
The company also has capabilities in high-performance and motorsport applications through its UK operations.
This provides exposure to both traditional internal-combustion vehicles and emerging electric mobility.
6. Electric Mobility
One of the strongest structural changes in Hero Motors’ business has been the growth of EV-related revenue.
EV-related revenue
| Fiscal Year | EV Revenue Share |
|---|---|
| FY24 | 12.03% |
| FY25 | 16.12% |
| FY26 | 23.00% |
This means the proportion of revenue associated with global e-mobility has nearly doubled in two years.
However, Hero Motors should not be viewed as a pure EV company.
Approximately 77% of FY26 revenue was still derived from non-EV applications.
That diversification allows the company to participate in both existing ICE/hybrid markets and the emerging EV market.
7. E-Bike Opportunity
The company has developed a specialised position in electric-bike powertrain technology.
Hero Motors manufactures and exports CVT hubs for global e-bike OEMs and has developed integrated electric powertrain products.
Its e-bike business includes technology partnerships and products supplied to global mobility companies.
The company reports that its CVT systems powered more than 0.40 million e-bikes globally during FY24–FY26.
The e-bike opportunity is significant because Hero Motors can potentially participate in:
Motor + transmission + integrated drive unit
rather than supplying only a single mechanical component.
8. Global Customers
Hero Motors has established relationships with global automotive and mobility companies.
Customers/programmes include names such as:
- BMW
- Ducati
- Enviolo
- Hero MotoCorp
- River
- Other global e-bike and mobility manufacturers
The company has developed long-term relationships with several customers, but customer concentration remains a major issue.
9. Customer Concentration
This is one of the most important risks disclosed in the IPO documents.
FY26 customer concentration
| Customer Group | Revenue Contribution |
|---|---|
| Largest customer | 35.57% |
| Top 5 customers | 61.42% |
| Top 10 customers | 72.89% |
The largest customer contributed approximately ₹422.74 Cr of FY26 revenue.
The concentration has improved:
Top 10 customers
FY24: 76.96%
FY25: 78.03%
FY26: 72.89%
So diversification is moving in the right direction, but the company remains significantly dependent on a relatively small number of customers.
This is particularly important for an automotive supplier because the loss or reduction of a major vehicle programme can materially affect capacity utilisation and revenue.
10. International Business
Hero Motors has developed a significant international revenue base.
FY26 international revenue
Approximately:
₹491.53 Cr
or:
41.36% of revenue from operations
The company supplied customers across approximately 23 countries during FY26.
Geographic revenue mix
| Geography | Approx. FY26 Share |
|---|---|
| India | 58.64% |
| Europe | 33.59% |
| United States | 3.86% |
| Other markets | 3.91% |
This gives the company geographical diversification but also creates:
- Currency risk
- European automotive-cycle exposure
- Global demand risk
- Export logistics risk
- Regulatory exposure
11. Manufacturing Footprint
Hero Motors currently operates six manufacturing facilities across:
India + UK + Thailand
It also has two technology centres:
- Gautam Buddha Nagar, India
- Southam, UK
The company is also developing additional facilities in:
- Ludhiana
- Bengaluru
Its current manufacturing footprint allows it to serve both Indian and international OEM customers.
12. Technology & R&D
Engineering capability is an important part of Hero Motors’ business model.
FY26 R&D expenditure was approximately:
₹89.59 Cr
equivalent to around:
7.54% of revenue
This is significant for an auto-component company because new product development, validation and customer-specific engineering are important for securing future vehicle programmes.
The company therefore competes not only on manufacturing cost but also on:
- Engineering
- Product development
- Design
- Validation
- Intellectual property
- Manufacturing quality
- Customer integration
13. Acquisition Strategy
Hero Motors has used acquisitions and strategic partnerships to expand its technology capabilities.
Hewland Engineering
Hero Motors acquired a majority stake in UK-based Hewland Engineering, a company associated with high-performance transmission technology.
Hewland provides exposure to:
- Motorsport
- High-performance vehicles
- Advanced transmission systems
- Engineering technology
Spur Technologies
The company acquired Spur Technologies during FY24.
Spur is involved in components for premium motorcycles and electric bikes.
The company has indicated that it is also exploring further technology acquisitions and strategic alliances, particularly in North America and Europe.
14. FY26 Financial Performance
Consolidated financials
| Particulars | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue from Operations | ₹1,064.39 Cr | ₹1,089.59 Cr | ₹1,188.35 Cr |
| EBITDA | ₹86.28 Cr | ₹114.00 Cr | ₹147.78 Cr |
| EBITDA Margin | 8.11% | 10.46% | 12.44% |
| PAT | ₹17.04 Cr | ₹32.80 Cr | ₹41.17 Cr |
| PAT Margin | 1.60% | 3.01% | 3.46% |
| Net Worth | ₹374.82 Cr | ₹426.01 Cr | ₹481.01 Cr |
| Borrowings | ₹303.998 Cr | ₹407.62 Cr | ₹400.79 Cr |
The FY24–FY26 figures are based on the restated financial information presented in IPO-related research based on the offer documents.
15. Revenue Growth
FY26 revenue grew approximately:
9.06% YoY
from ₹1,089.59 Cr to ₹1,188.35 Cr.
The more notable development was profitability.
EBITDA
FY24: ₹86.28 Cr
FY25: ₹114.00 Cr
FY26: ₹147.78 Cr
FY26 EBITDA growth was approximately:
29.6%
versus revenue growth of approximately 9.1%.
This resulted in EBITDA margin increasing from:
8.11% → 10.46% → 12.44%
over FY24–FY26.
16. Adjusted EBITDA
The company also reports adjusted EBITDA after certain adjustments.
| Fiscal | Adjusted EBITDA | Margin |
|---|---|---|
| FY24 | ₹125.74 Cr | 11.81% |
| FY25 | ₹128.82 Cr | 11.82% |
| FY26 | ₹160.24 Cr | 13.48% |
The improvement in adjusted EBITDA margin suggests that the FY26 margin expansion was not solely due to accounting adjustments.
However, investors should still examine the reconciliation between reported and adjusted EBITDA in the RHP.
17. Profitability
PAT increased from:
₹17.04 Cr in FY24
to:
₹32.80 Cr in FY25
and:
₹41.17 Cr in FY26
FY26 PAT growth was approximately:
25.5%
while PAT margin increased to approximately:
3.46%.
Despite the improvement, the net margin remains relatively thin compared with several established listed auto-component companies.
18. Cash Flow
FY26 operating cash flow was approximately:
₹144.04 Cr
versus:
₹48.34 Cr in FY25
and:
₹131.97 Cr in FY24.
The recovery in FY26 operating cash flow is positive from a cash-generation perspective.
However, working capital needs monitoring.
Receivable days
FY24: 67 days
FY25: 68 days
FY26: 78 days
The increase in receivable days indicates that cash conversion from customers became slower during FY26.
Inventory days remained around:
64 days
while payable days declined from 46 to 43 days.
19. Capital Expenditure
Hero Motors has historically invested heavily in manufacturing capacity and technology.
FY26 capital expenditure was approximately:
₹92.25 Cr
compared with approximately ₹152.40 Cr in FY25.
The IPO now provides another significant source of growth capital.
20. IPO Objects – ₹600 Cr Fresh Issue
The company will receive proceeds only from the ₹600 Cr fresh issue.
The ₹400 Cr OFS proceeds will go to the selling shareholders.
Fresh issue utilisation
| Purpose | Amount |
|---|---|
| Debt repayment/prepayment | ₹190 Cr |
| Capacity expansion / equipment | ₹200 Cr |
| Inorganic growth & strategic initiatives | Balance |
| General corporate purposes | Balance |
The ₹200 Cr capex is primarily intended for capacity expansion at the Gautam Buddha Nagar, Uttar Pradesh facility.
21. Why Gautam Buddha Nagar Expansion Matters
The company’s Gautam Buddha Nagar powertrain facility was operating at relatively high utilisation.
Reported FY26 capacity utilisation included approximately:
88.25% for Powertrain
and around:
78.53% overall
This provides a clear operational reason for additional capacity.
At the same time, some newer international facilities have lower utilisation, meaning future returns will depend on the ramp-up of these investments.
22. Debt Position
FY26 borrowings were approximately:
₹400.79 Cr
Debt/equity:
~0.83×
Net debt/adjusted EBITDA:
~2.24×
This represents an improvement from approximately 2.79× in FY25 but remains higher than FY24’s 1.72×.
IPO impact
The proposed ₹190 Cr debt repayment should reduce leverage after the IPO.
The exact post-IPO debt position will depend on the company’s debt movements between March 2026 and the completion of the issue.
23. IPO Valuation
The IPO price band is:
₹79–₹84
At the upper band, the company is expected to have a market capitalisation of approximately:
₹3,815 Cr
before considering the post-issue capital structure and listing-market movements.
FY26 EPS
The restated FY26 diluted EPS is approximately:
₹1.14
before considering the full dilution impact of the fresh issue.
Using ₹84:
₹84 ÷ ₹1.14 ≈ 73.7×
This is the commonly cited pre-issue FY26 P/E calculation.
However, after the fresh issue, the share count increases, so post-issue EPS is lower.
IPO research sources estimate post-issue FY26 EPS around ₹0.96, implying a post-issue P/E of roughly:
82–88×
at the ₹79–₹84 price band.
24. Valuation Sensitivity
Using post-issue illustrative EPS of approximately ₹0.96:
| P/E | Implied Value |
|---|---|
| 40× | ₹38 |
| 50× | ₹48 |
| 60× | ₹58 |
| 70× | ₹67 |
| 80× | ₹77 |
| 85× | ₹82 |
| 90× | ₹86 |
| 100× | ₹96 |
This shows that the IPO valuation is heavily dependent on expectations of future earnings growth, rather than current earnings alone.
The company would need continued growth in:
- Powertrain revenue
- EV revenue
- EBITDA margin
- Capacity utilisation
- Global customer programmes
- New product wins
to support a substantially higher earnings base over time.
25. Peer Comparison
Based on FY26 figures:
| Company | Revenue | EBITDA Margin | PAT Margin | P/E* |
|---|---|---|---|---|
| Hero Motors | ₹1,188 Cr | 12.44% | 3.46% | ~73× |
| CIE Automotive India | ₹9,406 Cr | 15.59% | 8.75% | ~17.7× |
| Endurance Technologies | ₹14,596 Cr | 14.17% | 6.52% | ~40.8× |
| Sona BLW | ₹4,449 Cr | 25.91% | 14.14% | ~76.5× |
| UNO Minda | ₹19,658 Cr | 12.75% | 6.53% | ~59.8× |
| Varroc Engineering | ₹8,891 Cr | 9.08% | 2.59% | ~56.2× |
*Peer multiples use market prices around the period of IPO analysis; Hero Motors uses the upper IPO band.
The comparison illustrates that Hero Motors is being valued at a substantial earnings multiple despite its much smaller revenue and profit base.
26. Key Growth Drivers
1. EV penetration
EV-related revenue has increased from 12.03% to 23% of revenue in two years.
2. E-bike powertrains
Hero Motors has developed specialised capabilities in CVT hubs and integrated electric powertrains.
3. Premium two-wheelers
The company supplies components for premium motorcycle programmes, including international customers.
4. Global OEM relationships
Long-term programmes with global OEMs can provide revenue visibility once products enter serial production.
5. Powertrain mix
Powertrain Solutions is becoming a larger portion of overall revenue.
6. International expansion
More than 40% of revenue comes from international customers.
7. Technology acquisitions
Future acquisitions could expand the company’s product portfolio and geographic reach.
8. Capacity expansion
The ₹200 Cr IPO-funded Gautam Buddha Nagar expansion could support future powertrain growth.
27. Key Risks
Customer concentration
The largest customer contributed 35.57% and the top 10 contributed 72.89% of FY26 revenue.
Valuation
At the upper IPO band, the company is valued at a high multiple of current earnings.
Debt
Net debt/adjusted EBITDA was approximately 2.24× in FY26.
Loss-making subsidiaries
Six subsidiaries reported losses in FY26, including HYM Drive Systems, Hero EDU Systems, Hewland Engineering and Spur Technologies.
Capacity utilisation
Some newer facilities have relatively low utilisation, creating execution and return-on-capital risks.
Working capital
Receivable days increased to 78 days in FY26.
Automotive cyclicality
Demand is dependent on vehicle production, model launches and OEM programmes.
Acquisition risk
Further acquisitions can create integration, capital allocation and execution risks.
International exposure
Around 41% of revenue is international, creating currency and overseas-market exposure.
28. Promoter Holding
Before the IPO, promoter/promoter-group ownership was approximately 85% according to IPO-related disclosures.
After the IPO, promoter ownership is expected to decline to approximately 61%–62%, depending on the final share structure and offer calculations.
This provides a meaningful increase in public shareholding and improves the potential free-float structure after listing.
29. IPO Structure
The ₹1,000 Cr issue consists of:
Fresh Issue – ₹600 Cr
Money comes into Hero Motors.
Used for:
- Debt reduction
- Capacity expansion
- Strategic/inorganic growth
OFS – ₹400 Cr
Money goes to selling shareholders.
The OFS is primarily being undertaken by promoter entities, including O P Munjal Holdings and Hero Cycles.
Therefore, investors should distinguish between:
₹600 Cr = company receives capital
and
₹400 Cr = existing shareholders monetise part of their holding.
30. Important Distinction – Hero Motors vs Hero MotoCorp
Hero Motors should not be confused with Hero MotoCorp Limited.
Hero Motors is an automotive components and powertrain technology company.
Hero MotoCorp is a two-wheeler manufacturer.
Hero Motors supplies components/powertrain solutions to various OEMs, while Hero MotoCorp manufactures motorcycles and scooters.
This distinction is important when evaluating the company.
31. What to Monitor After Listing
For investors following Hero Motors after the IPO, the following metrics will be particularly important:
Financial
- Revenue growth
- EBITDA margin
- PAT margin
- ROCE
- ROE
- Operating cash flow
Operational
- Powertrain capacity utilisation
- E-bike volumes
- EV revenue contribution
- New customer programmes
- International revenue
Balance sheet
- Debt reduction
- Net debt/EBITDA
- Working capital
- Receivable days
Customer diversification
- Largest customer share
- Top 5 customer share
- Top 10 customer share
New investments
- Gautam Buddha Nagar expansion
- Bengaluru facility
- Ludhiana facility
- HYM capacity ramp-up
- Thailand/UK utilisation
32. Research Perspective
Hero Motors has transitioned from a traditional automotive-component business towards a more technology-oriented powertrain platform.
The most notable change is the increasing contribution of electrification.
EV-related revenue:
12.03% → 16.12% → 23.00%
from FY24 to FY26.
At the same time, the company is not dependent entirely on EV adoption. Its Gears & Transmissions and Alloys & Metallics businesses continue to serve ICE, hybrid and conventional applications.
This creates a technology-agnostic powertrain model, allowing the company to participate across multiple vehicle technologies.
The financial trend is also improving:
Revenue: ₹1,064 Cr → ₹1,090 Cr → ₹1,188 Cr
EBITDA: ₹86 Cr → ₹114 Cr → ₹148 Cr
PAT: ₹17 Cr → ₹33 Cr → ₹41 Cr
The improvement in EBITDA margin from 8.11% to 12.44% is particularly notable.
However, the valuation is the central issue.
At ₹84, the IPO implies a very high multiple of current earnings. Consequently, the investment case depends substantially on future growth in EV/powertrain revenue, customer diversification, capacity utilisation and margin expansion.
33. Overall Assessment
Hero Motors represents an interesting combination of:
Automotive engineering + global OEM relationships + EV powertrain + e-bike technology + transmission systems + international manufacturing.
The company has several identifiable growth avenues:
- EV powertrain
- E-bike systems
- Premium motorcycles
- Global OEM programmes
- High-performance transmissions
- New manufacturing capacity
- Technology acquisitions
- International expansion
Its financial performance has also improved materially, particularly at the EBITDA level.
However, investors should balance these opportunities against:
- High customer concentration
- Moderate leverage
- Loss-making subsidiaries
- Working-capital intensity
- Capacity-utilisation differences
- Automotive cyclicality
- High IPO valuation
The IPO therefore needs to be evaluated using future earnings potential rather than current EPS alone.
The IPO is currently open from 16–18 September 2026, with a price band of ₹79–₹84 and a minimum application size of 178 shares / ₹14,952 at the upper band.
The proposed listing date is 23 September 2026, subject to the applicable IPO timetable.
34. Key Numbers at a Glance
| Parameter | Hero Motors |
|---|---|
| FY26 Revenue | ₹1,188.35 Cr |
| FY26 EBITDA | ₹147.78 Cr |
| FY26 EBITDA Margin | 12.44% |
| FY26 PAT | ₹41.17 Cr |
| FY26 PAT Margin | 3.46% |
| FY26 Adjusted EBITDA | ₹160.24 Cr |
| FY26 Adjusted EBITDA Margin | 13.48% |
| FY26 Operating Cash Flow | ₹144.04 Cr |
| FY26 Borrowings | ₹400.79 Cr |
| Net Debt / Adjusted EBITDA | 2.24× |
| EV Revenue Share | 23% |
| International Revenue | 41.36% |
| Top Customer Revenue | 35.57% |
| Top 10 Customers | 72.89% |
| IPO Size | ₹1,000 Cr |
| Fresh Issue | ₹600 Cr |
| OFS | ₹400 Cr |
| IPO Band | ₹79–₹84 |
| Lot Size | 178 |
| Minimum Investment | ₹14,952 |
| Proposed Listing | NSE & BSE |
| Proposed Listing Date | 23 Sep 2026 |
35. Important Links
Official Hero Motors Website:
Hero Motors Limited
Official IPO / Offer Documents:
Hero Motors IPO Documents
FY2024-25 Annual Report:
Hero Motors Annual Report FY2024-25
SEBI Filing:
SEBI – Hero Motors Public Issue Filings
Disclaimer
This report is prepared for research and informational purposes based on Hero Motors’ annual report, IPO offer documents, SEBI filings and publicly available market information.
The IPO is currently open, so the company is transitioning from the unlisted market to the listed market. IPO price-band calculations are based on the announced ₹79–₹84 range and should not be interpreted as a prediction of the eventual listing price.
Unlisted-market prices, where applicable, are indicative OTC references and are not exchange-traded prices.
Valuation scenarios and financial calculations are illustrative. Investors should read the final RHP/prospectus and risk factors carefully and independently assess the company’s financials, valuation and risk profile before making an investment decision.
For more such unlisted stocks visit Unlisted Shares on UnlistedCart
