
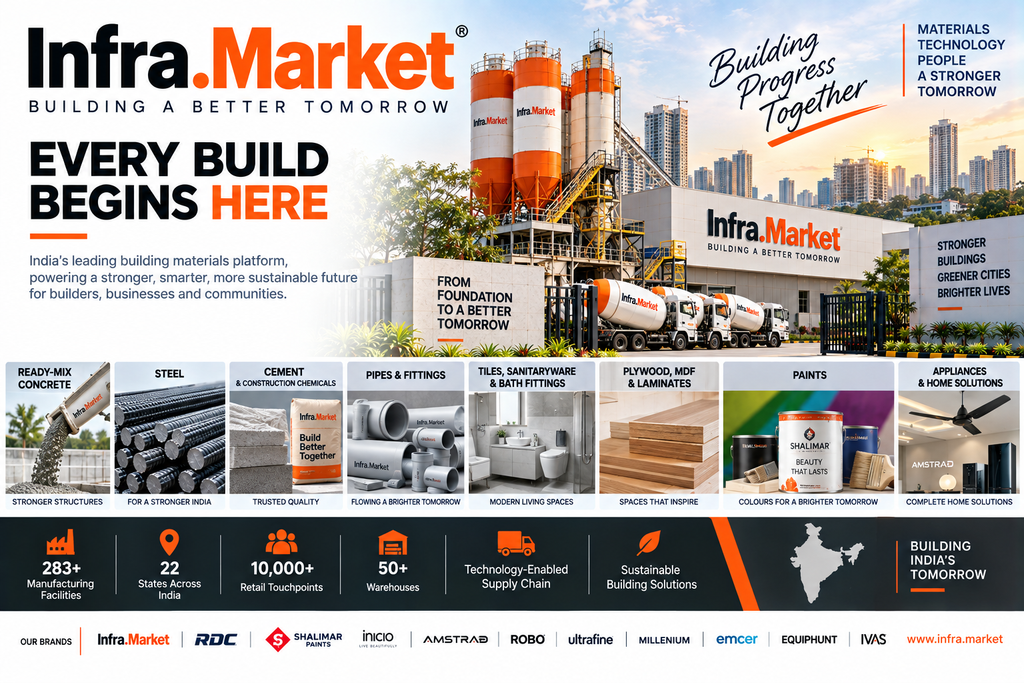
Infra.Market | Business, Financials, Valuation & Public-Market Route
Company: Hella Infra Market Limited
Brand: Infra.Market
Founded: 2016
CIN: U46632MH2016PLC283737
ISIN: INE06E501010
Registered Office: Thane, Maharashtra
Industry: Building Materials / Construction Technology
Status: Unlisted Public Company
Founders: Aaditya Sharda & Souvik Sengupta
Face Value: ₹10 per share
Website: Infra.Market Official Website
1. Company Overview
Hella Infra Market Limited operates the Infra.Market platform, a technology-enabled building-materials company serving contractors, developers, infrastructure companies, retailers and other construction-sector customers.
The company was founded in 2016 by Aaditya Sharda and Souvik Sengupta and is headquartered in Thane, Maharashtra.
Rather than being only an online marketplace, Infra.Market has built a combination of:
- Manufacturing
- Private-label brands
- Procurement
- Distribution
- Warehousing
- Logistics
- Technology
- B2B sales
- Retail/B2R distribution
This vertically integrated model is one of the most important features of the business.
The company’s official website says its platform has 283+ manufacturing facilities, comprising 163 owned and 120 exclusive third-party manufacturing facilities, across 22 states.
2. What Does Infra.Market Sell?
Infra.Market covers a very broad construction-material basket.
Structural Materials
- Ready-mix concrete
- Aggregates
- Steel
- AAC blocks
- Cement-related products
- Construction chemicals
Building Materials
- Pipes & fittings
- MDF
- Plywood
- Laminates
- Tiles
- Paints
Home & Interior Products
- Sanitaryware
- Bath fittings
- Electrical products
- Fans
- Lights
- Appliances
- Modular kitchens
- Wardrobes
- Designer hardware
The company describes this as a multi-product platform covering the entire construction project lifecycle, from foundation to finishing.
3. House of Brands
One of Infra.Market’s biggest strategic advantages is its house-of-brands strategy.
Its portfolio includes brands such as:
- Infra.Market
- RDC
- Shalimar Paints
- Inicio
- Amstrad
- Robo
- Ultrafine
- Millenium
- Emcer
- Equiphunt
- IVAS
The objective is to increase the share of branded/private-label products in its overall sales mix.
This can potentially provide better control over:
Product → Pricing → Manufacturing → Distribution → Customer relationship
rather than simply earning a marketplace/distribution margin.
4. Business Model
Infra.Market’s model can broadly be understood in four layers:
1. Manufacture
The company and its manufacturing partners produce construction materials.
2. Aggregate Demand
The platform uses technology and its large customer network to aggregate demand.
3. Distribution
Products are distributed through B2B and retail/B2R channels.
4. Private Labels
The company increasingly sells products under its own brands.
This creates an integrated model combining characteristics of a manufacturer + distributor + technology platform + branded building-material company.
5. Manufacturing & Distribution Network
According to the company’s official website, Infra.Market has:
283+ manufacturing facilities
including:
- 163 owned facilities
- 120 exclusive third-party facilities
across 22 states.
Its RMC network is particularly extensive. Infra.Market’s concrete business has described a network of 200+ concrete plants, alongside 30+ manufacturing units, 10,000+ retail touchpoints and 50+ warehouses.
The company’s retail platform also operates branded stores offering multiple construction and interior categories under one roof.
6. Technology Platform
Technology is an important part of Infra.Market’s business model.
The company says it uses internally developed technology to:
- Monitor construction projects
- Understand demand
- Optimise procurement
- Improve supply-chain efficiency
- Track sales
- Improve inventory management
- Cross-sell products
- Support customers and dealers
This technology layer differentiates Infra.Market from a conventional building-material wholesaler.
7. FY2025 Financial Performance
FY2025 was a year of strong revenue growth but considerably weaker bottom-line profitability.
Consolidated Financials
₹ Crore
| Particular | FY2024 | FY2025 |
|---|---|---|
| Revenue from Operations | 14,530 | 18,472 |
| Other Income | 213 | 84 |
| Total Income | 14,743 | 18,556 |
| EBITDA | ~1,029 | ~1,472 |
| PBT | ~448 | 306 |
| PAT | 378 | 220 |
| Net Worth | 2,914 | 5,774 |
| Borrowings | 1,778 | 2,668 |
| Total Assets | 5,564 | 9,209 |
Revenue from operations increased approximately 27%, while EBITDA increased significantly. However, PAT declined from approximately ₹378 Cr to ₹220 Cr because of higher finance costs, depreciation and other expenses.
8. Revenue Growth
Infra.Market has scaled very rapidly.
| FY | Sales |
|---|---|
| FY2021 | ₹1,062 Cr |
| FY2022 | ₹3,239 Cr |
| FY2023 | ₹4,416 Cr |
| FY2024 | ₹4,969 Cr |
| FY2025 | ₹6,053 Cr |
The consolidated revenue numbers reported by other databases are higher because of differences in presentation/consolidation; for example, FY2025 total revenue is reported at approximately ₹18,556 Cr, with revenue from operations around ₹18,472 Cr.
The large difference between the “sales” series and consolidated revenue presentation is a reminder that investors should use the audited consolidated financial statements for valuation rather than mixing database metrics.
9. Profitability
The most important issue in the FY2025 results is the divergence between EBITDA and PAT.
FY2025
Revenue: ~₹18,472 Cr
EBITDA: ~₹1,472 Cr
EBITDA Margin: ~8.0%
PAT: ~₹220 Cr
PAT Margin: ~1.2%
Finance costs increased to approximately ₹805 Cr, compared with about ₹554 Cr in FY2024. Depreciation also increased materially.
Therefore, EBITDA growth did not translate proportionately into net profit.
10. Why Did PAT Fall?
The company has been expanding rapidly through:
- Acquisitions
- Manufacturing
- Working capital
- New product categories
- Retail expansion
- Brand building
This has increased its capital requirements.
FY2025 finance cost was approximately ₹805 Cr, up sharply from FY2024.
Consequently:
Higher scale → higher EBITDA → but also higher finance cost + depreciation → lower PAT
This is one of the key factors investors should monitor.
11. Balance Sheet
FY2025 balance-sheet figures show significant expansion.
| Parameter | FY2024 | FY2025 |
|---|---|---|
| Net Worth | ₹2,914 Cr | ₹5,774 Cr |
| Borrowings | ₹1,778 Cr | ₹2,668 Cr |
| Assets | ₹5,564 Cr | ₹9,209 Cr |
| Debt/Equity | ~0.6x | ~0.5x |
Despite the increase in borrowings, the substantial increase in net worth improved the reported debt/equity ratio.
However, credit-rating analysis indicates that the broader group had significant external debt and refinancing requirements.
12. Latest Credit-Risk Update
An Acuité assessment published in September 2026 highlighted that the group’s tangible net worth was approximately ₹5,110 Cr as of March 2026 (provisional), compared with ₹3,709 Cr a year earlier.
The gearing improved to approximately 1.13x from 1.77x.
The group also used:
- Debt refinancing
- Equity infusion
- Additional proposed refinancing
- A proposed QIP
to strengthen its financial position.
The report noted that the group had refinanced approximately ₹750 Cr and raised about ₹915.55 Cr of equity in FY2026, with further refinancing and a proposed ₹1,000 Cr QIP forming part of the FY2027–FY2028 capital plan.
13. Major Investors
Infra.Market has attracted significant institutional backing.
Reported investors include:
- Tiger Global
- Accel
- Nexus Venture Partners
- Evolvence India
- Mars Unicorn Fund
- Capri Global
- Ascertis Credit
- Other institutional investors
The company has raised more than $740 million across reported funding rounds through September 2025, according to Inc42.
Tiger Global has participated across multiple rounds.
14. 2025 Funding & Valuation
In January 2025, Infra.Market raised approximately $121 million in a funding round led by Tiger Global and other investors.
The round reportedly valued the company at approximately $2.8 billion, or roughly ₹24,000 Cr at the then prevailing exchange rate. Reuters reported this valuation when covering the company’s confidential IPO filing.
A further Series G round in September 2025 raised approximately $83 million.
15. IPO Story – Important 2026 Update
This is one of the biggest changes in the investment story.
In September 2025, Infra.Market confidentially filed for an IPO. Reuters reported that the proposed IPO could involve a significant primary and secondary offering.
However, in August 2026, the company moved toward a different route.
Shalimar Paints Transaction
Shalimar Paints’ board approved a proposed transaction involving Hella Infra Market.
Under the proposed structure:
- Shalimar Paints would acquire/invest in Hella Infra Market through a share-swap structure.
- Hella Infra Market could become an unlisted material subsidiary of Shalimar Paints.
- Existing Hella Infra Market investors would receive securities of Shalimar Paints.
- Shalimar Paints also proposed raising up to ₹1,000 Cr through a QIP.
- The transaction remains subject to applicable shareholder and regulatory approvals.
Moneycontrol reported in August 2026 that Infra.Market had effectively moved away from the standalone IPO route and was pursuing public-market access through Shalimar Paints.
Why This Matters
For an existing unlisted-share investor, this transaction could potentially provide a corporate liquidity/public-market event, but the final value received by each Hella Infra Market shareholder depends on the approved transaction structure and valuation/share-swap ratio.
It should not be assumed that today’s unlisted share price will automatically convert into an equivalent Shalimar Paints value.
16. Proposed Share-Swap Structure
Shalimar Paints’ disclosures described a proposed issue of:
- Up to 41.70 crore equity shares
- Up to 81.12 crore CCPS
- Issue price of ₹85 per security
as part of the non-cash consideration structure related to Hella Infra Market.
The proposed transaction was stated to be based on valuation reports for both companies.
Therefore, the final exchange economics depend on the valuation and approved swap ratio, rather than simply multiplying the ₹85 issue price by Hella Infra Market’s shares.
17. Indicative Unlisted Share Price
The unlisted market currently shows very wide price differences, which itself demonstrates the limited price discovery in this security.
Recent dealer/platform indications include:
| Source | Indicative Price |
|---|---|
| WWIPL | ~₹85,000 |
| Unlisted Shares Wala | ~₹77,500 |
| Neo Capital | ~₹98,505 |
| SharesCart | ~₹99,500 |
These are dealer/platform indications, not NSE/BSE traded prices.
This difference is extremely important.
An investor should not assume that ₹77,500, ₹85,000 or ₹99,500 represents an immediately executable market price for a large quantity.
18. Indicative Valuation
Using one recent dealer indication of approximately ₹85,000/share, the quoted market capitalisation shown by that platform is approximately ₹7,950 Cr.
Another platform showing ₹99,500 reports a market cap of approximately ₹11,357 Cr.
The variation is largely because third-party platforms show different share counts/data snapshots.
Therefore, valuation should be based on the latest cap-table/share-count information and the approved Shalimar Paints transaction documents, rather than simply multiplying an indicative dealer quote by an outdated share count.
19. Valuation Reference from Institutional Transaction
The proposed Shalimar Paints transaction provides a more important reference point than dealer quotes.
Media reports estimated the proposed share-swap consideration at approximately ₹10,440 Cr, although the final swap ratio and valuation are subject to the transaction’s valuation process and approvals.
This is a transaction reference, not a guaranteed fair value or future market capitalisation.
20. Competitive Advantages
1. Scale
Infra.Market has grown from a startup into a multi-thousand-crore construction-material platform.
2. Multi-Product Model
Instead of focusing on one category, it participates across the construction lifecycle.
3. Manufacturing Integration
Owned and exclusive third-party manufacturing facilities provide greater supply control.
4. Private Labels
House brands potentially provide higher control over pricing and product differentiation.
5. Distribution Network
The company has built a significant B2B and retail distribution footprint.
6. Technology
Technology-driven procurement and supply-chain management is a central part of the model.
7. Institutional Backing
The company has attracted significant institutional capital from global and Indian investors.
21. Growth Drivers
India’s Construction Cycle
Infrastructure spending, housing construction, commercial real estate and urbanisation create a large addressable market.
Formalisation
Construction-material procurement remains fragmented. A technology-enabled organised platform can potentially gain share from smaller distributors.
Cross-Selling
A customer buying:
RMC → steel → pipes → tiles → sanitaryware → electricals → paints
can potentially purchase multiple products from the same platform.
Private-Label Expansion
Increasing the share of in-house brands can potentially improve gross margins and customer stickiness.
Retail Expansion
Infra.Market is developing a modern retail format offering multiple home-improvement categories.
22. Key Risks
1. Low Net Margins
FY2025 PAT margin was only around 1.2%, despite EBITDA of roughly ₹1,472 Cr.
2. Leverage
Rapid expansion has required significant external financing.
3. Working Capital
Construction materials are inherently working-capital intensive. Acuité has previously highlighted this as a structural characteristic of the business.
4. Commodity Price Volatility
Steel, cement, chemicals and other construction materials are exposed to commodity-price movements.
5. Real Estate Cycle
A slowdown in:
- Housing
- Infrastructure
- Commercial construction
- Real-estate development
could affect demand.
6. Execution Complexity
Managing hundreds of manufacturing facilities and a large product portfolio is operationally complex.
7. Public-Market Transaction Risk
The proposed Shalimar Paints transaction is subject to regulatory/shareholder approvals and final transaction terms.
8. Valuation Risk
At several thousand crore of implied valuation, future returns depend heavily on earnings growth and successful integration rather than revenue growth alone.
23. Public-Market Route: Old vs New
| Earlier Plan | Current 2026 Direction |
|---|---|
| Standalone Infra.Market IPO | Proposed Shalimar Paints route |
| Confidential IPO filing in 2025 | Proposed reverse/share-swap structure |
| Direct listing | Public-market access through Shalimar Paints |
| IPO price discovery | Swap based on valuation reports |
| Standalone listed company | Hella Infra Market potentially becomes material unlisted subsidiary |
| IPO timeline uncertain | Transaction subject to approvals |
Reuters confirmed the confidential IPO filing in 2025, while the August 2026 Shalimar Paints disclosures/reports indicate the newer route.
24. Company Snapshot
| Parameter | Hella Infra Market |
|---|---|
| Brand | Infra.Market |
| Founded | 2016 |
| Headquarters | Thane, Maharashtra |
| Industry | Building Materials |
| CIN | U46632MH2016PLC283737 |
| ISIN | INE06E501010 |
| Status | Unlisted Public Company |
| Founders | Aaditya Sharda, Souvik Sengupta |
| Manufacturing Facilities | 283+ |
| States | 22 |
| FY25 Revenue from Operations | ~₹18,472 Cr |
| FY25 EBITDA | ~₹1,472 Cr |
| FY25 PAT | ~₹220 Cr |
| FY25 Net Worth | ~₹5,774 Cr |
| FY25 Borrowings | ~₹2,668 Cr |
| 2025 Reported Valuation | ~$2.8 Bn |
| Indicative OTC Price | ~₹77,500–₹99,500* |
| IPO | Standalone route effectively superseded by proposed Shalimar transaction |
| Current Strategic Event | Proposed transaction with Shalimar Paints |
| Proposed QIP | Up to ₹1,000 Cr |
| Key Opportunity | Construction-material formalisation + scale |
| Key Risk | Low PAT margin + leverage + working capital |
*Indicative dealer/platform prices; not exchange-traded prices.
UnlistedCart Takeaway
Hella Infra Market Limited is one of India’s largest technology-enabled building-material platforms, combining manufacturing, private labels, distribution and technology across a very broad construction-material portfolio.
The company has achieved exceptional top-line scale: FY2025 revenue from operations was approximately ₹18,472 Cr, while EBITDA was approximately ₹1,472 Cr. However, PAT was only around ₹220 Cr, highlighting the importance of finance costs, depreciation and the capital required to support rapid expansion.
The biggest development for unlisted shareholders is the 2026 Shalimar Paints transaction. Infra.Market had confidentially filed for a standalone IPO in 2025, but in August 2026 the company moved toward a proposed share-swap/restructuring with listed Shalimar Paints. If completed, this could provide a different route to public-market liquidity without a standalone Infra.Market IPO.
For investors evaluating the unlisted shares today, the most important factors are therefore:
1. Final Shalimar Paints swap ratio
2. Independent valuation used for the transaction
3. Treatment of existing Hella Infra Market shareholders
4. Post-transaction ownership
5. QIP pricing and dilution
6. Ability to convert strong EBITDA growth into PAT and cash flow
The current unlisted-market prices should be treated cautiously because different platforms are quoting materially different prices.
Disclaimer: Unlisted-share prices are indicative OTC quotations and can differ significantly between dealers. There is no NSE/BSE order book for Hella Infra Market. The proposed Shalimar Paints transaction remains subject to applicable approvals and final terms. Transaction valuations, swap ratios and future liquidity are not guaranteed. This report is for informational purposes only and is not investment advice.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
