
Business, Financials & Unlisted Share Analysis
Company: Down Town Hospital Limited
Incorporated: 31 January 1986
Hospital commissioned: 15 February 1989
CIN: U85110AS1986PLC002477
ISIN: INE06NN01012
Registered Office: G.S. Road, Dispur, Guwahati, Assam – 781006
Industry: Healthcare / Hospitals
Status: Unlisted Public Company
Hospital Capacity: ~300 beds
Face Value: ₹10 per share
Paid-up Capital: ~₹3.03 Cr
Total Shares: ~30 lakh
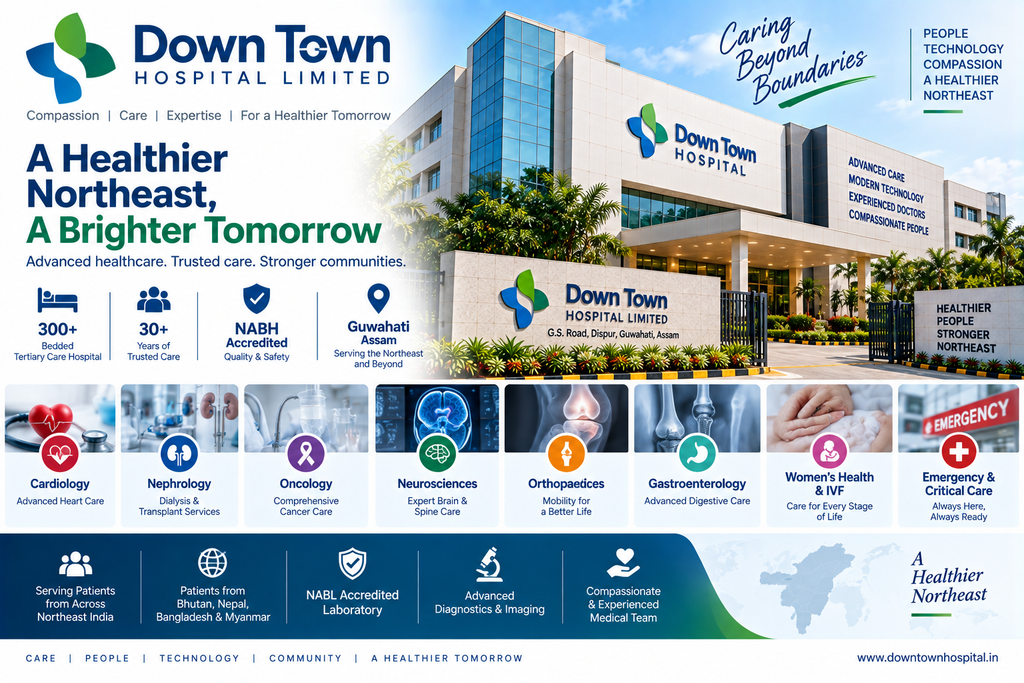
Down Town Hospital is one of the oldest organised private multispecialty hospitals in Northeast India. The hospital was established in Guwahati in 1989 and operates a roughly 300-bed tertiary-care facility.
1. Company Overview
Down Town Hospital Limited is a Guwahati-based healthcare company operating a multispecialty tertiary-care hospital on G.S. Road, Dispur.
The hospital was established by the Dutta family and has built a strong regional presence over more than three decades.
It is positioned as a healthcare destination not only for Assam and the wider Northeast but also for patients from neighbouring countries such as Bhutan, Nepal, Bangladesh and Myanmar.
The company describes itself as the first multispecialty corporate hospital in Northeast India, while third-party healthcare sources also identify it as a regional pioneer in NABH accreditation and advanced procedures.
2. Hospital Infrastructure
Down Town Hospital operates a facility of approximately 300 beds.
Its infrastructure includes:
- Intensive Care Units
- Modular operating theatres
- Diagnostic laboratory
- Radiology
- CT / imaging services
- Cath lab
- Dialysis
- Emergency & critical care
- Blood bank / transfusion services
- IVF facilities
- Advanced surgical facilities
The hospital has around 15 operating theatres, covering procedures across multiple specialties.
3. Major Medical Specialties
The hospital has a broad tertiary-care offering.
Cardiology
Includes cardiology and interventional cardiology services supported by a cath lab.
Nephrology & Renal Care
The hospital provides nephrology and dialysis services and has historically been associated with kidney transplantation in the Northeast.
Transplantation
Down Town Hospital has performed kidney transplantation and has expanded into liver-transplant services.
Oncology
The hospital provides cancer-related diagnostic and treatment services.
Neurosciences
Neurology and neurosurgical services form part of the hospital’s tertiary-care offering.
Orthopaedics
The hospital provides orthopaedic surgery, trauma care and joint-replacement procedures.
Gastroenterology
Gastrointestinal diagnostics and procedures form another important specialty.
Women’s Health & IVF
The hospital provides obstetrics, gynaecology and fertility/IVF services.
4. Accreditation & Quality
Down Town Hospital has developed its healthcare credentials over several decades.
The hospital is reported as having:
- NABH accreditation
- NABL-accredited laboratory
- ISO 9001 certification
It has also been recognised as the first NABH-accredited hospital in Northeast India.
The accreditation ecosystem is important because hospital businesses increasingly compete on clinical quality, safety systems, diagnostics and institutional credibility rather than only on bed capacity.
5. Regional Catchment Area
One of Down Town Hospital’s key strategic advantages is its location in Guwahati.
Guwahati acts as a healthcare hub for Assam and much of Northeast India.
The hospital therefore has access to patients from:
- Assam
- Meghalaya
- Nagaland
- Arunachal Pradesh
- Manipur
- Mizoram
- Tripura
- Other Northeast regions
The hospital also states that it serves patients from neighbouring countries including Bhutan, Nepal, Bangladesh and Myanmar.
This creates a regional referral model similar to other established tertiary-care hospitals.
6. Financial Performance
Revenue & PAT Trend
₹ Crore
| Financial Year | Revenue | PAT |
|---|---|---|
| FY2021 | 52.40 | 2.00 |
| FY2022 | 66.40 | 4.10 |
| FY2023 | 79.83 | 5.37 |
| FY2024 | 86.59 | 6.16 |
| FY2025 | 91.43 | 5.83 |
The company has grown revenue consistently over the five-year period.
Revenue increased from approximately ₹52.4 Cr in FY2021 to ₹91.43 Cr in FY2025, representing roughly 15% CAGR.
However, FY2025 PAT declined from ₹6.16 Cr to ₹5.83 Cr despite revenue growth.
7. FY2025 Financial Snapshot
| Particular | FY2025 |
|---|---|
| Total Income | ₹91.43 Cr |
| Net Profit | ₹5.83 Cr |
| PAT Margin | ~6.4% |
| Equity Capital | ₹3.03 Cr |
| Reserves & Surplus | ₹60.63 Cr |
| Net Worth | ₹63.65 Cr |
| Book Value/Share | ₹210.07 |
| EPS | ~₹19 |
| Fixed Assets | ₹49.15 Cr |
| Trade Receivables | ₹16.27 Cr |
| Trade Payables | ₹15.50 Cr |
These figures are based on the FY2025 financial information reported by the company/secondary databases.
8. Revenue Mix
The FY2025 annual report provides useful detail on the composition of operating revenue.
Revenue from operations was approximately ₹90.70 Cr.
Major service revenue included:
| Revenue Source | FY2025 |
|---|---|
| Laboratory Charges | ~₹12.12 Cr |
| Room Charges | ~₹8.95 Cr |
| Operation Procedure Charges | ~₹2.50 Cr |
| Ultrasound Charges | ~₹1.53 Cr |
| X-ray Charges | ~₹0.83 Cr |
| Nursing & Medical Care | ~₹1.51 Cr |
| O.T. Rent | ~₹0.64 Cr |
| Other operating/service revenue | Significant |
The annual report also shows revenue from finished goods and traded goods alongside healthcare services.
The diversified revenue base is important because the hospital is not dependent on a single specialty.
9. Profitability
The company has maintained profitability throughout the reported five-year period.
However, the margin profile remains relatively moderate for a tertiary-care hospital.
FY2025:
Revenue: ₹91.43 Cr
PAT: ₹5.83 Cr
PAT Margin: ~6.4%
The PAT margin was around 7% in FY2023–FY2024 before declining to roughly 6.4% in FY2025.
This suggests that future earnings growth will depend not only on increasing patient volumes but also on:
- Better occupancy
- Higher-value procedures
- Specialty mix
- Pricing
- Operating leverage
- Cost control
10. Balance Sheet
The company’s FY2025 net worth was approximately ₹63.65 Cr, compared with ₹57.94 Cr in FY2024.
| Parameter | FY2024 | FY2025 |
|---|---|---|
| Net Worth | ₹57.94 Cr | ₹63.65 Cr |
| Reserves | ₹54.94 Cr | ₹60.63 Cr |
| Fixed Assets | ₹47.96 Cr | ₹49.15 Cr |
| Trade Receivables | ₹12.48 Cr | ₹16.27 Cr |
| Trade Payables | ₹11.38 Cr | ₹15.50 Cr |
Book value increased from approximately ₹193/share to ₹210/share.
11. Debt Position
Available unlisted-market data indicates a relatively low debt-to-equity ratio of around 0.11x.
However, MCA-derived data also shows secured/open charges on the company, so investors should examine the latest annual report and charge filings before assuming that the company is effectively debt-free.
For a hospital operator, moderate leverage can be useful for capacity expansion, but excessive debt can put pressure on cash flows because hospital expansion requires significant upfront capital.
12. Cash Flow
The FY2025 data indicates:
| Cash Flow | FY2024 | FY2025 |
|---|---|---|
| Operating Cash Flow | ₹14.70 Cr | ₹7.71 Cr |
| Investing Cash Flow | -₹25.99 Cr | -₹13.54 Cr |
| Financing Cash Flow | -₹0.30 Cr | ₹7.12 Cr |
| Net Cash Generated | ₹6.98 Cr | ₹8.27 Cr |
The reduction in operating cash flow despite continued profitability is worth monitoring.
The combination of PAT, operating cash flow and receivables should be tracked together rather than evaluating earnings in isolation.
13. Promoter Holding
Promoter ownership has historically been high.
The FY2023 annual report showed:
| Promoter | Holding |
|---|---|
| Dr. Narendra Nath Dutta | 68.11% |
| Mrs. Bandana Dutta | 3.63% |
| Total Promoter Group | 71.74% |
No promoter shares were reported as pledged/encumbered in that disclosure.
More recent secondary-market data reports promoter ownership at approximately 71.74%, with the remaining shares held by public investors.
High promoter ownership can provide continuity of control, but it also contributes to relatively limited public float and therefore potentially lower liquidity.
14. Management
The Dutta family remains central to the management and ownership structure.
Key management/director names appearing in company records include:
- Dr. Narendra Nath Dutta – Chairman & Managing Director
- Bandana Dutta – Whole-Time Director
- Mayurakshi Dutta – Executive/Whole-Time Director
- Gariasi Dutta
- Joutishman Dutta
- Biswa Datta
- Dr. B.K. Gogoi
- Sabita Tamuli – nominee director
Company records identify Down Town Hospital as an active public company.
15. Unlisted Share Price
Down Town Hospital does not have an NSE/BSE market price.
Its shares are traded through private/off-market transactions.
Current indicative prices vary materially between unlisted-share dealers:
BuyUnlistedShares: approximately ₹375/share as of 16 September 2026.
Another unlisted-share platform reported approximately ₹302/share as of 1 August 2026.
A third platform currently shows other dealer quotes, demonstrating the lack of a single transparent market price.
Therefore, ₹302–₹375 should be treated as indicative OTC reference levels, not an exchange-traded price.
16. Indicative Valuation
With approximately 30 lakh shares outstanding, the implied equity value would be:
At ₹375/share
₹375 × 30 lakh = ~₹112.5 Cr
At ₹302/share
₹302 × 30 lakh = ~₹90.6 Cr
Using FY2025 EPS of approximately ₹19:
| Price | Approx. P/E |
|---|---|
| ₹302 | ~15.6x |
| ₹375 | ~19.3x |
Against FY2025 book value of approximately ₹210/share:
| Price | Approx. P/B |
|---|---|
| ₹302 | ~1.44x |
| ₹375 | ~1.78x |
The indicative valuation therefore depends significantly on the actual transaction price available to an investor.
17. Dividend Track Record
For FY2025, the company proposed a dividend of ₹1 per equity share on a ₹10 face-value share.
At ₹375/share, a ₹1 dividend represents an indicative yield of only around 0.27%.
Therefore, the investment thesis is primarily linked to business growth and potential valuation appreciation, rather than dividend income.
18. Competitive Position
Down Town Hospital operates in a competitive Guwahati healthcare market alongside other established hospitals.
Its differentiation comes from:
1. Legacy
Operating since 1989, it has built a long-standing brand in Northeast India.
2. Tertiary Care
The hospital provides advanced specialties beyond routine secondary-care services.
3. Regional Catchment
Guwahati provides access to patients from across the Northeast.
4. Accreditation
NABH/NABL credentials support institutional credibility.
5. Established Infrastructure
A 300-bed facility with multiple operating theatres, diagnostics and specialised departments provides a substantial existing asset base.
19. Growth Drivers
Increasing Healthcare Spending
India’s healthcare expenditure continues to shift toward private tertiary-care services, particularly for complex procedures and diagnostics.
Northeast Healthcare Hub
Guwahati has the potential to remain a referral centre for patients from the wider Northeast.
Specialty Mix
Higher-value specialties such as:
- Cardiology
- Oncology
- Neurosurgery
- Orthopaedics
- Transplantation
- IVF
- Gastroenterology
can increase revenue per patient compared with basic hospitalisation.
Diagnostic Revenue
Laboratory, imaging and diagnostic services are meaningful revenue contributors and can provide recurring hospital-linked income.
Government & Institutional Empanelment
The hospital has been part of government and insurance/TPA networks, expanding its addressable patient base. It was also listed for CGHS empanelment through April 2029 in a May 2026 government-order compilation.
20. Key Risks
Limited Liquidity
This is the most important risk for an unlisted investor.
There is no NSE/BSE order book, so buying and selling depends on private transactions and available counterparties.
Moderate Profit Margins
Despite revenue growth, PAT margin remains around 6–7%.
Receivables
Trade receivables increased to approximately ₹16.27 Cr in FY2025 from ₹12.48 Cr. This needs monitoring because hospital receivables can rise through insurer, TPA and institutional billing cycles.
Capital Intensity
Hospitals require continuing investment in:
- Medical equipment
- ICUs
- Operating theatres
- Imaging
- Technology
- Hospital infrastructure
Regional Concentration
The company’s primary hospital asset is concentrated in Guwahati. Expansion into other cities would require substantial capital.
Valuation Transparency
Unlike an NSE/BSE-listed company, there is no continuously discovered market price.
21. IPO / Listing Status
As of September 2026, Down Town Hospital remains unlisted.
I did not find a confirmed DRHP, IPO price band or announced listing timetable in the sources reviewed.
Therefore, investors should not assume that the current OTC price represents a pre-IPO price with a defined listing catalyst. The company would need to undertake the required regulatory and listing process before any IPO could occur.
22. Investment Snapshot
| Parameter | Down Town Hospital |
|---|---|
| Established | 1986 |
| Hospital operational since | 1989 |
| Location | Guwahati, Assam |
| Industry | Healthcare |
| Hospital Capacity | ~300 beds |
| Operating Model | Multispecialty tertiary care |
| FY25 Revenue | ₹91.43 Cr |
| FY25 PAT | ₹5.83 Cr |
| FY25 PAT Margin | ~6.4% |
| FY25 Net Worth | ₹63.65 Cr |
| Book Value | ~₹210/share |
| EPS | ~₹19 |
| Promoter Holding | ~71.74% |
| Indicative OTC Price | ~₹302–₹375 |
| Indicative Market Value | ~₹91–113 Cr |
| NSE/BSE Listed | No |
| IPO/DRHP | No confirmed process found |
| Main Strength | Established regional tertiary-care franchise |
| Main Risk | Low liquidity + moderate margins + regional concentration |
UnlistedCart Takeaway
Down Town Hospital Limited is a long-established regional healthcare franchise with more than three decades of operating history and a 300-bed tertiary-care hospital in Guwahati.
The company has demonstrated consistent revenue growth, with revenue increasing from approximately ₹52.4 Cr in FY2021 to ₹91.43 Cr in FY2025. Net worth also increased to approximately ₹63.65 Cr.
The interesting part of the business is its regional positioning. Guwahati acts as a healthcare hub for Northeast India, while Down Town Hospital has built capabilities across cardiology, nephrology, transplantation, oncology, orthopaedics, neurosciences, diagnostics, IVF and other specialties.
At the same time, investors should watch profit margins, operating cash flow, receivables and capacity utilisation. FY2025 revenue grew, but PAT declined slightly and operating cash flow fell from ₹14.7 Cr to ₹7.7 Cr.
At indicative OTC prices of roughly ₹302–₹375, the implied equity value is approximately ₹91–113 Cr, versus FY2025 net worth of ₹63.65 Cr. The resulting valuation is roughly 1.4–1.8x book value and 16–19x FY2025 earnings, depending on the actual transaction price. These are indicative calculations, not exchange-market valuations.
The key point for an investor is that Down Town Hospital is a genuine operating healthcare business with a long regional franchise, but the investment should be evaluated alongside its limited liquidity and the absence of a confirmed IPO/listing catalyst.
Disclaimer: Unlisted-share prices are indicative OTC reference prices and can vary significantly between dealers and transactions. There is no NSE/BSE order book for Down Town Hospital. Liquidity, valuation and exit price may differ materially from quoted indicative prices. Financial figures should be cross-checked against the latest audited company filings before making an investment decision. This report is for informational purposes only and is not investment advice.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
