
CIN: U74999HR1973PLC070262
ISIN: INE02YY01015
Face Value: ₹10 per share
Incorporated: 2 June 1973
Registered Office: Faridabad, Haryana
Listing Status: Unlisted Public Company
Shares Outstanding: ~25.08 lakh
FY26 Revenue from Operations: ₹459.63 Cr
FY26 PAT: ~₹76.15 Cr
FY26 EPS: ~₹303.58
Indicative Unlisted Price: ~₹3,150/share
Indicative Market Capitalisation: ~₹790 Cr
Executive Summary
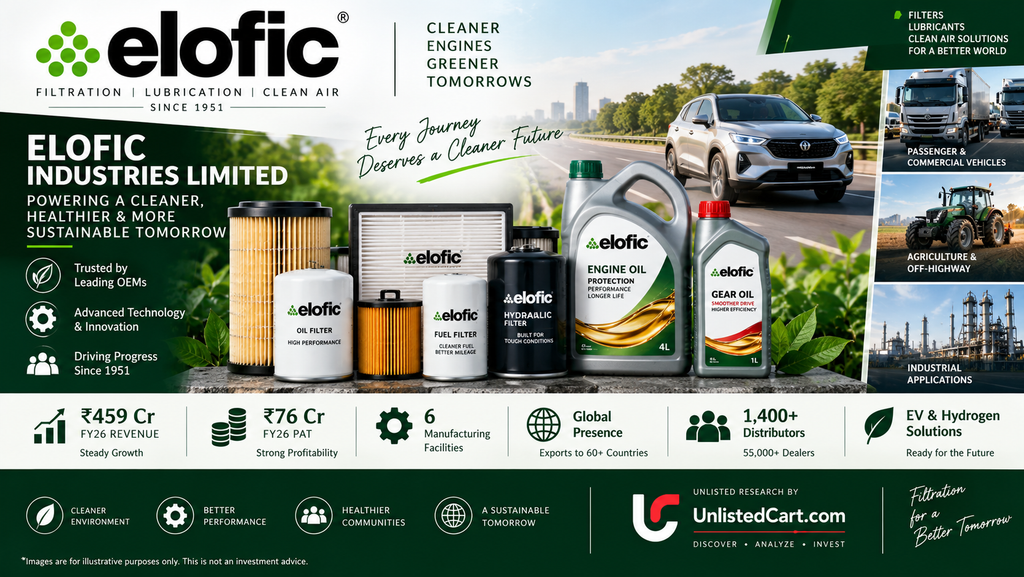
Elofic Industries Limited is an established Indian manufacturer of automotive and industrial filtration, lubrication and clean-air products. Although the legal company was incorporated in 1973, the business traces its origins to 1951, giving it more than seven decades of operating history. The company serves OEMs, aftermarket customers and industrial users in India and overseas.
Elofic’s product portfolio includes:
- Oil filters
- Air filters
- Cabin-air filters
- Fuel filters
- Hydraulic filters
- Lubricants
- Grease
- Coolants
- Diesel Exhaust Fluid
- EV filters
- Hydrogen filters
- Clean-air products
The company has developed a substantial OEM customer base and its official website lists customers including Maruti Suzuki, Tata Motors, Mahindra & Mahindra, Royal Enfield, TVS Motor, Bajaj Auto, JCB, Bosch, Renault-Nissan-Mitsubishi, Volvo Eicher and others.
The investment case is attractive because Elofic combines:
Long operating history + OEM relationships + aftermarket distribution + exports + zero debt + strong cash generation + EV/hydrogen filtration opportunity.
However, FY26 also highlights an important concern:
Revenue continued to grow, but operating profitability declined materially.
Latest secondary-market financial data shows FY26 revenue from operations of ₹459.63 Cr, but EBITDA declined from roughly ₹123 Cr to ₹117 Cr on one financial database, while another unlisted-market source reports operating EBITDA of ₹89.7 Cr. The difference appears to arise from differing EBITDA definitions. Therefore, investors should rely primarily on audited FY26 financial statements for final margin analysis.
At an indicative price of approximately ₹3,150, Elofic is trading around 10.3x FY26 earnings and approximately 2.3x book value, based on the latest available unlisted-market data.
Overall, the company presents an interesting value-oriented unlisted auto-component opportunity, but investors should monitor margin recovery and the sustainability of earnings before assigning a premium valuation.
Company Overview
Elofic Industries Limited is headquartered in Faridabad, Haryana and operates in the filtration and lubrication industry.
The company’s roots go back to 1951, when it began manufacturing approximately 100 filters per day with a small workforce. It became a public limited company in 1996. Over the decades, it expanded into OEM filtration, lubricants, exports, clean-air products and newer filtration technologies.
The company’s official website currently describes Elofic as having:
- More than 70 years of experience
- 1,200+ professionals
- Six manufacturing facilities
- Presence in Faridabad, Nalagarh and Hosur
- Global customers including Fortune 1000 companies
The company has also set a target of achieving ₹7,000 million (₹700 Cr) sales turnover by FY2027–28.
Business Model
Elofic operates primarily as a manufacturing-led automotive and industrial filtration company.
Its business can broadly be divided into four areas:
1. Automotive Filtration
The company manufactures filtration products used in:
- Passenger vehicles
- Commercial vehicles
- Two-wheelers
- Tractors
- Construction equipment
- Industrial machinery
Its portfolio includes oil, air, cabin, fuel and hydraulic filters.
2. Lubricants & Grease
Elofic manufactures lubricants and grease used across automotive and industrial applications.
Lubricants help reduce friction and wear, improve component life and support machine efficiency.
3. Clean-Air Products
The company has expanded beyond engine filtration into air-purification and clean-air products.
Its portfolio includes air purifiers and Clean Air Towers, including products designed around virus protection.
4. New-Energy Filtration
One of the more interesting emerging areas is filtration for:
- Battery electric vehicles
- Hydrogen applications
- CNG vehicles
The FY25 annual report specifically highlighted the development of advanced filters for BEV, hydrogen and CNG applications.
Manufacturing Footprint
Elofic’s FY25 annual report highlighted six state-of-the-art manufacturing units located across Faridabad, Hosur, Noida and Nalagarh, with production capacity of more than 110 million pieces per year.
The company also maintains warehouses in:
- Ahmedabad
- Faridabad
- Nagpur
- Zirakpur
- Lucknow
- Hosur
This manufacturing and distribution footprint provides the company with proximity to major automotive and industrial markets.
OEM Relationships
OEM relationships are one of Elofic’s strongest competitive advantages.
The company’s official customer list includes:
- Maruti Suzuki
- Tata Motors
- Mahindra & Mahindra
- Royal Enfield
- TVS Motor
- Bajaj Auto
- JCB
- Bosch
- Renault-Nissan-Mitsubishi
- Volvo Eicher
- New Holland
- Suzuki Motorcycles
- MG Motor
- Force Motors
- Kirloskar Oil Engines
- Doosan Bobcat
- CASE Construction
- Toyota Material Handling
- VST Tillers & Tractors
The breadth of the customer list indicates exposure across passenger vehicles, two-wheelers, commercial vehicles, tractors, construction equipment and industrial applications.
The FY25 annual report also states that Elofic had partnerships with more than 48 automotive OEMs in India.
Aftermarket Distribution Network
The aftermarket is another important part of the business.
According to the FY25 annual report, Elofic had approximately:
1,400 distributors and 55,000 dealers across India.
This provides the company with a second revenue channel beyond OEM supply.
The aftermarket can also provide recurring demand because filters, lubricants and related products are consumables that need periodic replacement.
Elofic has also developed the Nishtha/Saathi loyalty program for retailers and dealers purchasing its filters and lubricants through authorised stockists.
Export Business
Exports have become increasingly important.
The FY25 annual report reported export sales of approximately ₹214.76 Cr, compared with ₹134.16 Cr in FY24 — an increase of roughly 60%. Domestic sales increased more modestly to ₹210.15 Cr.
The company exports to markets including:
- USA
- Europe
- Africa
- South America
- Japan
- China
- Middle East and other markets
The company described FY25 as achieving its highest-ever export turnover.
This export opportunity is important because it reduces dependence on the Indian automotive market and provides access to larger international customers.
Research & Development
Elofic has developed an in-house R&D centre approved by the Department of Scientific and Industrial Research (DSIR), Government of India.
The FY25 annual report highlighted:
- 21 patents
- 8 additional patents pending
- NABL-certified laboratory
- In-house product development
- Industry 4.0 initiatives
- Advanced testing capabilities
The company is also working on next-generation filtration products for BEV, hydrogen and CNG applications.
This gives Elofic an opportunity to participate in the changing vehicle architecture rather than remaining dependent solely on conventional ICE vehicles.
FY2025–26 Financial Performance
Latest available financial data shows the following:
| Particulars | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|
| Revenue from Operations | ₹359.7 Cr | ₹351.8 Cr | ₹450.1 Cr | ₹459.6 Cr |
| Total Revenue incl. Other Income | ₹361.7 Cr | ₹359.2 Cr | ₹461.5 Cr | ₹487.0 Cr |
| PAT | ₹37.6 Cr | ₹48.1 Cr | ₹77.3 Cr | ₹76.2 Cr |
| EPS | ₹149.75 | ₹191.73 | ₹307.99 | ₹303.58 |
| Net Worth | ₹209.2 Cr | ₹256.5 Cr | ₹332.8 Cr | ₹410.3 Cr |
FY26 revenue from operations increased approximately 2.1%, while PAT declined slightly from FY25.
This means the FY26 picture is more about consolidation than acceleration.
Five-Year Growth Perspective
Revenue from operations increased from approximately ₹330 Cr in FY22 to ₹460 Cr in FY26.
This represents roughly 8.6% CAGR over the period.
PAT increased from approximately ₹39.5 Cr to ₹76.2 Cr over the same period, representing roughly 17.9% CAGR.
Therefore, over the medium term, profit growth has significantly outpaced revenue growth.
However, FY26 showed a moderation in this trend.
This is an important distinction for investors:
Historical earnings growth has been strong, but the latest year showed margin pressure.
Profitability Analysis
FY25 was an exceptionally strong year for Elofic from a profitability perspective.
The company’s FY25 audited annual report reported:
- EBITDA before depreciation/finance: ₹119.96 Cr
- PBT: ₹104.50 Cr
- PAT: ₹74.58 Cr
compared with PAT of ₹45.79 Cr in FY24.
Latest FY26 secondary data indicates:
- PBT: ~₹96.5 Cr
- PAT: ~₹76.2 Cr
- PAT margin: ~15.6%
One third-party analysis reports operating EBITDA of ₹89.7 Cr and operating margin of 19.5%, down from FY25’s ~24.9%. Another financial database calculates EBITDA differently and reports ~₹117 Cr. The divergence reinforces the need to use the FY26 audited statement for the final EBITDA definition.
The key conclusion remains:
FY26 revenue grew, but operating profitability was under pressure.
Raw Material & Margin Risk
Filtration manufacturing is sensitive to:
- Steel
- Paper/filter media
- Plastics
- Rubber
- Aluminium
- Lubricant inputs
- Energy
- Labour
A recent analysis of FY26 financials indicates that raw-material costs increased as a percentage of revenue and employee costs also increased faster than sales, contributing to margin compression.
This is one of the most important things investors should monitor going forward.
If revenue growth returns to 8–10% while margins recover toward FY25 levels, earnings could compound strongly.
If margins remain around FY26 levels, valuation upside may be more limited.
Balance Sheet Strength
The balance sheet is a major positive.
Latest FY26 data indicates:
- Total assets: ₹473.56 Cr
- Total equity: ₹410.26 Cr
- Total liabilities: ₹63.30 Cr
- Borrowings: Nil
- Fixed assets: ₹172.3 Cr
- Trade receivables: ₹68.3 Cr
- Inventory: ₹78.8 Cr
- Investments: ₹4.6 Cr
The company therefore has a very low financial leverage profile.
Debt-to-equity is effectively zero.
This is particularly valuable in a cyclical manufacturing business.
Cash Flow
FY26 operating cash flow was approximately:
₹78.18 Cr
compared with ₹46.26 Cr in FY25.
Investing cash flow was negative ₹17.12 Cr, while financing cash flow was negative ₹2.88 Cr.
Net cash generation during FY26 was approximately ₹58.19 Cr.
This is a significant improvement from FY25, when the company generated negative net cash after investing and financing flows.
The combination of:
₹76 Cr PAT + ₹78 Cr operating cash flow + zero debt
is a healthy characteristic.
Capital Expenditure
The company has been investing in its manufacturing capabilities.
Latest balance-sheet data shows fixed assets increasing from approximately ₹70 Cr in FY25 to ₹172 Cr in FY26, while CWIP stood around ₹1.8 Cr.
This is a substantial increase in the fixed-asset base.
The key question for investors is whether the additional manufacturing capacity will translate into:
- Higher volumes
- Better export growth
- New OEM programs
- Higher utilisation
- Improved return on capital
If utilisation improves, the new asset base could provide operating leverage.
Competitive Advantages
1. Seven Decades of Experience
Elofic’s operating history dates back to 1951, creating substantial experience in filtration and lubrication.
2. Strong OEM Relationships
Its customer base spans major automobile, tractor, commercial vehicle and industrial manufacturers.
3. Large Aftermarket Network
Approximately 1,400 distributors and 55,000 dealers provide significant distribution reach.
4. Export Capability
Exports have become a major contributor, with FY25 export turnover reaching a record level.
5. Debt-Free Balance Sheet
Zero borrowings significantly reduce financial risk.
6. In-House R&D
DSIR-approved R&D, patents and product-development capabilities create barriers to entry.
7. EV/Hydrogen Opportunity
Development of BEV, hydrogen and CNG filters provides an avenue for the company to remain relevant as mobility changes.
Growth Drivers
Automotive Production Growth
Growing Indian vehicle production creates structural demand for filtration products.
Aftermarket Replacement Demand
Filters, lubricants and related products require regular replacement, providing recurring demand.
Export Expansion
FY25 export growth was particularly strong and provides a potential second engine of growth.
EV & Hydrogen Filtration
The transition to electric and alternative-fuel vehicles creates opportunities for new filtration technologies.
Industrial Filtration
Expansion beyond passenger vehicles into industrial machinery, construction equipment and other applications can diversify the business.
₹700 Cr Revenue Target
Elofic has publicly stated an objective of achieving approximately ₹700 Cr turnover by FY2027–28.
From FY26 revenue of approximately ₹460 Cr, achieving ₹700 Cr would require significant growth over the next two years.
Therefore, this target should be treated as an important monitorable rather than an assumption in valuation.
Key Risks
1. Margin Compression
FY26 operating margins declined compared with FY25.
A continuation of margin pressure could limit EPS growth even if revenue grows.
2. Automotive Cyclicality
A slowdown in vehicle production could affect OEM demand.
3. Raw Material Inflation
Raw-material costs can materially affect profitability if price increases cannot be passed through to customers.
4. Customer Concentration
OEM businesses are generally dependent on customer production schedules, model cycles and annual price negotiations.
5. Working Capital
Inventory and receivables need to be monitored as the company expands.
6. Unlisted Liquidity
There is no continuous NSE/BSE trading mechanism.
An investor may therefore face:
- Limited buyers
- Wide bid-ask spreads
- Long exit periods
- Significant price variation between intermediaries
7. Valuation Risk
Although the P/E looks reasonable compared with many high-growth businesses, the company is still valued above book value by a significant margin.
8. IPO Uncertainty
Elofic remains unlisted and there is no confirmed IPO date in the sources reviewed.
Investors should not pay a substantial premium purely on the assumption that an IPO is imminent.
Current Unlisted Price
As of September 2026, unlisted-market references show Elofic around:
₹3,075–₹3,150/share
with some platforms showing higher historical or indicative levels. UnlistedZone shows approximately ₹3,150 as of 10 September 2026, while another unlisted-market source also reports ₹3,150 as of 13 September.
Moneycontrol currently displays approximately ₹2,969, while its page explicitly states that unlisted prices are derived from partners and are indicative rather than exchange-traded prices.
Therefore, investors should consider ₹3,000–₹3,150 as an indicative market zone rather than treating one platform’s number as a firm market price.
Valuation
At approximately ₹3,150/share:
- Shares outstanding: ~25.08 lakh
- Implied market cap: ~₹790 Cr
- FY26 EPS: ~₹303.58
- P/E: ~10.4x
- Book value: ~₹1,365/share
- P/B: ~2.3x
- Debt/Equity: 0x
- ROE: approximately 23% on the latest platform data
These figures indicate that Elofic is not trading at an extreme valuation.
Earnings-Based Valuation Sensitivity
Using FY26 EPS of approximately ₹303.58:
| P/E Multiple | Indicative Value |
|---|---|
| 7x | ₹2,125 |
| 8x | ₹2,429 |
| 9x | ₹2,732 |
| 10x | ₹3,036 |
| 11x | ₹3,339 |
| 12x | ₹3,643 |
| 13x | ₹3,946 |
| 15x | ₹4,554 |
At approximately ₹3,150, the stock is effectively trading around 10.4x FY26 earnings.
This is reasonable if earnings stabilise and growth resumes.
A re-rating toward 12–13x could be justified if Elofic demonstrates:
- Revenue growth above 10%
- Margin recovery
- Strong export growth
- Better utilisation of new assets
- Continued debt-free operations
- Successful EV/hydrogen product expansion
Dividend
For FY25, the company proposed a final dividend of ₹5 per equity share.
At ₹3,150, a ₹5 dividend represents only around 0.16% yield.
Therefore, Elofic should primarily be evaluated as an earnings-growth and value-compounding opportunity, rather than a dividend-yield investment.
IPO / Listing Status
Elofic Industries remains an unlisted public company.
The reviewed unlisted-market sources do not indicate a current DRHP filing or confirmed IPO date. Moneycontrol currently shows DRHP Status: No.
Any future IPO could create a potential liquidity catalyst, but investors should not build the investment thesis around an unconfirmed listing.
Investment Scorecard
| Parameter | Assessment |
|---|---|
| Business Quality | 8/10 |
| Brand & Industry Position | 8/10 |
| OEM Relationships | 8.5/10 |
| Balance Sheet | 9/10 |
| Cash Flow | 8/10 |
| Growth Potential | 7.5/10 |
| Margin Stability | 6.5/10 |
| Valuation | 8/10 |
| Liquidity | 4/10 |
| Overall | 7.8/10 |
Overall Assessment
Elofic Industries Limited is an interesting unlisted auto-component and industrial manufacturing opportunity, particularly for investors looking for a profitable, debt-free business at a moderate earnings multiple.
The strongest part of the investment thesis is the combination of:
**70+ years of operating history
- strong OEM relationships
- 55,000-dealer aftermarket network
- export opportunity
- zero debt
- strong cash generation
- R&D capabilities
- EV/hydrogen filtration opportunity.**
The main concern is the FY26 margin slowdown.
Revenue increased only modestly, while operating profitability weakened from the exceptionally strong FY25 level. The company therefore needs to demonstrate that FY26 was a temporary margin correction rather than the beginning of a structural decline.
At approximately ₹3,000–₹3,150, the valuation around 10x FY26 earnings appears relatively reasonable for a debt-free company with a strong balance sheet and established market position.
However, at significantly higher prices, investors would need stronger confidence in:
- Revenue growth
- Margin recovery
- Export expansion
- New OEM wins
- Capacity utilisation
- EV/hydrogen product contribution
- Cash-flow conversion
Investment View
BUSINESS: Strong
BALANCE SHEET: Excellent
GROWTH: Moderate-to-Good
VALUATION: Reasonable
RISK: Moderate
LIQUIDITY: Low
Our view: A fundamentally sound unlisted auto-component business with attractive balance-sheet quality and reasonable valuation, but FY26 margin compression needs close monitoring before assigning a higher multiple.
Important Disclaimer
This report is prepared for research and educational purposes using publicly available company disclosures, the company’s official website, audited FY2024–25 disclosures and publicly available FY2025–26 financial data from unlisted-market sources. Certain FY26 financial figures have not been independently reproduced from the company’s FY2025–26 annual-report PDF in this research and should therefore be verified against the audited filing before making an investment decision.
Unlisted share prices are indicative and may differ materially from actual negotiated transaction prices. Unlisted securities carry risks including illiquidity, limited price discovery, valuation uncertainty, lack of continuous trading and possible loss of capital. An IPO or listing should not be assumed unless officially announced and approved.
This report does not constitute investment advice, an offer, solicitation or recommendation to buy or sell securities.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
