
Sector: Industrial Engineering / Hydraulics
Industry: Fluid Power, Hydraulic Systems & Machinery
Former Name: Eaton Fluid Power Limited
Current Legal Name: Danfoss Systems Private Limited
CIN: U29120PN1965PTC015850
ISIN: INE762B01015
Face Value: ₹10 per equity share
Registered Office: 145, Off Mumbai-Pune Road, Pimpri, Pune – 411018
Status: Active, Private, Unlisted
Promoter / Parent: Danfoss Fluid Power Private Limited
Important: This report uses the name Eaton Fluid Power because that is the name under which the company is commonly known in the Indian unlisted-share market. The legal entity has since undergone multiple name/status changes.
1. Executive Summary
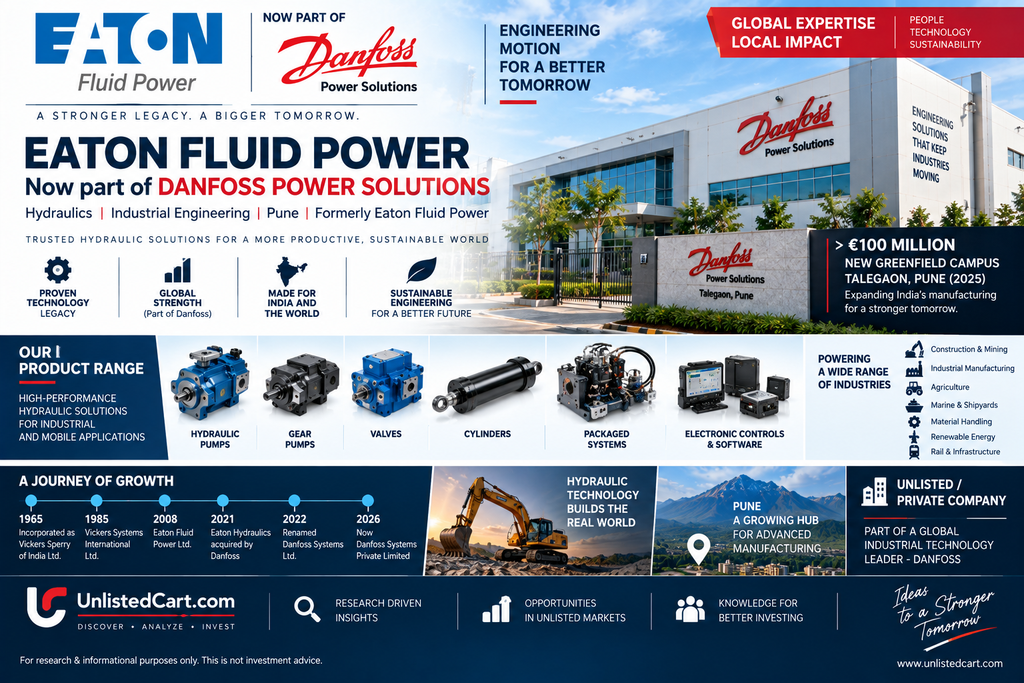
Eaton Fluid Power Limited was an established Indian hydraulics business with roots going back to 1965. The company was originally incorporated as Vickers Sperry of India Limited, subsequently became Vickers Systems International Limited, then Eaton Fluid Power Limited in 2008, and later Danfoss Systems Limited in 2022. In 2026, it became Danfoss Systems Private Limited.
The business manufactures and supplies hydraulic products and systems, with capabilities spanning design, manufacturing, assembly, sales and marketing of hydraulic products and systems. Danfoss describes its broader Power Solutions business as covering hydraulics, fluid conveyance, electrification, electronic controls and software.
The company remains strategically relevant because it sits within the Danfoss ecosystem, while the broader Danfoss Power Solutions business continues to invest significantly in India. In March 2025, Danfoss announced a more than €100 million investment in a new 27,000-square-metre Talegaon, Pune campus, including an Application Development Center.
However, there is a major distinction for investors:
Eaton Fluid Power should not currently be treated like a conventional freely available unlisted/pre-IPO opportunity.
Following an NCLT-approved capital reduction in 2025, 1,66,778 non-promoter equity shares were cancelled and the shareholders were paid ₹872.99 per cancelled share. The resulting paid-up capital became ₹6,79,74,890 divided into 67,97,489 equity shares.
The company subsequently moved from public to private status. Current corporate records identify Danfoss Systems Private Limited as an active private unlisted company.
2. Company Evolution
| Period | Company Name / Event |
|---|---|
| 1965 | Incorporated as Vickers Sperry of India Limited |
| 1985 | Renamed Vickers Systems International Limited |
| 2008 | Renamed Eaton Fluid Power Limited |
| 2021 | Eaton’s global hydraulics business acquired by Danfoss |
| 2022 | Indian company renamed Danfoss Systems Limited |
| May 2025 | NCLT approved selective capital reduction |
| May 2025 | ROC registered the capital reduction |
| 2026 | Converted into Danfoss Systems Private Limited |
The historical connection to Eaton is therefore genuine, but Eaton Fluid Power is now a legacy name rather than the current legal entity name.
Danfoss completed its global acquisition of Eaton’s hydraulics business in August 2021 for approximately US$3.3 billion. The transaction added approximately 10,000 employees and about US$1.8 billion of 2020 global sales to Danfoss Power Solutions.
3. Current Corporate Status – Most Important Point
The latest corporate records show:
- Current name: Danfoss Systems Private Limited
- CIN: U29120PN1965PTC015850
- Status: Active
- Company type: Private Limited
- Listing: Unlisted
- Authorised capital: ₹15.50 Cr
- Paid-up capital: approximately ₹6.80 Cr
- Registered office: Pimpri, Pune
Current corporate records also list Eaton Fluid Power Limited and Danfoss Systems Limited as previous names.
This is important because many unlisted-share websites continue to display the historical “Eaton Fluid” name and older share-market information.
4. Capital Reduction – What Happened to Outside Shareholders?
The company proposed a selective reduction of capital specifically involving non-promoter shareholders because the company was not listed on a stock exchange and those shareholders had limited liquidity.
The NCLT-approved transaction cancelled 1,66,778 equity shares and paid the affected shareholders ₹872.99 per share.
The approved reduction changed the capital structure from:
69,64,267 equity shares → 67,97,489 equity shares
The resulting paid-up capital was:
67,97,489 shares × ₹10 = ₹6.80 Cr approximately.
Prior to the reduction, Danfoss Fluid Power Private Limited owned 6,797,489 shares, representing 97.61% of the company.
Because the cancelled shares were the non-promoter shares, the post-reduction structure effectively leaves Danfoss Fluid Power with the entire equity ownership.
Investor implication
This is substantially different from a normal unlisted company where a meaningful public/non-promoter shareholder base remains.
Therefore, any current OTC quotation found on unlisted-share websites should be treated with extreme caution.
5. Business Model
Danfoss Systems operates in the hydraulic and fluid-power engineering industry.
Its activities include:
- Hydraulic products
- Hydraulic systems
- Hydraulic machinery
- Pumps
- Valves
- Motors
- Power units
- Engineered hydraulic systems
- Industrial and mobile hydraulic applications
- Design and engineering
- Manufacturing and assembly
- Sales and marketing
Danfoss Power Solutions describes its broader portfolio as including hydraulic pumps, valves, motors, cylinders, hydraulic power units, electronic controls, hoses and fittings, software and electrification solutions.
Danfoss Power Solutions – Official Business Page
6. Industry Position
Hydraulics is a critical enabling technology for machinery requiring:
- High force
- Precise movement
- Heavy-duty operation
- Compact power transmission
- High reliability
Applications include:
- Construction equipment
- Agriculture
- Mining
- Material handling
- Industrial machinery
- Transportation
- Marine
- Infrastructure equipment
- Off-highway vehicles
Danfoss Power Solutions states that its products and technologies are used across mobile and industrial machinery and that it is developing solutions around hydraulics, electrification and software.
7. Strategic Advantage of the Danfoss Relationship
One of the strongest qualitative aspects of the company is its connection with the global Danfoss group.
Danfoss describes the combination of its Power Solutions business and Eaton Hydraulics as creating a broader portfolio of mobile and industrial hydraulics and fluid-conveyance solutions.
This provides access to:
- Global technology
- Engineering expertise
- Product development
- International customers
- Global procurement
- Technology platforms
- Danfoss distribution network
- Application development capabilities
This is not simply a standalone Indian hydraulic manufacturer; it operates within a much larger global industrial technology ecosystem.
8. FY2025 Financial Performance
The latest audited annual report available for the company covers FY2024-25.
Profit & Loss
| Particulars | FY2025 | FY2024 |
|---|---|---|
| Revenue from Operations | ₹519.50 Cr | ₹517.14 Cr |
| Other Income | ₹1.52 Cr | ₹6.05 Cr |
| Total Income | ₹521.01 Cr | ₹523.19 Cr |
| PBT | ₹5.82 Cr | ₹29.08 Cr |
| PAT | ₹6.27 Cr | ₹21.64 Cr |
| EPS | ₹9.01 | ₹31.09 |
Source: audited Danfoss Systems FY2024-25 financial statements.
Revenue Growth
Revenue remained broadly stable:
₹517.14 Cr → ₹519.50 Cr
This represents only around 0.5% growth.
However, profitability declined substantially.
PAT:
₹21.64 Cr → ₹6.27 Cr
This represents a decline of approximately 71%.
The company’s own ratio analysis attributes the profitability decline primarily to higher corporate support charges, while also noting that increased net borrowings adversely affected the financial ratios.
9. EBITDA & Operating Margin
Based on the reported profit before finance costs and tax plus depreciation:
Approximate FY2025 EBITDA = ₹22.67 Cr
Approximate EBITDA margin:
₹22.67 Cr / ₹519.50 Cr ≈ 4.4%
This is materially lower than the previous year’s operating profitability.
The reported FY2025 profit before finance costs and tax was ₹11.52 Cr versus ₹34.71 Cr in FY2024.
10. Why Did Profit Fall So Sharply?
This is one of the most important areas of the report.
Corporate support charges increased from approximately:
₹25.08 Cr → ₹62.57 Cr
The annual report specifically identifies higher corporate support charges as a major reason for the decline in profitability.
At the same time:
- Royalty expense was ₹9.34 Cr
- Finance costs were ₹5.69 Cr
- Freight/packaging/forwarding expenses increased
- Working capital requirements increased
- Borrowings increased substantially
The company also recorded a ₹10.95 Cr reversal of technology royalty charges during FY2025 to align segment margins with local transfer-pricing requirements.
This makes FY2025 earnings particularly important to analyse rather than simply extrapolating FY2024 EPS.
11. Balance Sheet Analysis
FY2025
| Particulars | FY2025 |
|---|---|
| Total Assets | ₹378.95 Cr |
| Total Equity | ₹112.81 Cr |
| Borrowings | ₹121.72 Cr |
| Cash & Cash Equivalents | ₹1.02 Cr |
| Net Debt | ₹120.70 Cr |
| Trade Receivables | ₹114.38 Cr |
The company reported a significant increase in borrowings from ₹35.07 Cr in FY2024 to ₹121.72 Cr in FY2025. Net debt increased to approximately ₹120.70 Cr.
Debt-to-Equity
Reported debt-equity ratio:
1.10x
versus:
0.35x in FY2024
The increase is substantial and needs to be considered when evaluating any valuation.
12. Working Capital
Trade receivables increased to:
₹114.38 Cr
against:
₹89.46 Cr in FY2024.
The company also had inventory-related cash requirements, and its FY2025 cash-flow statement shows a significant working-capital outflow.
The receivable profile is not necessarily alarming by itself because the company operates in industrial B2B markets, but it becomes more relevant when combined with:
- Higher borrowings
- Lower profitability
- Negative operating cash flow
13. Cash Flow Analysis
This is arguably the weakest part of the FY2025 financial profile.
Cash Flow from Operations
FY2025:
–₹50.69 Cr
FY2024:
+₹46.06 Cr
Therefore, operating cash flow swung by almost ₹97 Cr year-on-year.
Investing Cash Flow
FY2025:
–₹28.86 Cr
The company invested approximately ₹29.85 Cr in property, plant and equipment and intangible assets.
Financing Cash Flow
FY2025:
+₹80.10 Cr
This was mainly supported by additional borrowings from related parties.
The result was that cash and cash equivalents increased only modestly to approximately ₹10.15 million, despite significant financing inflows.
Cash-flow interpretation
The FY2025 numbers indicate that the company was funding substantial working-capital and investment requirements through financing rather than internally generated operating cash.
This deserves close monitoring.
14. Land Transaction – Important Asset Development
An interesting development occurred after FY2025.
The company had classified its Pimpri factory land/building/road as assets held for sale, with net book value of approximately ₹10.83 Cr.
Subsequently, the company entered into a land-exchange arrangement involving its Pimpri factory land and a 177,400-square-metre parcel at Talegaon, Pune.
The exchange deed was executed on April 25, 2025, for consideration of approximately ₹186.30 Cr, with the Pimpri property subsequently taken back on lease.
This is strategically relevant because Danfoss simultaneously announced its major Talegaon expansion project.
15. New Talegaon Manufacturing Campus
In March 2025, Danfoss announced a more than €100 million investment in a new greenfield campus at Talegaon, Pune.
The planned facility:
- Covers approximately 27,000 square metres
- Is expected to more than double Danfoss Power Solutions’ manufacturing footprint in India
- Includes an Application Development Center
- Is designed to increase production capacity
- Supports pumps, motors, cylinders and valves
- Is intended to support Indian and global markets
Danfoss expected construction completion in the second half of 2026.
Danfoss Talegaon Investment Announcement
This is an important long-term industry development, although investors should not automatically assume that the entire Danfoss investment translates into the standalone earnings of Danfoss Systems Private Limited.
16. Export Exposure
FY2025 revenue from customers was approximately:
India: ₹402.17 Cr
Outside India: ₹114.24 Cr
Therefore, roughly 22% of customer revenue came from outside India.
This provides some geographic diversification but also introduces:
- Foreign exchange exposure
- Global industrial-cycle exposure
- International supply-chain exposure
17. Related-Party Transactions
The company has substantial transactions with other Danfoss group companies.
FY2025 included significant:
- Purchases of raw materials and traded goods
- Corporate support charges
- Royalty
- Related-party borrowings
- Sales to Danfoss group companies
For example, corporate support charges were ₹62.57 Cr and related-party current borrowings at year-end were significant.
This is understandable within a multinational group structure, but it is important for investors because standalone profitability can be affected by group-level:
- Royalties
- Support charges
- Procurement arrangements
- Transfer pricing
- Financing arrangements
18. Management / Governance
The FY2025 annual report lists directors including:
- Ravichandran Purushothaman
- Torben Jessen Christensen
- Anders Stahlschmidt
- Binu Antony Kuttickatt
- Prajakta Sangoram
- Akshay Bhalchandra Purandare
The statutory auditor is Price Waterhouse Chartered Accountants LLP.
19. Current Ownership
Before the capital reduction, Danfoss Fluid Power Private Limited held approximately:
97.61%
After the selective cancellation of the non-promoter shares, the company’s paid-up equity capital became 67,97,489 shares, matching the number previously held by Danfoss Fluid Power.
This means the company effectively became a wholly owned Danfoss entity.
20. Current Unlisted Share Price
Several unlisted-share platforms continue to display historical Eaton Fluid Power quotations.
For example, one platform currently shows approximately ₹443.60, while another shows approximately ₹544.50. These numbers are materially different from each other and should not be interpreted as an exchange-traded market price.
More importantly, these quotations are difficult to reconcile with the company’s current corporate structure because:
- The non-promoter shares were cancelled.
- The company became privately held.
- The legal entity changed to Danfoss Systems Private Limited.
- The historical share count and current ownership structure changed.
- The company is not listed on NSE/BSE.
Therefore:
No reliable current OTC market price should be presented as the current fair market price of Eaton Fluid Power.
The ₹872.99 per share paid under the 2025 capital reduction was a transaction-specific valuation determined for the cancelled non-promoter shares and should not be treated as today’s fair value.
21. Valuation Perspective
Using FY2025 EPS of approximately:
₹9.01/share
a hypothetical valuation at different P/E multiples would be:
| P/E Multiple | Illustrative Value |
|---|---|
| 10x | ₹90 |
| 15x | ₹135 |
| 20x | ₹180 |
| 25x | ₹225 |
| 30x | ₹270 |
| 40x | ₹360 |
| 50x | ₹451 |
| 60x | ₹541 |
These are scenario calculations only, not price targets.
They illustrate why using older unlisted quotations without adjusting for FY2025 earnings can produce misleading valuation conclusions.
22. Book Value Perspective
FY2025 equity was approximately:
₹112.81 Cr
against roughly 69.64 lakh shares before the capital reduction.
This translates to a historical FY2025 book value of approximately:
₹162/share
However, the post-capital-reduction share count and subsequent private-company structure mean historical P/B calculations based on publicly quoted “Eaton Fluid” prices should be treated cautiously.
23. Key Growth Drivers
1. Indian industrialisation
Growth in:
- Construction
- Infrastructure
- Agriculture
- Mining
- Material handling
- Industrial automation
can support long-term demand for hydraulic equipment.
2. Danfoss technology
Danfoss Power Solutions continues to invest in hydraulics, electrification and digital technologies.
3. Local manufacturing
The Talegaon investment represents a major expansion of Danfoss’s Indian manufacturing footprint.
4. Export potential
Approximately ₹114 Cr of FY2025 customer revenue came from outside India.
5. Engineering ecosystem
The broader Danfoss group provides access to global engineering, R&D, product platforms and application-development capabilities.
24. Key Risks
1. Corporate restructuring risk
The company has undergone multiple name, ownership and legal-form changes.
2. Illiquidity
The historical Eaton Fluid Power shares were already highly illiquid; the company is now a private company with a much more concentrated ownership structure.
3. Profitability compression
PAT fell from ₹21.64 Cr to ₹6.27 Cr in FY2025.
4. Negative operating cash flow
CFO was –₹50.69 Cr in FY2025.
5. Higher leverage
Net debt increased to approximately ₹120.70 Cr and reported gearing rose sharply.
6. Related-party dependence
A substantial portion of financing and expenses involve Danfoss group companies.
7. Valuation uncertainty
There is no exchange-traded price and no reliable continuous price discovery.
8. No conventional IPO thesis
The conversion into a private company significantly changes the probability framework around any traditional “pre-IPO” thesis.
25. Investment Due-Diligence Checklist
Before considering any transaction described as “Eaton Fluid Power shares”, an investor should verify:
- Current legal name on the share certificate
- Current ISIN
- Current demat balance
- Whether the shares are still legally transferable
- Whether the seller is the registered shareholder
- Current share certificate / corporate action history
- Capital reduction impact
- Current Articles of Association
- Current ownership
- Board approval requirements for transfer
- Whether the quoted price relates to the current security
- Whether the proposed transaction is actually a transfer of shares in Danfoss Systems Private Limited
This is particularly important because websites may continue using the historical “Eaton Fluid” trading name.
26. Overall Assessment
Eaton Fluid Power has a strong industrial heritage and is connected to a globally established hydraulics platform through Danfoss. The broader Danfoss Power Solutions business is investing heavily in India’s manufacturing and engineering ecosystem, including the major Talegaon project.
However, the investment case today is fundamentally different from the historical Eaton Fluid Power unlisted-share story.
The most important developments are:
Eaton Fluid Power → Danfoss Systems → Danfoss Systems Private Limited
and
Non-promoter shares cancelled → Danfoss becomes effectively 100% owner.
Financially, FY2025 showed:
- Stable revenue
- Significant PAT decline
- Lower operating profitability
- Negative operating cash flow
- Higher working-capital requirements
- Substantially higher borrowings
- Higher leverage
Therefore, the company remains strategically interesting as a Danfoss-owned industrial hydraulics manufacturing platform, but historical unlisted-share prices should not be used mechanically to establish a current investment valuation.
Important Investor Note
If someone is currently offering “Eaton Fluid Power unlisted shares”, the first question should not be “What is the price?”
The first question should be:
“What exact current security is being transferred, under what current legal entity, and who is the registered shareholder?”
That verification is essential given the 2025 capital reduction and 2026 conversion into a private company.
27. Official & Research Links
Company / Group
Danfoss Power Solutions – Official Business Page
Danfoss Power Solutions India / Customer Support
Official FY2024-25 Financial Statements
Danfoss Systems FY2024-25 Annual Report / Financial Statements
Corporate Status
Current Danfoss Systems Private Limited Corporate Record
Historical Eaton Hydraulics Acquisition
Danfoss – Eaton Hydraulics Acquisition Announcement
Disclaimer
This report is prepared for research and informational purposes only. Unlisted and privately held securities involve substantially higher liquidity, valuation, transferability and information risks than exchange-listed securities. Historical OTC prices are not equivalent to NSE/BSE market prices. The valuation scenarios presented above are illustrative calculations and are not price targets or investment recommendations. Investors should independently verify the current legal status, ISIN, ownership, transferability and documentation of any security before entering into a transaction.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
