
1. Company Overview
Imagine Marketing Limited, popularly known through its flagship consumer brand boAt, is an Indian consumer-electronics company focused primarily on personal audio, wearables and connected lifestyle products.
The boAt brand was launched in 2015 and has expanded from audio products into smartwatches, home audio, charging solutions, mobile accessories, gaming, projectors, grooming products and other consumer-technology categories.
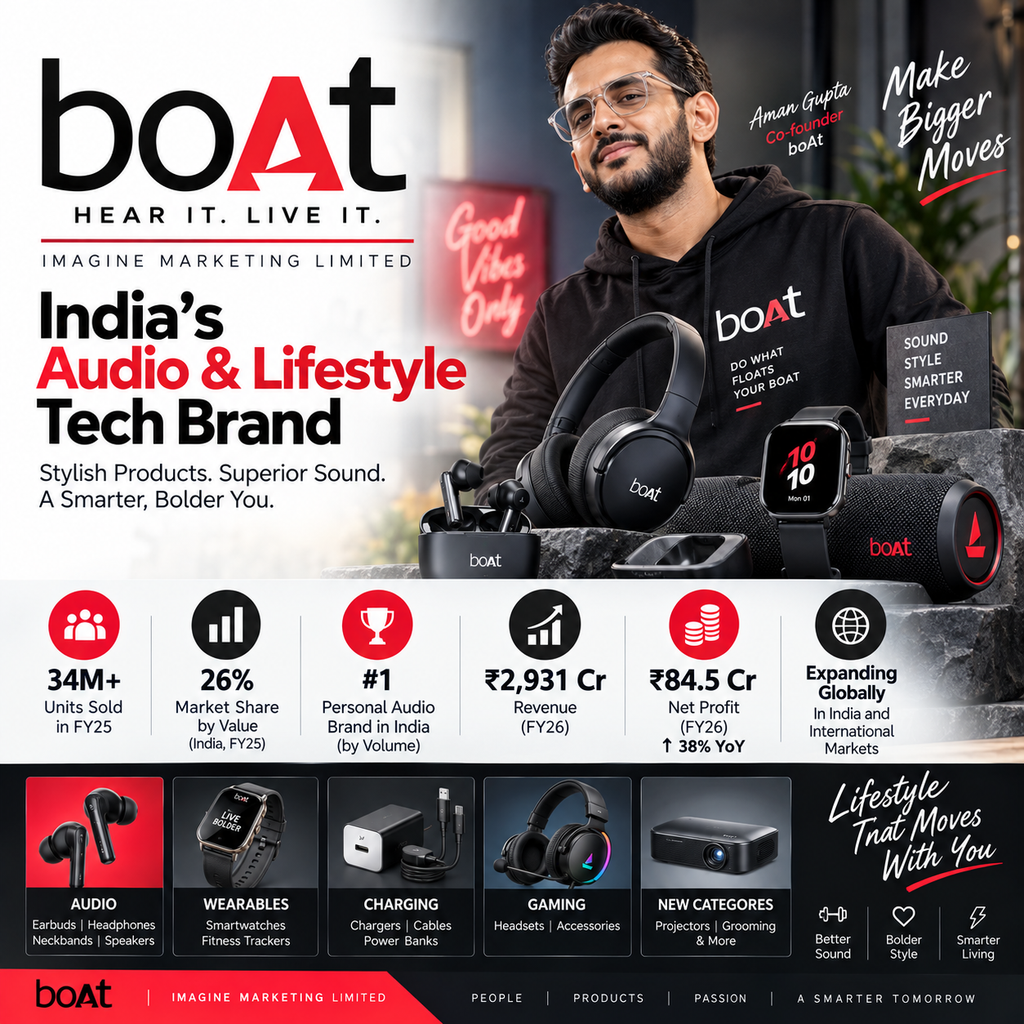
According to the company’s Updated Draft Red Herring Prospectus, boAt was the largest branded personal-audio brand in India in FY2025, with approximately 26% market share by value and 34% by volume. It had also maintained the #1 position in India’s branded personal-audio market by volume from FY2020 through FY2025.
The company is currently unlisted, with an IPO process underway based on its previously filed and updated offer documents.
2. Company Details
| Particular | Details |
|---|---|
| Company | Imagine Marketing Limited |
| Brand | boAt |
| CIN | U52300MH2013PLC249758 |
| Incorporated | 2013 |
| Brand Launched | 2015 |
| Registered / Corporate Office | Mumbai, Maharashtra |
| Industry | Consumer Electronics / Consumer Technology |
| Core Categories | Audio, Wearables, Charging & Accessories |
| Current Status | Unlisted |
| Proposed Listing | NSE & BSE |
| Face Value | ₹1 per Equity Share |
| IPO Process | DRHP / Updated DRHP filed |
| Promoters | Sameer Ashok Mehta, Aman Gupta & South Lake Investment Ltd. |
The company’s official investor-relations page provides its financial statements, annual returns, corporate-governance information and IPO documents.
3. Business Model
boAt operates primarily as a consumer technology and lifestyle brand.
Its products are sold through:
- E-commerce marketplaces
- boAt’s own website
- Offline retail
- Multi-brand electronics stores
- Modern trade
- Other distribution channels
The company follows a largely asset-light brand and product model, with manufacturing substantially supported by third-party manufacturing partners.
This allows boAt to focus heavily on:
- Product design
- Brand building
- Marketing
- Distribution
- Product innovation
- Customer acquisition
- Supply-chain management
4. Major Product Categories
1. Personal Audio
This remains the core business.
Products include:
- True wireless earbuds
- Wireless headphones
- Neckbands
- Wired earphones
- Bluetooth speakers
- Soundbars
- Home audio
2. Wearables
The company offers:
- Smartwatches
- Fitness trackers
- Connected devices
Wearables had previously been a major growth category but faced substantial industry-wide pressure from declining average selling prices and intense competition.
Importantly, the wearables segment returned to profitability in FY2026.
3. Charging & Mobile Accessories
This includes:
- Chargers
- Cables
- Power banks
- Mobile accessories
4. Gaming
The company has expanded into gaming-oriented products and accessories.
5. New Consumer-Tech Categories
boAt has increasingly entered categories such as:
- Projectors
- Grooming
- Dashcams
- Additional charging solutions
- Other smart consumer devices
The company has stated that these newer categories are intended to become additional growth and profit pools.
5. Brand Strength
The company’s biggest competitive asset is the boAt brand.
The DRHP states that boAt was:
- #1 in India’s branded personal audio market by volume in each year from FY2020–FY2025
- Approximately 26% market share by value in FY2025
- Approximately 34% market share by volume in FY2025
- Among the world’s largest branded personal-audio companies by volume
The company sold more than 34 million units during FY2025, demonstrating the scale of its distribution and consumer reach.
6. FY2026 Financial Performance
The latest FY2026 results show a mixed but improving financial picture.
| ₹ Crore | FY2025 | FY2026 | Change |
|---|---|---|---|
| Revenue from Operations | ~3,073 | ~2,931 | ↓ ~4.6% |
| EBITDA | ~100 | ~117.5 | ↑ ~17.6% |
| PAT | 61.1 | 84.5 | ↑ ~38% |
| PBT | 74.7 | 114.3 | ↑ ~53% |
| Cash Reserves | — | ~₹397 Cr | — |
| Bank Debt | — | Zero | — |
boAt reported FY2026 revenue from operations of approximately ₹2,931 Cr and PAT of ₹84.5 Cr, up 38% from ₹61.1 Cr in FY2025.
Important accounting point
The audited standalone financial statements of Imagine Marketing Limited report FY2026 revenue from operations of ₹2,928.08 Cr and profit for the year of ₹64.22 Cr before the relevant group/consolidation presentation. The ₹2,931 Cr revenue and ₹84.5 Cr PAT figures are the FY2026 company-reported figures used in public reporting on the boAt business.
The official audited statements confirm that the standalone financial statements were audited for the year ended March 31, 2026.
7. Profitability Improvement
FY2026 represented an important improvement in profitability.
According to management commentary:
- PAT increased 38%
- PBT increased approximately 53%
- ROCE improved
- Finance costs declined substantially
- Warranty costs declined
- Inventory was reduced
- Wearables returned to profitability
- Other categories became more meaningful
The company ended FY2026 with approximately ₹397 Cr of cash reserves and zero bank debt, according to management commentary.
8. Wearables Turnaround
Wearables were previously one of boAt’s biggest challenges.
The segment had suffered from:
- Falling average selling prices
- Intense competition
- Slower replacement demand
- Market saturation
However, FY2026 saw a significant improvement.
Wearables Segment
FY2025: approximately ₹54 Cr loss
FY2026: approximately ₹7 Cr profit
This turnaround contributed to the improvement in overall profitability.
9. Other Business Categories
The company’s “Other” category, which includes products such as:
- Charging solutions
- Cables
- Gaming
- Other consumer-tech products
also improved significantly.
Segment profit increased to approximately ₹46 Cr in FY2026, compared with approximately ₹14 Cr in FY2025.
This is important because boAt is attempting to reduce its dependence on the traditional audio category by building multiple consumer-electronics businesses.
10. Audio Remains the Core Business
Despite expansion into multiple categories, audio remains the company’s most important business.
The FY2025 DRHP indicated that audio accounted for more than 79% of revenue.
Major audio products include:
- Airdopes
- Wireless headphones
- Neckbands
- Speakers
- Soundbars
- Home audio
This provides boAt with a strong category position but also creates category-concentration risk.
11. International Expansion
boAt is increasingly looking beyond India.
FY2026 international revenue increased to approximately:
₹45 Cr
from approximately:
₹20 Cr in FY2025
This represents more than a doubling of international revenue, although international business remains relatively small compared with the company’s Indian operations.
The company’s stated strategy is to build international markets as one of the future growth engines for “boAt 2.0.”
12. Manufacturing & Supply Chain
boAt primarily follows an outsourced manufacturing model.
This provides several advantages:
- Lower fixed manufacturing investment
- Flexible production capacity
- Ability to scale products quickly
- Access to specialized electronics manufacturers
- Faster product refresh cycles
However, it also creates dependence on third-party manufacturers and the broader electronics supply chain.
Risks include:
- Component shortages
- Import dependence
- Currency movements
- Shipping costs
- Geopolitical disruptions
- Quality-control issues
13. Distribution Strategy
boAt has developed a strong omnichannel distribution ecosystem.
Its channels include:
Online
- Amazon
- Flipkart
- boAt’s own website
- Other e-commerce platforms
Offline
- Electronics retailers
- Multi-brand stores
- Modern retail
- Distribution partners
The company historically had significant dependence on major online marketplaces, making platform economics and changes in marketplace policies an important consideration for investors.
14. Industry Opportunity
India’s consumer-electronics market is supported by:
- Rising smartphone penetration
- Increasing disposable income
- Digital lifestyles
- Young consumers
- E-commerce penetration
- Replacement demand
- Increasing adoption of wireless audio
- Smart-device adoption
The personal-audio market has particularly benefited from the transition from wired to wireless devices.
Emerging categories such as:
- Smart home
- Gaming
- Projectors
- Wearables
- Charging
- Personal grooming
provide additional potential addressable markets.
15. Competitive Advantages
1. Strong Indian Consumer Brand
boAt has built significant brand awareness among younger Indian consumers.
2. Leadership in Personal Audio
Its market position in personal audio remains its biggest competitive strength.
3. Large Product Portfolio
The company has expanded from a single-category audio business into a broader consumer-tech platform.
4. Digital-First DNA
The company built its brand through digital marketing and e-commerce, enabling relatively rapid product launches and customer acquisition.
5. Strong Distribution
Its presence across online and offline channels provides broad market access.
6. Product Innovation
Frequent launches allow the company to respond quickly to changing consumer preferences.
7. Improving Balance Sheet
The FY2026 reported cash position and zero bank debt are significant improvements compared with the company’s earlier leveraged position.
16. Major Investors & Promoters
The company’s IPO documents identify:
- Sameer Ashok Mehta
- Aman Gupta
- South Lake Investment Ltd.
as promoters.
The company has also attracted major institutional investors over its private-market journey, including:
- Warburg Pincus / South Lake
- Fireside Ventures
- Qualcomm Ventures
- Peak XV / Sequoia ecosystem
- Other institutional investors
17. IPO History
Imagine Marketing originally filed for an IPO in January 2022.
The original proposed issue consisted of:
- Fresh issue: ₹900 Cr
- OFS: ₹1,100 Cr
- Total: ₹2,000 Cr
SEBI’s records show that the 2022 draft offer document subsequently received observations but the original IPO process was withdrawn.
18. Updated IPO Proposal
The company subsequently returned to the IPO market with an updated offer document.
The October 2025 Updated DRHP proposed:
| IPO Component | Proposed Size |
|---|---|
| Fresh Issue | Up to ₹500 Cr |
| Offer for Sale | Up to ₹1,000 Cr |
| Total IPO | Up to ₹1,500 Cr |
| Pre-IPO Placement | Up to ₹100 Cr |
| Face Value | ₹1 |
| Proposed Listing | NSE & BSE |
The proposed fresh issue was intended primarily for:
- Working capital
- Brand building and marketing
- General corporate purposes
- Potential acquisitions
The updated DRHP specifically disclosed the ₹500 Cr fresh issue and ₹1,000 Cr OFS structure.
19. IPO Status – September 2026
As of September 2026, Imagine Marketing Limited remains unlisted.
The company’s official investor-relations page continues to host the Updated DRHP-I and other IPO documents.
No final IPO price band, opening date or listing date has been publicly confirmed in the latest sources reviewed.
Therefore, investors should not treat earlier reported IPO valuations or unlisted-market prices as the final IPO valuation.
20. FY2026 Balance Sheet
The audited FY2026 standalone financial statements show:
| Particular | FY2026 |
|---|---|
| Revenue from Operations | ₹2,928.08 Cr |
| Profit for the Year | ₹64.22 Cr |
| Total Assets | ₹1,659.95 Cr |
| Total Liabilities | ₹1,120.78 Cr |
| Other Equity | ₹616.48 Cr |
| Working-Capital Bank Borrowings | Nil at March 31, 2026 |
The company also reported that finance costs fell significantly from the previous year.
21. Key Growth Drivers
1. Audio Leadership
Maintaining leadership in personal audio remains the core growth engine.
2. New Categories
Projectors, grooming, charging, gaming and other consumer-tech products could diversify revenue.
3. Wearables Recovery
The return of wearables to profitability could improve the overall product mix.
4. International Expansion
International revenue more than doubled in FY2026, although from a relatively small base.
5. Operating Efficiency
Lower finance and warranty costs, improved procurement and inventory discipline have supported profitability.
6. Brand Strength
A strong consumer brand can potentially support premiumisation and repeat purchases.
7. E-commerce Growth
India’s expanding online consumer-electronics ecosystem remains supportive of the company’s digital-first distribution model.
22. Key Risks
1. Revenue Decline
FY2026 revenue declined approximately 4.6% despite the improvement in profitability. This makes future topline growth an important monitorable.
2. Audio Concentration
Audio continues to account for the majority of revenue.
3. Wearables Competition
The wearables market remains highly competitive and price-sensitive.
4. Low Margins
Even after improvement, the company’s profitability margins remain relatively modest for a consumer brand.
5. E-commerce Dependence
Large online platforms remain important distribution channels.
6. Product Obsolescence
Consumer electronics have short product cycles. Products can quickly become outdated.
7. Inventory Risk
Rapid product launches and changing consumer preferences can result in inventory obsolescence.
8. Imported Components
Currency movements and global electronics supply chains can influence product costs.
9. Competition
boAt competes with:
- Noise
- Boult
- JBL
- Sony
- Samsung
- Xiaomi
- Realme
- OnePlus
- Apple
- Other domestic and international brands
10. Valuation Risk
The final IPO valuation is critical.
A strong brand does not automatically translate into an attractive investment if the entry valuation is high relative to sustainable earnings.
23. Unlisted Investment Perspective
boAt represents a differentiated Indian consumer-tech opportunity because of its combination of:
- Strong brand recognition
- Leadership in personal audio
- Large consumer base
- Digital-first distribution
- Multiple product categories
- Improving profitability
- Stronger balance sheet
- International expansion plans
- Potential IPO catalyst
The FY2026 numbers show an important shift:
Revenue: declined
Profitability: improved
Wearables: turned profitable
Other categories: became more meaningful
Cash: strengthened
Bank debt: reported at zero
The key question for an unlisted investor is therefore whether boAt can transition from a profit-recovery story into a sustainable growth story.
The company’s ability to grow newer categories without sacrificing margins, maintain audio leadership and expand internationally will be important factors to monitor.
24. Company Snapshot
| Parameter | Imagine Marketing Limited |
|---|---|
| Brand | boAt |
| Sector | Consumer Electronics |
| Founded | 2013 |
| boAt Brand Launched | 2015 |
| FY26 Revenue | ~₹2,931 Cr |
| FY26 PAT | ₹84.5 Cr |
| FY26 PBT | ₹114.3 Cr |
| FY26 EBITDA | ~₹117.5 Cr |
| FY26 International Revenue | ~₹45 Cr |
| FY26 Wearables Segment | Profitable |
| FY26 Cash Reserves | ~₹397 Cr |
| Bank Debt | Zero reported |
| Core Category | Personal Audio |
| FY25 Audio Market Share | ~26% value / ~34% volume |
| Promoters | Sameer Mehta, Aman Gupta & South Lake Investment |
| Current Status | Unlisted |
| Proposed IPO | ₹1,500 Cr |
| Fresh Issue | Up to ₹500 Cr |
| OFS | Up to ₹1,000 Cr |
| Proposed Listing | NSE & BSE |
| IPO Price Band | Not announced |
| IPO Date | Not announced |
25. Important Links
Official boAt Website:
boAt – Official Website
Imagine Marketing Investor Relations:
Imagine Marketing – Investor Relations
Imagine Marketing FY2026 Audited Financial Statements:
FY2026 Audited Financial Statements
Imagine Marketing IPO / Updated DRHP:
Updated Draft Red Herring Prospectus-I
boAt FY2026 Results:
boAt FY2026 Financial Results – Moneycontrol
boAt on UnlistedCart:
boAt / Imagine Marketing Limited – UnlistedCart
26. Disclaimer
This report is prepared for informational and educational purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Imagine Marketing Limited is currently unlisted. Its proposed IPO structure, issue size, price band, IPO dates, valuation and other terms may change before the final offer document.
Financial information has been compiled from the company’s audited financial statements, IPO documents, company disclosures and reputable secondary sources. Where FY2026 figures differ between standalone audited statements and company-reported business figures, the distinction has been identified rather than treating the numbers as interchangeable.
Investors should independently verify the latest financial statements, regulatory filings, valuation and transaction documents before making any investment decision.
Unlisted and pre-IPO investments involve liquidity risk, valuation risk, regulatory risk and limited price discovery. Past financial performance does not guarantee future performance.
For more such unlisted stocks visit:
UnlistedCart – Unlisted Shares
