
1. Company Overview
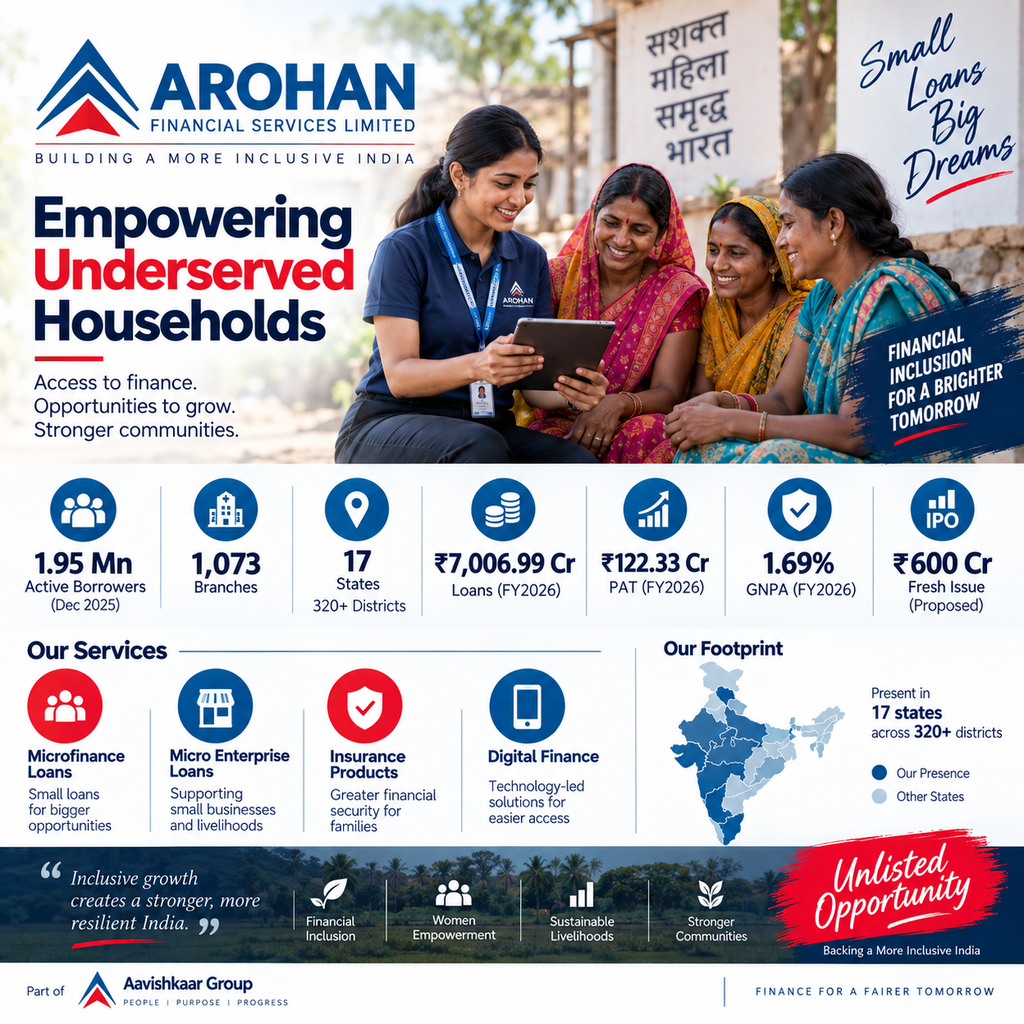
Arohan Financial Services Limited (AFSL) is a technology-enabled Non-Banking Financial Company – Microfinance Institution (NBFC-MFI) focused on providing financial services to underserved and underbanked households, particularly in rural and semi-urban India.
The company commenced its microfinance operations in 2006 and is part of the Aavishkaar Group, an impact-focused investment and financial-services ecosystem.
Arohan primarily provides income-generating loans to low-income households through its Joint Liability Group (JLG) model, with women forming the majority of its customer base. It also offers micro-enterprise financing, insurance and selected cross-sell products.
As of December 31, 2025, Arohan had ₹6,308.41 Cr of AUM, 1.95 million active borrowers, 1,073 branches across 17 states and 320 districts.
2. Company Details
| Particular | Details |
|---|---|
| Company | Arohan Financial Services Limited |
| CIN | U74140WB1991PLC053189 |
| Incorporated | 1991 |
| Microfinance Operations Started | 2006 |
| Registered Office | Kolkata, West Bengal |
| Industry | NBFC-MFI / Microfinance |
| Parent / Group | Aavishkaar Group |
| Current Status | Unlisted Public Company |
| RBI Status | NBFC-MFI |
| Core Market | Rural & Semi-Urban India |
| States | 17 |
| Districts | 320+ |
| Branches | 1,073 as of Dec. 2025 |
| Active Borrowers | 1.95 Mn as of Dec. 2025 |
| Proposed IPO | Fresh Issue + OFS |
| Proposed Fresh Issue | Up to ₹600 Cr |
| Proposed OFS | Up to 40,437,529 shares |
| Proposed Listing | NSE & BSE |
Arohan’s latest annual-report and investor-relations disclosures are available on its official website.
3. What Does Arohan Financial Services Do?
Arohan’s core business is providing small-ticket, income-generating loans to financially underserved customers.
The company predominantly uses a Joint Liability Group (JLG) model.
Under this model:
- Customers generally borrow as part of groups of women.
- Groups typically contain 3–5 borrowers.
- Members provide joint liability for the loans.
- Loans are primarily collateral-free.
- Repayments are generally collected through structured field and digital processes.
Arohan primarily targets households with annual household income of ₹3 lakh or less.
4. Major Products & Services
1. Microfinance Loans
The core business is microfinance lending to low-income households for income-generating activities and household requirements.
2. Micro Enterprise Loans
Arohan also provides financing to small entrepreneurs and micro businesses.
These loans can support:
- Small shops
- Trading businesses
- Livestock-related activities
- Small manufacturing
- Services
- Working capital requirements
3. Insurance Products
Arohan is registered as a Composite Corporate Agent with IRDAI, enabling it to offer insurance products alongside its financial-services ecosystem.
4. Cross-Sell Products
The company has historically offered selected household and consumer products through partner arrangements, including products such as:
- Inverter bulbs
- Consumer durables
- Kitchen appliances
- Bicycles
- Other household products
These initiatives are intended to improve customer access to relevant products while creating additional engagement with its borrower base.
5. Institutional Lending
Arohan also provides term loans to other microfinance institutions, adding an institutional-lending component to its overall business model.
5. Geographic Presence
Arohan has historically focused on India’s Low Income States and financially under-penetrated markets.
As of December 31, 2025:
- 17 states
- 320 districts
- 1,073 branches
- 1.95 million active borrowers
Approximately 76.82% of active customers were located in rural and semi-urban areas, while women represented approximately 93.57% of the customer base.
The company’s FY2025 network consisted of approximately 1,103 branches across 17 states and 323 districts.
6. AUM / Loan Portfolio
Arohan’s AUM experienced a significant contraction during FY2025 as the microfinance sector faced elevated credit stress and regulatory challenges.
| Period | AUM |
|---|---|
| FY2023 | ₹5,357.37 Cr |
| FY2024 | ₹7,112.04 Cr |
| FY2025 | ₹6,002.58 Cr |
| Dec. 2025 | ₹6,308.41 Cr |
The company recorded 5.10% AUM growth during the nine months ended December 2025 after the FY2025 contraction.
Management had indicated an objective of reaching approximately ₹7,000 Cr AUM by March 2026, and FY2026 loan assets on the balance sheet reached approximately ₹7,006.99 Cr.
7. FY2026 Financial Performance
Arohan’s FY2026 results showed a recovery in profitability compared with FY2025.
| ₹ Crore | FY2025 | FY2026 |
|---|---|---|
| Revenue from Operations | ~1,691.75 | 1,544.88 |
| Total Income | ~1,695.26 | 1,551.55 |
| Interest Income | 1,581.18 | 1,415.50 |
| Finance Costs | 631.96 | 524.59 |
| Impairment on Financial Instruments | 397.51 | 303.37 |
| Profit Before Tax | 138.09 | 163.41 |
| PAT | 109.69 | 122.33 |
| EPS | ₹7.20 | ₹8.02 |
FY2026 PAT increased approximately 11.5% to ₹122.33 Cr despite lower revenue from operations. Finance costs and impairment expenses both declined during the year.
8. FY2026 Balance Sheet
As of March 31, 2026:
| Particular | FY2026 |
|---|---|
| Total Assets | ₹8,219.94 Cr |
| Loans | ₹7,006.99 Cr |
| Investments | ₹535.71 Cr |
| Cash & Cash Equivalents | ₹331.47 Cr |
| Debt Securities | ₹160.13 Cr |
| Other Borrowings | ₹5,489.93 Cr |
| Subordinated Liabilities | ₹249.57 Cr |
| Equity | ~₹2,157.78 Cr |
The company therefore operates with a leveraged balance sheet, as is typical for an NBFC, making funding cost, asset quality and capital adequacy important monitorables.
9. Latest Quarterly Performance – Q1 FY2027
Arohan’s latest available financial results for the quarter ended June 30, 2026 show continued improvement in profitability.
| ₹ Crore | Q1 FY2027 |
|---|---|
| Revenue from Operations | ₹477.82 Cr |
| Total Income | ₹478.59 Cr |
| Finance Costs | ₹155.24 Cr |
| Impairment | ₹20.10 Cr |
| Profit Before Tax | ₹141.21 Cr |
| PAT | ₹105.14 Cr |
| EPS | ₹6.90 |
For comparison, Q1 FY2026 PAT was only ₹4.74 Cr. The sharp year-on-year improvement reflects significantly lower impairment costs and improved operating performance.
The June 2026 financial results were subject to limited review by the statutory auditor, with an unmodified conclusion.
10. Asset Quality
Asset quality is one of the most important factors for any microfinance institution.
Arohan’s reported metrics show a significant improvement in FY2026.
| Asset Quality | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Gross NPA | 1.67% | 2.85% | 1.69% |
| Net NPA | Nil | 0.53% | 0.39% |
| Credit Cost | 2.87% | 6.06% | 4.37% |
| Collection Efficiency | 108.85% | 103.92% | 108.67% |
The FY2026 improvement in GNPA and NNPA came after the asset-quality pressure experienced during FY2025.
11. Regulatory History
The Indian microfinance sector went through a difficult period during FY2025.
Arohan had faced regulatory restrictions relating to loan disbursement, following concerns around its lending processes and pricing practices.
The RBI subsequently lifted the restrictions in January 2025 after reviewing corrective actions and systems implemented by the company.
The episode remains relevant when evaluating Arohan because it highlights the importance of:
- Regulatory compliance
- Responsible lending
- Pricing discipline
- Customer protection
- Credit underwriting
- Collection practices
12. Capital Adequacy
Arohan maintains a substantial capital buffer.
According to the DRHP industry-research data:
| Capital Metric | FY2025 | 9M FY2026 |
|---|---|---|
| CRAR | 34.09% | 31.20% |
| Tier-I Capital | 31.82% | 30.58% |
| Tier-II Capital | 2.27% | 0.62% |
The capital adequacy ratio remains significantly above regulatory minimum requirements, although it declined from FY2025 levels as the balance sheet began recovering.
13. Funding Cost
Funding cost is a major driver of profitability for an NBFC-MFI.
Arohan’s average cost of borrowings improved significantly:
FY2025: 11.79%
9M FY2026: 7.76%
The reduction in funding cost helped offset some of the pressure from lower interest income.
Arohan also maintains relationships with institutional lenders and development-finance institutions.
FMO, for example, has disclosed financing support for Arohan and describes the investment as supporting inclusive growth and financial inclusion.
14. Technology & Digital Lending
Technology is an important component of Arohan’s operating model.
The company has developed and deployed technology across:
- Digital customer acquisition
- e-KYC
- Credit scoring
- Loan processing
- Collection monitoring
- Fraud management
- Audit management
- Employee monitoring
- Customer servicing
Arohan’s proprietary Nirnay credit-scoring model is designed to support lending decisions.
The company has also developed ArohanPrivilege Digital, a digital lending platform.
Digital collections increased over time, reaching 13.53% of collections in 9M FY2026, compared with 12.37% in FY2025 and 10.78% in FY2024.
15. Business Efficiency
Arohan has been working to improve operating efficiency as its portfolio recovers.
| Metric | FY2025 | 9M FY2026 |
|---|---|---|
| Operating Expenses / Avg. AUM | 8.05% | 6.50% |
| Cost-to-Income Ratio | 49.63% | 53.44% |
| Net Interest Margin | 13.10% | 9.86% |
| Average Cost of Borrowings | 11.79% | 7.76% |
The lower operating-expense-to-AUM ratio and borrowing cost are positive operating developments, although NIM remained under pressure.
16. Customer Base
Arohan’s business is heavily focused on women borrowers.
As of December 2025:
- Active customers: 1.95 million
- Women customers: 93.57%+
- Rural/semi-urban customers: 76.82%
- States: 17
- Districts: 320
- Branches: 1,073
The company’s lending model is designed around low-income households with limited access to formal financial services.
17. Competitive Position
Arohan is one of India’s established NBFC-MFIs.
According to the CARE industry research referenced in the IPO process, Arohan was:
- The second-largest NBFC-MFI in Eastern India by AUM
- The ninth-largest NBFC-MFI in India by AUM
as of December 31, 2025.
Its competitive position is supported by:
- Long operating history
- Large branch network
- Rural customer relationships
- Strong institutional investor base
- Technology-enabled underwriting
- Established collection infrastructure
- Aavishkaar Group association
18. Promoters & Shareholders
The DRHP identifies the following promoters:
- Aavishkaar Venture Management Services Private Limited
- Intellectual Capital Advisory Services Private Limited
- Vineet Chandra Rai
- Swati Rai
Arohan has a diversified institutional investor base.
Reported shareholders include:
| Shareholder | Approx. Holding |
|---|---|
| Teachers Insurance and Annuity Association of America | 12.09% |
| Aavishkaar Goodwell India Microfinance Development Company II | ~11.7% |
| Tano India Private Equity Fund II | 10.50% |
| Intellectual Capital Advisory Services | 10.37% |
| FMO | 9.90% |
| Maj Invest Financial Inclusion Fund II | 9.69% |
| Others | Balance |
The shareholding information is based on the latest publicly available company/IPO-related data and may change before the final prospectus.
19. Management
Manoj Kumar Nambiar
Managing Director
Manoj Kumar Nambiar has been associated with the microfinance and financial-services sector for more than three decades and is the current Managing Director of Arohan.
Vineet Chandra Rai
Founder, Aavishkaar Group / Non-Executive Promoter
Vineet Rai is the founder of the Aavishkaar Group and has been associated with Arohan’s development since its early years.
The management’s stated priorities include improving operating efficiency, strengthening risk management, expanding responsibly and building the capital base for future lending.
20. Industry Opportunity
India’s microfinance sector plays an important role in extending formal credit to households that may have limited access to conventional banking.
Long-term growth drivers include:
- Financial inclusion
- Rural consumption
- Women’s entrepreneurship
- Micro-enterprise financing
- Increasing formalisation of rural credit
- Digital lending
- Better credit-data availability
- Expansion of formal financial services
However, the industry remains sensitive to borrower indebtedness, local economic conditions, regulation and collection behaviour.
21. Growth Drivers
1. Recovery in Microfinance Cycle
Arohan’s FY2026 asset-quality improvement could support renewed portfolio growth.
2. Capital Infusion Through IPO
The proposed ₹600 Cr fresh issue can strengthen the capital base and support additional lending.
3. Rural & Semi-Urban Penetration
The company remains focused on financially underserved regions where formal-credit penetration is relatively lower.
4. Digital Transformation
Higher digital collections and technology-enabled underwriting can potentially improve productivity.
5. Lower Funding Cost
The reduction in average borrowing cost from 11.79% to 7.76% in the reported period can support margins if sustained.
6. Micro-Enterprise Lending
Expansion beyond traditional group microfinance could increase average ticket sizes and diversify the portfolio.
7. Insurance Cross-Selling
Insurance and other financial products provide opportunities to deepen relationships with existing borrowers.
22. Key Risks
1. Microfinance Credit Risk
Arohan primarily lends to low-income borrowers, making repayment behaviour sensitive to rural income, employment and local economic conditions.
2. Regulatory Risk
Microfinance is highly regulated. Changes in RBI regulations, state-level rules or borrower-protection requirements can affect operations.
3. Multiple Borrowing
Borrowers may have loans from several institutions. Excessive indebtedness can negatively affect portfolio quality.
4. Geographic Concentration
The top three states accounted for approximately 67.89% of AUM as of December 2025.
5. Funding Risk
The business relies substantially on external borrowings. Changes in interest rates or lender appetite can affect profitability.
6. Collection Risk
Collection efficiency can be affected by local economic disruptions, natural disasters, social issues or regulatory changes.
7. Margin Pressure
NIM declined to 9.86% in 9M FY2026 from 13.10% in FY2025.
8. Regulatory History
The company’s previous regulatory restrictions demonstrate the importance of maintaining strong compliance and responsible-lending practices.
9. Profit Volatility
Arohan’s PAT moved from approximately ₹314 Cr in FY2024 to ₹110 Cr in FY2025 before recovering to ₹122 Cr in FY2026.
23. IPO Details
Arohan filed its Draft Red Herring Prospectus with SEBI on May 15, 2026.
The proposed IPO comprises:
| IPO Component | Proposed Size |
|---|---|
| Fresh Issue | Up to ₹600 Cr |
| Offer for Sale | Up to 40,437,529 shares |
| Face Value | ₹10/share |
| Issue Type | Book Building |
| Proposed Listing | NSE & BSE |
| Price Band | Not announced |
| IPO Dates | Not announced |
The IPO is a combination of fresh capital and an offer for sale by existing shareholders.
24. Use of IPO Proceeds
The company proposes to use the ₹600 Cr fresh issue primarily to strengthen its capital base.
The stated purpose is:
Augmenting the capital base to meet future business requirements towards onward lending.
The balance, if any, is proposed to be used for general corporate purposes.
This means the fresh capital is intended to support future loan-book growth rather than primarily debt repayment.
25. Offer for Sale
The proposed OFS comprises up to:
40,437,529 equity shares
Existing investors are expected to use the IPO to partially monetise their holdings.
The proposed OFS includes participation from several institutional investors, including investors associated with the company’s long-term private-equity and development-finance shareholder base.
26. IPO Reservation
According to the DRHP-related disclosures:
| Investor Category | Reservation |
|---|---|
| QIB | Not more than 50% |
| NII | Not less than 15% |
| Retail | Not less than 35% |
| Employee Reservation | Proposed |
Final allocation will depend on the final offer document and applicable regulations.
27. IPO Status – September 2026
As of September 2026:
| Parameter | Status |
|---|---|
| Company | Arohan Financial Services Limited |
| Current Status | Unlisted |
| DRHP Filed | Yes |
| DRHP Date | May 15, 2026 |
| Fresh Issue | Up to ₹600 Cr |
| OFS | Up to 40.44 million shares |
| Proposed Listing | NSE & BSE |
| Price Band | Not announced |
| IPO Opening Date | Not announced |
| Listing Date | Not announced |
| Lead Managers | DAM Capital, Motilal Oswal Investment Advisors, SBI Capital Markets |
| Registrar | MUFG Intime India |
| Latest Financials | Q1 FY2027 available |
Arohan’s June 2026 financial results also confirm that the Board approved actions to pursue an IPO comprising a fresh issue and OFS and that the DRHP was filed with SEBI on May 15, 2026.
28. Unlisted Investment Perspective
Arohan represents an established financial-inclusion and microfinance platform with a long operating history and a large rural/semi-urban customer base.
Key factors to monitor include:
- ₹7,000 Cr+ loan assets around FY2026
- ₹122.33 Cr FY2026 PAT
- Q1 FY2027 PAT of ₹105.14 Cr
- GNPA improvement to 1.69% in FY2026
- NNPA of 0.39%
- CRAR of 31.20% in 9M FY2026
- 1.95 Mn active borrowers as of Dec. 2025
- 1,073 branches
- 17 states
- Strong institutional investor base
- Proposed ₹600 Cr fresh IPO
- IPO proceeds primarily for onward lending
The most important variables for an unlisted investor are entry valuation, book value, post-IPO valuation, asset quality, funding cost, credit cost, loan-book growth and sustainability of profitability.
The improvement in FY2026 asset quality and Q1 FY2027 profitability is significant, but the microfinance business remains inherently sensitive to regulatory and credit cycles.
29. Company Snapshot
| Parameter | Arohan Financial Services |
|---|---|
| Sector | NBFC-MFI |
| Started Microfinance Operations | 2006 |
| Group | Aavishkaar Group |
| FY2026 PAT | ₹122.33 Cr |
| FY2026 Revenue from Operations | ₹1,544.88 Cr |
| FY2026 Loans | ₹7,006.99 Cr |
| FY2026 GNPA | 1.69% |
| FY2026 NNPA | 0.39% |
| 9M FY2026 CRAR | 31.20% |
| Q1 FY2027 PAT | ₹105.14 Cr |
| Dec. 2025 AUM | ₹6,308.41 Cr |
| Active Borrowers | 1.95 Mn |
| Branches | 1,073 |
| States | 17 |
| Districts | 320 |
| Proposed Fresh Issue | ₹600 Cr |
| Proposed OFS | 40,437,529 shares |
| Proposed Listing | NSE & BSE |
| Current Status | Unlisted |
30. Important Links
Official Arohan Website:
Arohan Financial Services – Official Website
Arohan Investor Relations – Financials:
Arohan Financial Services – Financials
Arohan Annual Reports:
Arohan – Annual Reports
Arohan DRHP:
Arohan Financial Services – DRHP
Arohan IPO / Initial Disclosure:
Arohan – IPO Disclosure
Arohan – June 2026 Financial Results:
Arohan Q1 FY2027 Financial Results
Arohan – UnlistedCart:
Arohan Financial Services – UnlistedCart
31. Disclaimer
This report is prepared for informational and educational purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Arohan Financial Services Limited is currently unlisted. Its proposed IPO, issue size, price band, dates, valuation, OFS size and other terms may change before the final offer document.
Financial information has been compiled from the company’s DRHP, audited financial statements, limited-reviewed financial results, annual reports, regulatory disclosures and other publicly available sources.
Investors should independently review the latest SEBI filings, DRHP/RHP, financial statements, asset-quality disclosures and final IPO valuation before making any investment decision.
Unlisted and pre-IPO investments involve liquidity risk, valuation risk, regulatory risk, credit risk and limited price discovery. Past financial performance does not guarantee future performance.
For more such unlisted stocks visit:
UnlistedCart – Unlisted Shares
