
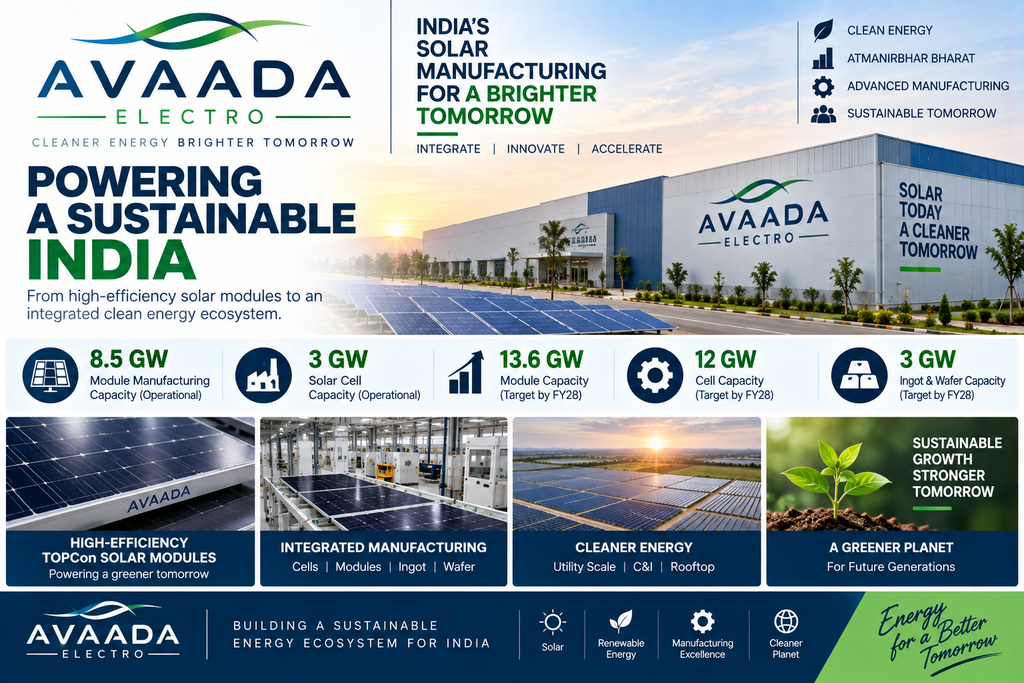
Solar PV Manufacturing | TOPCon Cells & Modules | Integrated Solar Manufacturing
Company: Avaada Electro Limited
Formerly: Avaada Electro Private Limited
CIN: U31905UP2021PLC145680
Incorporated: 27 April 2021
Converted to Public Limited: September 2025
Registered Office: Noida, Uttar Pradesh
Corporate Offices: Noida & Mumbai
Business: Solar PV cells and modules manufacturing
Promoter: Avaada Ventures Private Limited
Chairman & Whole-time Director: Vineet Mittal
Status: Unlisted public company / IPO-bound
Face Value: ₹5 per share
FY26 Revenue: ~₹5,303.5 Cr
FY26 PAT: ~₹888.7 Cr
Operational Module Capacity: 8.5 GW
Operational Cell Capacity: 3 GW
Proposed FY28 Module Capacity: 13.6 GW
Proposed FY28 Cell Capacity: 12 GW
Proposed Ingot/Wafer Capacity: 3 GW
1. Company Overview
Avaada Electro is the solar-manufacturing arm of the Avaada Group and focuses on high-efficiency solar PV cells and modules, particularly N-type TOPCon technology.
The company has rapidly scaled from a newly established manufacturing business into a large Indian solar manufacturer.
Its manufacturing strategy is increasingly vertically integrated:
Ingot/Wafer → Solar Cell → Solar Module
The company currently operates manufacturing facilities at Dadri, Uttar Pradesh and Butibori/Nagpur, Maharashtra. Its official website states that it has 8.5 GW of annual operational module capacity and is expanding its integrated cell and module manufacturing footprint.
Official Avaada Electro Website
2. What Does Avaada Electro Manufacture?
The company’s core products include:
Solar Modules
- N-type TOPCon modules
- Bifacial modules
- Glass-to-glass modules
- Utility-scale solar modules
- Commercial & industrial modules
- Rooftop solar modules
Its flagship products include the Enlume 720 Wp N-Type TOPCon G12 and Enlume 630 Wp N-Type TOPCon G12R modules.
Solar Cells
Avaada is also building a large N-type TOPCon solar-cell manufacturing platform.
Its first 3 GW of a planned 6 GW TOPCon cell facility at Nagpur became operational in July 2026, with the remaining capacity under ramp-up.
Future Manufacturing
The company plans to expand further into:
Solar Cells + Modules + Ingot + Wafer manufacturing
This is designed to reduce dependence on external suppliers and increase control over the solar manufacturing value chain.
3. Manufacturing Capacity
Current Capacity
| Manufacturing | Capacity |
|---|---|
| Solar modules | 8.50 GW |
| Solar cells | 3.00 GW |
| Additional cell capacity under ramp-up | 3.00 GW |
Avaada’s current module capacity consists of approximately 1.5 GW at Dadri and 7 GW at Nagpur, according to company disclosures.
4. Planned Capacity – FY28
Avaada Electro is targeting a significantly larger integrated manufacturing footprint by FY28.
| Manufacturing | Current | FY28 Target |
|---|---|---|
| Solar modules | 8.5 GW | 13.6 GW |
| Solar cells | 3 GW | 12 GW |
| Ingot & wafer | — | 3 GW |
The additional capacity is primarily planned at Greater Noida, Uttar Pradesh, along with further upstream manufacturing at Nagpur.
The planned Greater Noida project includes approximately:
- 5.1 GW module capacity
- 6 GW cell capacity
with commissioning targeted during FY28.
5. Technology – TOPCon
A major focus of Avaada is N-type TOPCon technology.
TOPCon offers higher efficiency potential compared with traditional PERC technology and is increasingly becoming an important technology in India’s solar-manufacturing industry.
Avaada says its upcoming cell lines will use advanced N-type TOPCon technology.
The company’s current modules include:
Up to 720 Wp output
Up to 23%+ module efficiency
Bifacial technology
30-year performance warranty
according to company product specifications.
6. Business Model
Avaada Electro’s business model can be understood through three layers:
1. Manufacturing
Produce solar cells and modules.
2. Captive Group Demand
Supply modules to Avaada Energy and other Avaada Group renewable-energy businesses.
3. External Customers
Sell modules to:
- EPC companies
- Solar developers
- Rooftop installers
- Commercial customers
- Utility-scale projects
- Channel partners
The company has recently been expanding its external distribution/channel presence as well.
7. Customer Concentration – Important
This is one of the most important points in the Avaada Electro story.
Avaada Energy Private Limited (AEPL), another Avaada Group company, has historically accounted for a very large proportion of Avaada Electro’s revenue.
According to the updated DRHP:
| Fiscal Year | Revenue from AEPL |
|---|---|
| FY25 | 99.74% |
| FY26 | 89.34% |
This means the company remains significantly dependent on its group company as a customer.
The company argues that Avaada Energy’s renewable-project pipeline provides a significant order pipeline for its manufacturing business.
Nevertheless, customer concentration remains an important risk to monitor.
8. FY26 Financial Performance
The FY26 numbers show extremely rapid growth.
₹ Crore
| Particular | FY25 | FY26 |
|---|---|---|
| Revenue from operations | ₹911.6 Cr | ₹5,303.5 Cr |
| PAT | ₹173.3 Cr | ₹888.7 Cr |
| Revenue growth | — | ~482% |
| PAT growth | — | ~413% |
Revenue increased almost six times while PAT increased roughly five times.
This is one of the fastest financial ramps among India’s newer solar-manufacturing companies.
9. FY25 Financial Performance
For comparison, FY25 standalone financials reported:
| Particular | FY25 |
|---|---|
| Operating income | ₹911.6 Cr |
| PAT | ₹173.3 Cr |
| OPBDIT margin | ~27.9% |
| PAT margin | ~19.3% |
| Total debt / OPBDIT | ~1.9x |
| Interest coverage | ~27.4x |
These figures are based on ICRA’s analysis of audited/provisional company financial information.
10. Why FY26 Growth Was So High
The company essentially moved from a limited-revenue manufacturing operation into large-scale commercial production.
The rapid increase in:
Module capacity → production → Avaada Energy demand → external sales
resulted in the sharp revenue expansion.
This is why the FY25-to-FY26 growth rate should not simply be extrapolated indefinitely.
The business is transitioning from a capacity ramp-up phase to a much larger-scale manufacturing operation.
11. Balance Sheet & Debt
As of March 2026, the company had substantial borrowings associated with its manufacturing expansion.
The updated DRHP states that borrowings were approximately ₹3,926.4 crore as of June 2026.
A portion of the debt was used to finance the development of the Dadri and Nagpur manufacturing facilities.
The company also has loans from its corporate promoter.
As of 31 March 2026:
Promoter loans: ~₹526 crore
Interest rates: 8.15% and 8.65%
Repayment: After eight years
The company states that interest on these promoter loans was accruing and unpaid as of the UDRHP date.
12. Promoter Support
Avaada Electro is part of the broader Avaada Group, founded and led by entrepreneur Vineet Mittal.
The company’s official website identifies Vineet Mittal as Chairman & Whole-time Director.
The updated DRHP discloses significant promoter support, including:
- Equity contributions
- Promoter loans
- Corporate guarantees
- EPC support
- Manufacturing-facility development support
As of March 2026, promoter-related equity contribution was approximately ₹504.74 crore, while outstanding promoter borrowings were approximately ₹529.05 crore.
13. Related-Party Transactions – Important Monitorable
Another important aspect is the company’s relationship with other Avaada Group entities.
The company has purchased significant capital goods/services and made EPC payments to Avaada Power and Lighting Limited (AVPL) for its manufacturing facilities.
As of 31 March 2026, disclosed purchases of capital goods were approximately:
₹1,678.8 crore
and corresponding EPC payments were approximately:
₹1,567.2 crore
The transactions are disclosed in the company’s IPO documents.
This does not by itself indicate wrongdoing, but it is an important area for investors to monitor because of the company’s dependence on the broader group.
14. IPO – Major Development
Avaada Electro filed an updated Draft Red Herring Prospectus in August 2026 for a proposed IPO of up to:
₹7,600 Crore
The proposed structure is:
| Component | Amount |
|---|---|
| Fresh Issue | ₹1,600 Cr |
| Offer for Sale | ₹6,000 Cr |
| Total IPO | ₹7,600 Cr |
The OFS is proposed by promoter/shareholder Avaada Ventures Private Limited.
15. IPO Use of Funds
The fresh issue is proposed primarily to reduce debt.
Approximately:
₹1,200 Crore
of the fresh issue proceeds is proposed to be used towards repayment/prepayment of borrowings and related obligations.
The balance would be used for general corporate purposes.
This means the IPO has two different purposes:
Fresh issue → Company receives capital → Debt reduction
OFS → Existing shareholder sells shares → Company does not receive that money
This distinction is particularly important when evaluating the IPO.
16. IPO Status
As of 21 September 2026:
Updated DRHP filed: Yes
Fresh issue: ₹1,600 Cr
OFS: ₹6,000 Cr
Proposed total issue: ₹7,600 Cr
Price band: Not announced
IPO dates: Not announced
Listing: Proposed on NSE/BSE
The August 2026 UDRHP is still a draft offer document, so final IPO terms can change before the RHP/final prospectus.
17. IPO Merchant Bankers
The proposed issue has appointed:
- ICICI Securities
- Axis Capital
- BofA Securities India
- HSBC Securities & Capital Markets India
- SBI Capital Markets
- IIFL Capital Services
as book-running lead managers.
18. Unlisted Share Status
Avaada Electro is currently an unlisted public company.
There is no NSE/BSE traded equity price yet.
Private-market platforms may quote shares before listing, but these prices can differ significantly depending on:
- Share availability
- Seller expectations
- Transaction size
- IPO expectations
- Liquidity
- IPO valuation
- Negotiation
Therefore, I would not treat an OTC quote as an official market price.
The IPO documents are a better reference point for understanding the company’s capital structure until a transparent exchange price exists.
19. Competitive Position
Avaada Electro operates in India’s rapidly expanding solar manufacturing industry.
Relevant listed/IPO-stage peers include:
- Waaree Energies
- Premier Energies
- Vikram Solar
- Emmvee Photovoltaic Power
- Websol Energy System
Avaada’s key differentiator is its ambition to build a more vertically integrated manufacturing chain.
Current
Modules + Cells
Target
Ingot + Wafer + Cells + Modules
This could potentially improve supply-chain control, but it also requires substantial capital expenditure.
20. Growth Drivers
1. India’s solar manufacturing push
India is encouraging domestic manufacturing of solar cells and modules to reduce dependence on imported components.
This creates a structural opportunity for domestic manufacturers.
2. Rapid capacity expansion
Module capacity is targeted to increase:
8.5 GW → 13.6 GW
while cell capacity is targeted to increase:
3 GW → 12 GW
by FY28.
3. TOPCon adoption
N-type TOPCon is becoming increasingly important in high-efficiency solar modules.
4. Vertical integration
Future ingot/wafer capacity could provide greater control over the supply chain.
5. Captive group demand
Avaada Energy’s large renewable project pipeline provides a natural source of module demand.
6. External customer expansion
The company is increasingly developing channel and external customer relationships beyond the Avaada Group.
7. Debt reduction through IPO
If the proposed fresh issue is completed as planned, approximately ₹1,200 crore would be directed towards debt reduction.
21. Key Risks
Customer Concentration
Nearly 89% of FY26 revenue came from Avaada Energy, making this one of the most important risks.
Related-Party Dependence
The company has significant financial and operational relationships with Avaada Group entities.
High Capex
The planned manufacturing expansion requires several thousand crore rupees of investment.
Debt
Borrowings were approximately ₹3,926 crore as of June 2026, increasing the importance of cash generation and debt servicing.
Solar Module Pricing
Solar-module prices can be affected by:
- Chinese imports
- Global polysilicon prices
- Cell prices
- Oversupply
- Technology changes
- Government trade policy
Technology Risk
Solar technology evolves quickly.
TOPCon is currently a major technology, but future technologies could reduce the economic life of existing production lines.
IPO/OFS Structure
The proposed ₹7,600 crore IPO contains a large ₹6,000 crore OFS component.
Only the ₹1,600 crore fresh issue provides capital to the company.
Limited Operating History
Avaada Electro began meaningful revenue-generating operations only recently, making long-term financial track record relatively short.
22. What Investors Should Track
| Metric | Why it matters |
|---|---|
| Module capacity utilisation | Manufacturing efficiency |
| Cell capacity utilisation | Integration economics |
| Module ASP | Pricing power |
| EBITDA margin | Manufacturing profitability |
| Customer concentration | Revenue risk |
| External sales | Diversification |
| Avaada Energy orders | Captive demand |
| Debt/EBITDA | Leverage |
| Interest cost | Financial burden |
| Working capital | Cash conversion |
| Cell/wafer commissioning | Vertical integration |
| IPO progress | Capital-market access |
| Import duties | Competitive environment |
| TOPCon efficiency | Technology competitiveness |
23. Business Model in One Picture
Polysilicon
↓
Ingot / Wafer
↓
Solar Cell
↓
TOPCon Module
↓
Avaada Energy / External Customers
↓
Solar Projects
This integrated structure is the central part of Avaada Electro’s long-term strategy.
24. Quick Snapshot
| Parameter | Avaada Electro |
|---|---|
| Incorporated | 2021 |
| Public company conversion | Sep 2025 |
| Promoter | Avaada Ventures |
| Chairman | Vineet Mittal |
| Business | Solar PV Manufacturing |
| Module capacity | 8.5 GW |
| Cell capacity | 3 GW operational |
| Cell capacity under ramp-up | 3 GW |
| FY26 Revenue | ₹5,303.5 Cr |
| FY26 PAT | ₹888.7 Cr |
| FY26 Revenue growth | ~482% |
| FY26 PAT growth | ~413% |
| FY26 revenue from AEPL | 89.34% |
| June-26 borrowings | ₹3,926.4 Cr |
| FY28 module target | 13.6 GW |
| FY28 cell target | 12 GW |
| FY28 ingot/wafer target | 3 GW |
| Proposed IPO | ₹7,600 Cr |
| Fresh issue | ₹1,600 Cr |
| OFS | ₹6,000 Cr |
| IPO status | UDRHP filed |
| Price band | TBA |
| Listing | Proposed NSE/BSE |
| Current equity status | Unlisted |
25. UnlistedCart Takeaway
Avaada Electro is one of the newer large-scale solar manufacturing stories in India, with an unusually rapid scale-up in both revenue and manufacturing capacity.
The company has moved from a relatively small manufacturing base to 8.5 GW of operational module capacity and 3 GW of operational TOPCon cell capacity, while targeting 13.6 GW modules, 12 GW cells and 3 GW ingot/wafer capacity by FY28.
The FY26 financial jump is substantial:
Revenue: ₹912 Cr → ₹5,304 Cr
PAT: ₹173 Cr → ₹889 Cr
But investors should not look at the growth numbers in isolation.
The most important areas to examine are customer concentration, related-party transactions, debt, manufacturing utilisation, module pricing and the funding required for the next phase of capacity expansion.
The proposed ₹7,600 crore IPO is potentially a major liquidity event, but the structure is important:
₹1,600 Cr fresh issue + ₹6,000 Cr OFS
Only the fresh issue provides new capital to Avaada Electro, with approximately ₹1,200 crore proposed for debt reduction.
Key Theme
8.5 GW Modules + 3 GW TOPCon Cells + 13.6 GW FY28 Target + Vertical Integration + ₹7,600 Cr Proposed IPO
Official & Research Links
Avaada Electro – Official Website
Avaada Electro – About the Company
Avaada Electro – Financial Reports
Avaada Electro – Press Releases
Avaada Electro – FY2024-25 Annual Report
Avaada Electro – Sustainability Report FY2024-25
Avaada Group – Official Website
Moneycontrol – August 2026 Updated DRHP / ₹7,600 Cr IPO
ICRA – Avaada Electro Rating Rationale
Disclaimer
This report is for informational and research purposes only and should not be considered investment advice, a recommendation, or an offer to buy or sell securities. Avaada Electro remains unlisted as of September 2026. IPO terms, price band, dates and final issue structure may change before the RHP/final prospectus. Private-market prices, where available, may not represent fair value because of limited liquidity and price discovery. Investors should independently verify the latest UDRHP/RHP, audited financial statements, shareholding, related-party disclosures and final IPO terms before making an investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
