
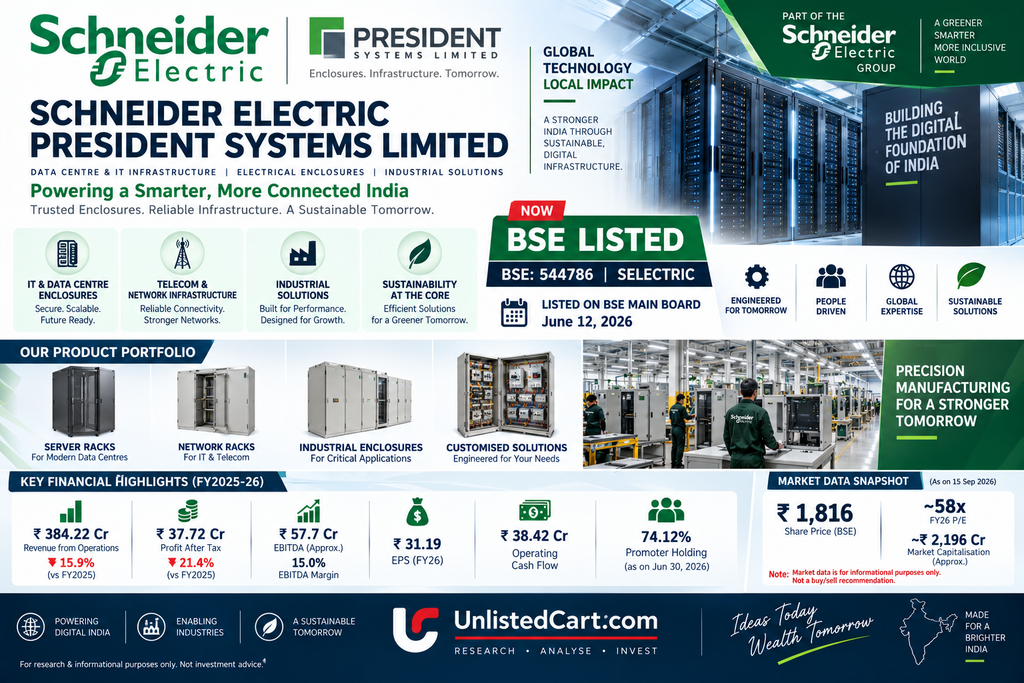
BSE: 544786 | Scrip ID: SELECTRIC | ISIN: INE155D01018
Sector: Electrical Equipment / Industrial Electronics
Industry: Data Centre Infrastructure, IT & Telecom Enclosures, Electrical Distribution & Industrial Enclosures
CIN: L32109KA1984PLC079103
Face Value: ₹10 per share
Registered Office: 5C/1, KIADB Industrial Area, Attibele, Bengaluru, Karnataka
Promoter: Schneider Electric South East Asia (HQ) Pte. Ltd.
Promoter Holding: 74.12% as of June 30, 2026
Listing: BSE Main Board + MSEI
BSE Scrip Code: 544786
Current Status: Listed — no longer an unlisted share
Official Company Website
Official Company Overview
Official Investor Relations
1. Important Update – From Unlisted to Listed
Schneider Electric President Systems has undergone a significant capital-market transition.
The company was historically traded on the Metropolitan Stock Exchange of India (MSEI), and for many investors it was treated as an illiquid/unlisted opportunity.
However, on June 12, 2026, the company’s 12,096,000 equity shares were admitted to dealings on the BSE Main Board through the direct-listing route. The shares were initially placed in the T Group and traded in the Trade-for-Trade segment for the first 10 trading days.
Current listing details
| Particular | Details |
|---|---|
| BSE | 544786 |
| BSE Symbol | SELECTRIC |
| MSEI Symbol | SELECTRIC |
| ISIN | INE155D01018 |
| Shares Listed | 1.2096 Cr |
| Face Value | ₹10 |
| Listing Date on BSE | June 12, 2026 |
| Listing Route | Direct Listing |
| Exchange | BSE Main Board + MSEI |
| Market Lot | 1 share |
Therefore, Schneider Electric President Systems should now be analysed as a listed equity rather than as an unlisted-share opportunity.
2. Company Overview
Schneider Electric President Systems Limited is an Indian manufacturer and supplier of standard and customised enclosure systems used in IT, networking, telecom and industrial-electronics applications.
The company has operated in the enclosure business for more than three decades and focuses on:
- Server racks
- Network racks
- IT enclosures
- Telecom cabinets
- Industrial cabinets
- Card frames
- Components and accessories
- Electrical equipment
- Contract manufacturing
- IT infrastructure management solutions
The company’s stated business includes manufacturing of enclosures, card frames, components and accessories along with trading of electrical equipment.
3. Business Model
The company operates primarily in a single business segment related to products and systems for electricity distribution, according to its regulatory filings.
At the product level, however, its operations cover several important infrastructure categories.
Major product categories
1. Flexibox
Designed for LAN/WAN applications and smaller IT infrastructure deployments.
2. Cyberack
19-inch server/network enclosure designed for rapid assembly and equipment integration.
3. Smart Rack
Cost-effective rack enclosure designed for SMEs and office environments.
4. Uniserv DLX
Heavy-duty enclosure designed for improved robustness and transportation protection.
The company’s official product catalogue confirms these four principal enclosure categories.
4. Key Application Areas
The company’s products are used across:
- IT infrastructure
- Data centres
- Networking
- Telecom
- Industrial electronics
- General electronics
- Server infrastructure
- Enterprise computing
- Infrastructure management
The company also provides customised solutions rather than operating solely as a standard catalogue manufacturer.
5. Why Data Centres Are Important
One of the major structural opportunities for the company is the rapid growth of India’s digital infrastructure.
Modern data centres require extensive physical infrastructure around:
- Server racks
- Network racks
- Cable management
- Airflow management
- Power integration
- Equipment protection
- Security
- Thermal management
President Systems’ products are designed specifically around the physical infrastructure required to house and manage IT equipment.
The company states that its enclosures are engineered around IT standards and designed to improve management of space, airflow and power-supply integration.
This gives the business exposure to the broader expansion of:
Cloud → Data Centres → Servers → Networking → Rack Infrastructure
However, investors should distinguish between the company’s actual reported revenue growth and the broader data-centre opportunity. The data-centre theme does not automatically translate into equivalent earnings growth.
6. Schneider Electric Parentage
The company benefits from its association with the global Schneider Electric group.
As of June 30, 2026, Schneider Electric South East Asia (HQ) Pte. Ltd. held 74.12% of the company.
This provides the company with access to a large global industrial ecosystem and potentially supports:
- Technology
- Engineering capabilities
- Global customer relationships
- Procurement
- Product development
- International standards
- Brand credibility
The promoter holding also creates a high degree of ownership concentration.
7. FY2025-26 Financial Performance
FY2026 was weaker than FY2025 at the revenue and profitability level.
Consolidated/Standalone reported financial picture
| Particular | FY2026 | FY2025 |
|---|---|---|
| Revenue from Operations | ₹384.22 Cr | ₹456.98 Cr |
| Other Income | ₹7.16 Cr | ₹8.37 Cr |
| Total Income | ₹391.39 Cr | ₹465.36 Cr |
| PBT before exceptional | ₹52.02 Cr | ₹65.16 Cr |
| PBT | ₹50.66 Cr | ₹65.16 Cr |
| PAT | ₹37.72 Cr | ₹48.02 Cr |
| EPS | ₹31.19 | ₹39.71 |
FY2026 figures are based on the reported financial statements, while FY2025 EPS has been presented on the post-bonus share basis.
Revenue growth
Revenue declined from:
₹456.98 Cr → ₹384.22 Cr
This represents approximately:
–15.9% YoY
PAT growth
PAT declined from:
₹48.02 Cr → ₹37.72 Cr
Approximate decline:
–21.4%
Therefore, FY2026 was not a year of earnings acceleration despite the company’s long-term exposure to IT infrastructure and data-centre-related demand.
8. EBITDA Analysis
Using the reported PBT before exceptional items, finance costs and depreciation:
Approximate FY2026 EBITDA = ₹57.7 Cr
Approximate EBITDA margin:
₹57.7 Cr / ₹384.22 Cr ≈ 15.0%
For FY2025, the comparable calculation gives approximately ₹71.5 Cr EBITDA, implying a margin of roughly 15.6%.
Therefore, operating profitability remained reasonably resilient despite the revenue decline.
The bigger concern is the absolute decline in earnings rather than a collapse in operating margins.
9. Quarterly Trend
The quarterly trend shows considerable volatility.
| Quarter | Revenue | PAT |
|---|---|---|
| Jun 2025 | ₹93.71 Cr | ₹8.14 Cr |
| Sep 2025 | ₹93.56 Cr | ₹8.32 Cr |
| Dec 2025 | ₹115.49 Cr | ₹12.14 Cr |
| Mar 2026 | ₹81.46 Cr | ₹9.13 Cr |
| Jun 2026 | ₹109.53 Cr | ₹4.47 Cr |
The Q1 FY2027 result is particularly important.
Revenue increased approximately 16.9% YoY, but PAT declined approximately 45% YoY to ₹4.47 Cr.
This indicates that the recent revenue recovery has not yet translated into corresponding profit growth.
10. Q1 FY2027 – Important Update
For the quarter ended June 30, 2026:
Revenue from operations: ₹109.53 Cr
Total income: ₹111.44 Cr
PBT: ₹6.23 Cr
PAT: ₹4.47 Cr
EPS: ₹3.70
Revenue increased from ₹93.71 Cr in Q1 FY2026 to ₹109.53 Cr, but PAT declined from ₹8.14 Cr to ₹4.47 Cr.
This creates an important monitoring point:
Revenue growth has returned, but margin/profit conversion needs improvement.
11. Balance Sheet & Debt
The company has historically maintained a relatively conservative debt position.
FY2026 finance cost was only approximately:
₹0.65 Cr
against revenue of ₹384.22 Cr.
This indicates that interest expense is not currently a major earnings burden.
The company generated approximately:
₹38.42 Cr operating cash flow in FY2026
which was broadly similar to FY2025 operating cash flow of approximately ₹38.56 Cr.
This is an important positive aspect because operating cash generation remained relatively stable despite lower PAT.
12. Cash Flow Quality
FY2026 operating cash flow:
₹38.42 Cr
FY2026 PAT:
₹37.72 Cr
Therefore, cash conversion was broadly healthy.
The company also had:
- Increase in trade payables
- Increase in inventory
- Increase in trade receivables
- Reduction in certain other assets
The cash-flow statement indicates that working-capital movements supported operating cash generation.
13. Shareholding Pattern
As of June 30, 2026:
| Category | Holding |
|---|---|
| Promoter | 74.12% |
| DII | 0.25% |
| Public / Others | ~25.64% |
The promoter holds approximately 89.65 lakh shares out of the total 1.2096 Cr shares.
Major disclosed public holders
The June 2026 filing includes several sizeable public shareholders, including:
- Niraj Kumar – approximately 4.58%
- Hitesh Satishchandra Doshi – approximately 3.14%
- Sukant Venture Private Limited – approximately 1.18%
These holdings are disclosed in public shareholding data.
14. Bonus Issue
The company allotted 6,048,000 bonus equity shares in a 1:1 ratio in November 2025.
This doubled the equity share count from approximately 60.48 lakh shares to 120.96 lakh shares.
This is important when comparing historical EPS and share prices.
For example, an old EPS figure before the bonus cannot simply be compared with the current EPS without adjusting for the bonus.
15. Direct BSE Listing
The BSE listing is one of the biggest recent developments.
The company received approval for direct listing and its shares started trading on BSE from June 12, 2026.
The listed securities:
- BSE Code: 544786
- Symbol: SELECTRIC
- ISIN: INE155D01018
- Shares: 1.2096 Cr
- Face value: ₹10
The company continues to be listed on MSEI.
Official Investor Announcements
16. Current Market Price & Market Capitalisation
The latest available close before this report is:
₹1,816 per share — September 15, 2026.
With approximately 1.2096 Cr shares outstanding:
Approximate market capitalisation = ₹2,196 Cr
For context, the stock has traded in a wide range since its BSE listing.
Reported 52-week range:
₹769.99 – ₹2,718.75.
The stock has therefore experienced significant price discovery since the direct listing.
17. Valuation
Using the FY2026 EPS of:
₹31.19
and a market price of approximately:
₹1,816
the implied FY2026 P/E is approximately:
58.2x
Using the June 2026 book value of approximately ₹196.52/share, the implied P/B is approximately:
9.2x
Market-data providers similarly show the stock trading at a P/E in the high-50s/60x area around September 2026.
Illustrative P/E sensitivity
| P/E | Value based on FY26 EPS ₹31.19 |
|---|---|
| 20x | ₹624 |
| 25x | ₹780 |
| 30x | ₹936 |
| 35x | ₹1,092 |
| 40x | ₹1,248 |
| 45x | ₹1,404 |
| 50x | ₹1,560 |
| 55x | ₹1,715 |
| 60x | ₹1,871 |
| 65x | ₹2,027 |
These are valuation scenarios, not price targets or forecasts.
At ₹1,816, the market is effectively valuing the business at around 58x FY2026 earnings.
Therefore, a significant part of the valuation requires expectations of future earnings growth rather than simply the FY2026 earnings base.
18. What Could Support Future Growth?
Data-centre infrastructure
Increasing server density, cloud infrastructure and digitalisation could increase demand for sophisticated rack and enclosure infrastructure.
Telecom infrastructure
The company’s products are also applicable to telecom and networking infrastructure.
Customised solutions
Customised industrial and telecom enclosures can provide differentiation compared with purely commodity manufacturers.
Schneider Electric ecosystem
The global parent can potentially provide technology, customer access, engineering capabilities and procurement advantages.
Contract manufacturing
The company has historically executed contract manufacturing projects for established international businesses.
19. Competitive Advantages
1. Global parentage
74.12% promoter ownership by Schneider Electric South East Asia gives the company a strong strategic parent.
2. Established manufacturing capability
The company has more than three decades of experience in enclosure systems.
3. Customisation
The business is not restricted to standard racks and cabinets.
4. Product breadth
The portfolio covers Flexibox, Cyberack, Smart Rack and Uniserv DLX as well as customised solutions.
5. Data-centre exposure
The company’s products form part of the physical infrastructure supporting IT equipment.
20. Key Risks
1. High valuation
At around ₹1,816, the stock trades at roughly 58x FY2026 EPS.
This leaves limited room for earnings disappointment if growth does not accelerate.
2. FY2026 revenue decline
Revenue declined approximately 16% YoY.
3. Q1 FY2027 profit decline
Despite 17% revenue growth in Q1 FY2027, PAT declined approximately 45%.
This indicates pressure on profit conversion.
4. Customer / parent concentration
A large strategic parent can provide advantages, but related-party transactions and dependence on the broader group ecosystem should be monitored.
5. Small-cap liquidity
Despite the BSE listing, trading volumes remain relatively modest compared with larger electrical-equipment companies. Recent daily volumes have often been only a few thousand shares.
6. Cyclical IT infrastructure spending
Data-centre and enterprise IT spending can fluctuate based on economic cycles and corporate capex.
7. Competition
The company competes indirectly with larger electrical, industrial, IT infrastructure and enclosure manufacturers.
21. Key Metrics Snapshot
| Metric | FY2026 |
|---|---|
| Revenue | ₹384.22 Cr |
| PAT | ₹37.72 Cr |
| EPS | ₹31.19 |
| Approx. EBITDA | ₹57.7 Cr |
| EBITDA Margin | ~15.0% |
| CFO | ₹38.42 Cr |
| Market Price* | ₹1,816 |
| Market Cap* | ~₹2,196 Cr |
| P/E* | ~58x |
| P/B* | ~9.2x |
| Promoter Holding | 74.12% |
| Shares Outstanding | 1.2096 Cr |
*Market price and valuation based on September 15, 2026 closing price.
22. Investment Research View
Schneider Electric President Systems is an interesting business because it sits at the intersection of:
Electrical infrastructure + IT infrastructure + data centres + telecom + industrial electronics.
Its association with Schneider Electric provides a significant strategic backdrop, while the company’s established enclosure manufacturing capabilities create a direct connection to India’s digital infrastructure expansion.
However, the current financial picture needs to be separated from the long-term industry opportunity.
FY2026 revenue and PAT declined, and Q1 FY2027 showed a sharp fall in profit despite double-digit revenue growth. At the same time, the stock’s market valuation is substantially higher than what the current earnings base alone would imply.
Therefore, the key variables to monitor are:
- Revenue recovery
- EBITDA margin
- PAT conversion
- Data-centre-related order growth
- Working-capital requirements
- Parent-company business contribution
- Cash-flow generation
- New product/customised solution growth
- Trading liquidity
- Whether earnings growth can justify the current valuation
23. Important Change for UnlistedCart Investors
This company was historically covered in the unlisted/illiquid-share ecosystem.
That thesis has now changed.
Since June 12, 2026, Schneider Electric President Systems has been directly listed on the BSE Main Board.
Therefore:
Old unlisted-market prices should no longer be used as the primary reference for valuation.
The appropriate reference is now the BSE market price of SELECTRIC (544786).
View Schneider Electric President Systems Investor Relations
View Official Annual Reports & Financials
View Official Shareholding Pattern
24. Overall Assessment
Schneider Electric President Systems has a differentiated position as an Indian enclosure and IT infrastructure manufacturer backed by the Schneider Electric group.
The major positives are:
- Strong global parent
- 74.12% promoter ownership
- Established enclosure manufacturing business
- Exposure to IT, telecom and data-centre infrastructure
- Broad product portfolio
- Healthy operating cash generation
- Low finance-cost burden
- Direct BSE Main Board listing
The major areas requiring monitoring are:
- FY2026 revenue decline
- FY2026 PAT decline
- Q1 FY2027 profit compression
- Relatively high valuation
- Small-cap liquidity
- Dependence on continued infrastructure/IT capex
- Ability to convert revenue growth into sustainable earnings growth
The biggest analytical question at the current valuation is not whether India’s data-centre ecosystem can grow. It is whether Schneider Electric President Systems can grow its own earnings rapidly enough to support the valuation currently being assigned by the market.
25. Official & Relevant Links
Company
Schneider Electric President Systems – Official Website
Company Overview
Products
Investor Relations
Annual Reports
Official Annual Reports & Financial Results
Corporate Announcements
Official Company Announcements
Shareholding
BSE Listing
The company’s BSE scrip is 544786 / SELECTRIC, with listing effective June 12, 2026.
Disclaimer
This report is prepared for research and informational purposes only and should not be construed as investment advice, a recommendation, a solicitation to buy or sell securities, or a guarantee of future returns.
Valuation scenarios are illustrative and based on stated assumptions. Actual market valuation can differ materially due to earnings growth, market conditions, liquidity, corporate actions and investor expectations.
Investors should review the company’s latest filings, financial statements, shareholding pattern, exchange disclosures and risk factors before making any investment decision.
Important: Schneider Electric President Systems Limited is now a BSE-listed company, so this report should not be interpreted as a recommendation to purchase an unlisted security.
**For more such unlisted stocks visit **
