
Business: Packaged Drinking Water | Beverages | Premium Water | Carbonated Drinks
Status: Unlisted Private Company
CIN: U15540MH1984PTC127572
Incorporated: 5 March 1984
Registered Office: Chakala Division, Western Express Highway, Andheri East, Mumbai, Maharashtra – 400099
Paid-up Capital: ~₹46.5 lakh
FY2024-25 Revenue: ~₹3,218 crore
FY2024-25 Operating Profit: ~₹393 crore
FY2024-25 PAT: ~₹253 crore
FY2024-25 Net Worth: ~₹1,259 crore
FY2024-25 Debt: Nil reported
Listing Status: Unlisted
Industry: FMCG / Packaged Beverages
Executive Summary
Bisleri International Private Limited is one of India’s most recognised consumer brands and the country’s leading packaged drinking-water businesses.
The company has operated for more than four decades and has built an exceptionally strong association between the word “Bisleri” and packaged drinking water in India.
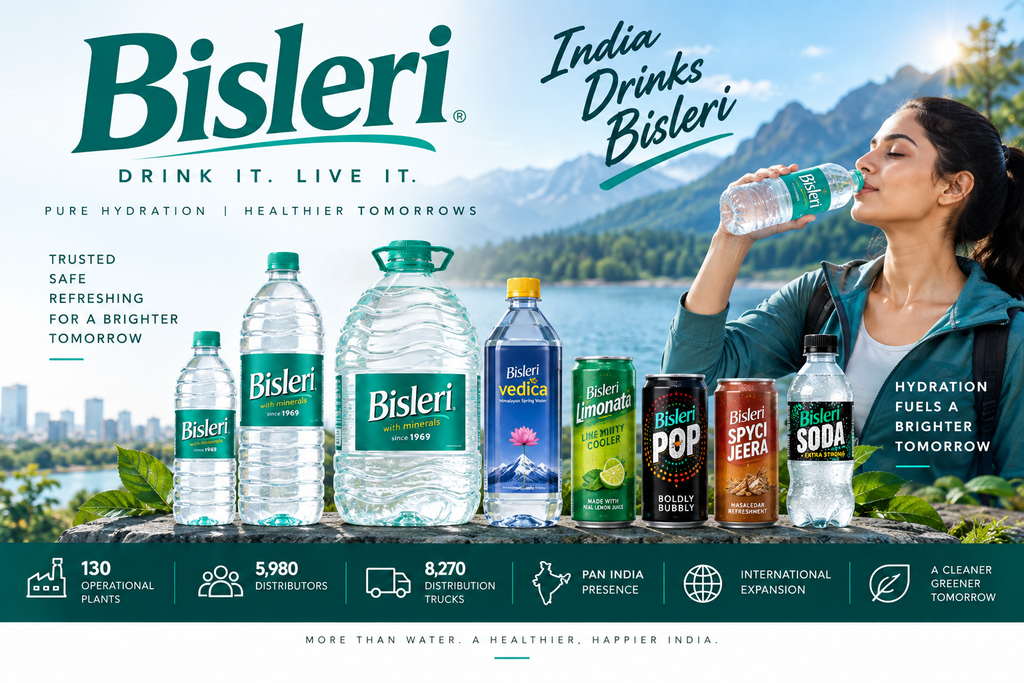
The business today is much broader than a traditional bottled-water company. Its portfolio includes:
- Bisleri packaged drinking water
- Bisleri Vedica Himalayan Spring Water
- Bisleri Soda
- Limonata
- POP
- Spyci Jeera
- Rev and other beverage products
The official company website currently reports 130 operational plants, 5,980 distributors and 8,270 distribution trucks, demonstrating the scale of its physical distribution network.
Bisleri International – Official Website
Financially, Bisleri has grown substantially over the last five years. Tofler’s FY2024-25 data shows sales of approximately ₹3,218 crore, operating profit of approximately ₹393 crore and net profit of approximately ₹253 crore. Net worth increased to approximately ₹1,259 crore, while reported borrowings were nil.
One of the most important points for investors is that Bisleri is not currently pursuing an IPO.
In August 2025, Vice-Chairperson Jayanti Chauhan stated that Bisleri would remain privately held and that the company had no plans for an IPO or another stake sale. She also said the company was investing approximately ₹600 crore in manufacturing, distribution and product development.
Therefore, Bisleri should be viewed as a high-quality private FMCG business, but not as a conventional pre-IPO opportunity.
Company Overview
Company Name: Bisleri International Private Limited
Former Name: Acqua Minerals Private Limited / Acqua Minerals Limited
CIN: U15540MH1984PTC127572
Incorporation: 5 March 1984
ROC: Mumbai
Company Type: Private Limited Company
Status: Active and Unlisted
Authorised Capital: ₹50 lakh
Paid-up Capital: ₹46.5 lakh
Public corporate records confirm that Bisleri International is an active unlisted private company headquartered in Mumbai.
The official website identifies the company as Bisleri International Pvt. Ltd. and lists its Mumbai headquarters at Chakala, Andheri East.
History and Brand Evolution
Bisleri has a legacy of more than 50 years in India’s packaged-water industry.
The brand has evolved from a bottled-water company into a broader beverage platform.
The company’s strategy today is based on protecting the strength of the core Bisleri brand while expanding into adjacent categories.
This includes:
Core hydration → Premium water → Carbonated beverages → New-age beverage products → International expansion
This strategy is important because packaged drinking water is a large but relatively commoditised category. Expanding into adjacent beverages gives Bisleri an opportunity to increase its addressable market and consumer engagement.
Business Model
1. Packaged Drinking Water
This remains the core business.
Bisleri sells packaged water in multiple formats for:
- Home consumption
- Offices
- Restaurants
- Travel
- Hotels
- Events
- Retail
- Institutional customers
The company states that its water passes through a 10-step quality process and 90 quality tests designed to ensure safe and hygienic drinking water.
2. Premium Water
Bisleri Vedica is positioned as a premium Himalayan spring-water offering.
Bisleri Vedica and Product Portfolio
Premiumisation is strategically important because it can potentially increase average selling prices and margins compared with standard packaged water.
3. Carbonated Beverages
Bisleri has expanded into carbonated and flavoured beverages through brands such as:
- Limonata
- POP
- Spyci Jeera
- Bisleri Soda
- Rev
The company has stated that it intends to remain within the broader beverage category while continuing to innovate.
4. Direct-to-Consumer
Bisleri also operates a doorstep-delivery ecosystem through its online platform and app.
This gives the company greater control over the customer relationship and creates an opportunity for recurring household purchases.
Distribution Strength
Distribution is one of Bisleri’s biggest competitive advantages.
The company’s current official website reports:
130 operational plants
5,980 distributors
8,270 distribution trucks
It also states that the network covers India and neighbouring markets.
This is particularly important in bottled water because transportation costs can be significant relative to the value of the product.
A strong local manufacturing and distribution network helps reduce logistics costs and enables the company to keep products available across a large geography.
Manufacturing Network
Bisleri’s manufacturing footprint is another major competitive advantage.
The company currently states that it has 130 operational plants, including 13 owned facilities.
The combination of:
Plants + distributors + trucks + retail reach
creates a meaningful barrier to entry.
A competitor can manufacture bottled water relatively easily, but replicating Bisleri’s national distribution network and brand recognition would require substantial investment and time.
Brand Strength
The biggest asset of Bisleri may not be its manufacturing infrastructure.
It is the brand itself.
Bisleri has become one of the most recognised names in packaged drinking water in India.
This creates several advantages:
- Consumer trust
- Brand recall
- Premium pricing potential
- Retailer preference
- Institutional acceptance
- Strong advertising efficiency
- High repeat consumption
In a category where consumers are particularly sensitive to safety and quality, brand trust can be a powerful competitive advantage.
Market Position
Bisleri remains one of India’s leading packaged drinking-water brands.
According to statements made by Jayanti Chauhan in 2025, the company had approximately 32% share of the organised packaged drinking-water segment. She also stated that the business distributed through more than four lakh outlets.
The organised packaged-water market faces competition from:
- Coca-Cola’s Kinley
- PepsiCo’s Aquafina
- Tata Consumer’s Himalayan
- Regional packaged-water companies
- Numerous local players
However, Bisleri’s brand remains one of its biggest differentiators.
Industry Opportunity
India’s packaged drinking-water industry has several structural growth drivers.
Rising Urbanisation
Urbanisation increases demand for convenient and safe drinking water.
Rising Travel
Air travel, road travel, rail travel and tourism create recurring demand for bottled water.
Health Awareness
Consumers increasingly prefer packaged water over unverified local alternatives.
Institutional Consumption
Hotels, restaurants, offices, hospitals and events generate significant recurring demand.
Premiumisation
Consumers are increasingly willing to pay for premium water and differentiated beverages.
Organised Market Growth
Large branded players can gain share as consumers move away from unorganised suppliers.
Financial Performance
Bisleri has shown strong revenue growth over the past five years.
Financial Snapshot
| Particulars | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Sales | ₹1,133 Cr | ₹1,645 Cr | ₹2,342 Cr | ₹2,690 Cr | ₹3,218 Cr |
| Operating Profit | ₹173 Cr | ₹144 Cr | ₹315 Cr | ₹418 Cr | ₹393 Cr |
| PAT | ₹95 Cr | ₹69 Cr | ₹171 Cr | ₹307 Cr | ₹253 Cr |
| Net Worth | ₹466 Cr | ₹535 Cr | ₹701 Cr | ₹1,006 Cr | ₹1,259 Cr |
| Borrowings | ₹25 Cr | ₹26 Cr | ₹39 Cr | ₹5 Cr | Nil |
Source: Tofler financial compilation.
Revenue Growth
Sales increased from approximately:
₹1,133 crore in FY2021
to
₹3,218 crore in FY2025.
That represents approximately 2.8x growth over four years.
The company therefore demonstrated strong top-line expansion even though profitability has fluctuated.
FY2025 sales increased approximately 19.6% over FY2024 according to the available financial data.
Profitability
FY2025 operating profit was approximately ₹393 crore compared with approximately ₹418 crore in FY2024.
PAT declined from approximately ₹307 crore to ₹253 crore.
Therefore, FY2025 was a year in which:
Revenue increased strongly, but profitability declined.
This is an important point for investors.
The business should not be evaluated only on revenue growth.
Investors should monitor:
- EBITDA/operating margin
- Advertising expenditure
- Distribution costs
- Raw-material costs
- PET costs
- Freight
- Product mix
- Premiumisation
- Cash conversion
Margin Analysis
FY2025 operating margin was approximately 12.2%, compared with approximately 15.5% in FY2024.
Net margin declined from approximately 10.9% to 7.6%.
This indicates that the company’s strong revenue growth did not translate proportionately into earnings growth.
The key question going forward is whether Bisleri can regain operating leverage as the new investments in manufacturing and distribution mature.
Balance Sheet
One of Bisleri’s strongest financial characteristics is its balance sheet.
FY2025:
Net Worth: ~₹1,259 crore
Borrowings: Nil reported
Assets: ~₹1,631 crore
Debt/Equity: 0.0x
ROE: ~20.1%
The absence of reported borrowings provides the company with substantial financial flexibility.
This is particularly valuable because Bisleri is currently pursuing an aggressive investment programme.
Investment Programme
In August 2025, Jayanti Chauhan said Bisleri planned to invest approximately ₹600 crore during the year across:
- Manufacturing
- Distribution
- Product development
- Marketing
- Capacity expansion
The company had reportedly invested around ₹850 crore over the previous decade, making the new investment programme substantial relative to its historical spending.
The company indicated that six new plants were part of the expansion programme.
If executed effectively, this could increase:
- Manufacturing capacity
- Geographic reach
- Distribution efficiency
- Product availability
- Revenue potential
However, investors should monitor the return generated on this incremental capital.
International Expansion
International expansion is becoming an increasingly important part of Bisleri’s strategy.
The company has historically targeted markets with large Indian diaspora populations.
In June 2025, Bisleri announced a strategic partnership with Apparel Group to manufacture, market and distribute its beverage portfolio across the Middle East and Africa, beginning with the UAE.
Bisleri–Apparel Group UAE Expansion
The partnership is strategically attractive because Apparel Group already has an extensive retail and consumer ecosystem in the region.
The company has stated that the wider strategy could expand beyond the UAE into Oman, the Middle East and Africa.
UAE Opportunity
The UAE is particularly attractive because of:
- Large Indian diaspora
- High tourism
- High per-capita income
- Hot climate
- Strong packaged-water consumption
- Existing awareness of the Bisleri brand
Bisleri had previously operated in the UAE, so the latest partnership represents an attempt to strengthen and scale its international presence.
In December 2025, Bisleri also entered a three-year hydration partnership with the Emirates Cricket Board, further strengthening its UAE positioning.
Marketing Strength
Bisleri has historically invested heavily in brand-building.
Sports partnerships have become an important part of its recent marketing strategy.
In 2025, Bisleri partnered with five IPL franchises:
- Delhi Capitals
- Gujarat Titans
- Mumbai Indians
- Rajasthan Royals
- Royal Challengers Bengaluru
The company positioned these partnerships around its #DrinkItUp campaign and its effort to connect with younger consumers.
Bisleri also became the official beverage partner of the Tata Women’s Premier League for two seasons beginning in 2026.
These partnerships can strengthen:
- Brand awareness
- Gen-Z engagement
- National reach
- Sports association
- Premium brand perception
Product Diversification
Bisleri’s future growth is unlikely to depend entirely on packaged water.
The company is increasingly exploring beverages adjacent to its core category.
Current brands include:
Bisleri
Vedica
Limonata
Bisleri Soda
POP
Spyci Jeera
This creates the possibility of moving from a single-category water company toward a broader beverage platform.
However, diversification also increases competition because Bisleri begins competing directly with established soft-drink and beverage companies.
Sustainability Strategy
Plastic is simultaneously an essential part of Bisleri’s business model and one of its biggest reputational challenges.
The company has therefore developed its Bottles for Change initiative to encourage PET collection and recycling.
The official website currently reports:
65 cities
52 municipal corporations
8,164 residential welfare associations
1,807 corporates
2,519 educational institutes
2,092 hotels and restaurants
10.09 million citizens
34,888 metric tonnes of used plastic collected and recycled
In 2025, Bisleri also partnered with EcoLine Clothing to convert recovered PET bottles into fashion and lifestyle products.
Competitive Advantages
1. Exceptional Brand Recognition
Bisleri is one of India’s strongest packaged-water brands.
2. Distribution Scale
The company has thousands of distributors and thousands of distribution vehicles.
3. Manufacturing Network
130 operational plants provide substantial geographic coverage.
4. Consumer Trust
Water is a trust-driven category where established brands have an advantage.
5. Strong Balance Sheet
The company reported no borrowings in FY2025 according to Tofler’s financial compilation.
6. Premiumisation Opportunity
Vedica and premium packaging provide opportunities to increase average realisations.
7. International Potential
The UAE and broader Middle East/Africa expansion provide additional growth avenues.
8. Strong Brand-Building Capability
Sports and entertainment partnerships provide significant consumer visibility.
Tata Consumer Acquisition Story
Bisleri became one of India’s most discussed unlisted companies after reports emerged in 2022 that Tata Consumer Products was negotiating to acquire the business.
The proposed transaction was widely reported at approximately ₹6,000–₹7,000 crore.
However, the transaction was never completed.
In March 2023, Tata Consumer Products officially confirmed that discussions with Bisleri had ceased and that there was no definitive agreement or binding commitment.
This is important for investors because older unlisted-market reports sometimes continue to reference the Tata transaction as though it were completed.
It was not.
Bisleri remains privately controlled by the Chauhan family.
Current Ownership and IPO Outlook
This is perhaps the most important consideration for an unlisted investor.
In August 2025, Jayanti Chauhan explicitly stated that Bisleri would:
remain privately held
and that she did not intend to:
- Take the company public
- Sell another stake
- Pursue an IPO
She stated that the company had sufficient internal funds to finance its expansion.
Therefore:
IPO Visibility: LOW
Investors should not purchase Bisleri shares based on an assumption of an imminent IPO.
The company’s current stated strategy is the opposite.
Valuation History
The Tata acquisition discussions provide the most widely reported historical valuation benchmark.
Reports in 2022 indicated a proposed transaction value of approximately:
₹6,000–₹7,000 crore
However, the deal was never completed and therefore this should not be treated as today’s fair value.
Since then, the business has grown substantially.
Sales increased from approximately ₹2,690 crore in FY2024 to approximately ₹3,218 crore in FY2025. Net worth increased from approximately ₹1,006 crore to ₹1,259 crore.
At the same time, FY2025 profitability declined.
Therefore, a current valuation must consider both:
Business growth + lower recent profitability
rather than simply applying the old Tata transaction valuation.
Indicative Valuation Framework
Because Bisleri is privately held and does not have an actively traded equity market, there is no reliable current market price comparable with an NSE/BSE-listed company.
A useful approach is to consider potential P/E or EV/EBITDA ranges.
Using FY2025 PAT of approximately ₹253 crore:
| Illustrative P/E | Implied Equity Value |
|---|---|
| 20x | ₹5,068 Cr |
| 25x | ₹6,335 Cr |
| 30x | ₹7,602 Cr |
| 35x | ₹8,869 Cr |
| 40x | ₹10,136 Cr |
These are illustrative valuation scenarios only, not a fair-value estimate.
A 25x multiple would imply a value broadly around the historical ₹6,000–₹7,000 crore Tata transaction range.
However, a premium multiple would require confidence in:
- Revenue growth
- Margin recovery
- Premiumisation
- Beverage diversification
- International expansion
- Strong cash generation
Is Bisleri Expensive or Attractive?
At a valuation around ₹6,000–₹7,000 crore, the company would trade at approximately:
24–28x FY2025 PAT
based on the ₹253 crore reported PAT.
That is not cheap for a bottled-water business.
However, the company has several characteristics that justify some premium:
- Iconic brand
- Strong distribution
- National reach
- High consumer trust
- Debt-free balance sheet
- High return on equity
- International expansion
- Beverage diversification
The valuation therefore depends heavily on the investor’s confidence in future earnings growth.
Key Growth Drivers
1. Packaged Water Market Growth
India’s organised packaged-water market continues to expand.
2. Premium Water
Vedica and premium formats can increase realisations.
3. Carbonated Beverages
Limonata, POP, Spyci Jeera and other products can expand the addressable market.
4. Distribution Expansion
The company’s large network creates opportunities for greater penetration.
5. Six New Plants
The planned investment in new manufacturing facilities can support future growth.
6. Middle East Expansion
The Apparel Group partnership provides a new international growth platform.
7. Sports Marketing
Sports partnerships can increase brand relevance among younger consumers.
8. Direct-to-Consumer
Home delivery and subscription models can improve consumer retention.
Key Risks
1. No IPO
The company’s current stated intention is to remain private.
2. Unlisted Liquidity
There is no exchange-based liquidity for ordinary shareholders.
3. Margin Pressure
FY2025 operating margin declined from approximately 15.5% to 12.2%.
4. Plastic Regulations
Environmental regulation around PET packaging could increase costs.
5. Counterfeit Products
Management has highlighted counterfeit packaged-water products as a significant challenge to the organised industry and Bisleri’s brand.
6. Competition
Major competitors include:
- Kinley
- Aquafina
- Himalayan
- Regional brands
- Local packaged-water companies
7. Commodity Costs
PET resin, packaging, energy and transportation costs can affect profitability.
8. Diversification Risk
Entering carbonated beverages puts Bisleri into highly competitive categories dominated by large multinational companies.
9. Capital Expenditure Risk
The planned ₹600 crore investment programme needs to generate attractive returns.
10. Family-Controlled Business
The company remains closely controlled by the promoter family, making governance and capital-allocation decisions important to monitor.
Re-rating Triggers
Potential positive triggers include:
- Revenue growth above 15%
- Recovery in operating margins
- Strong growth in Vedica
- Successful launch of new beverages
- Higher premium-product mix
- Successful six-plant expansion
- Strong UAE/Middle East growth
- Increased export contribution
- Improved cash generation
- Greater distribution reach
- Potential change in IPO strategy
Key KPIs to Monitor
Investors should track:
Revenue growth
Operating margin
PAT growth
ROE
ROCE
Plant utilisation
Distribution outlets
Distributor count
Number of operational plants
Premium-water contribution
Carbonated beverage contribution
International revenue
Working-capital days
Advertising expenditure
Free cash flow
Return on incremental capital
Investment Positives
Iconic brand: Bisleri is one of India’s strongest packaged-water brands.
Large distribution network: 5,980 distributors and 8,270 trucks according to the company’s current website.
Manufacturing scale: 130 operational plants provide strong geographic reach.
Strong financial position: FY2025 reported borrowings were nil in Tofler’s financial compilation.
High ROE: FY2025 ROE was approximately 20%.
Revenue growth: Sales increased to approximately ₹3,218 crore in FY2025.
International opportunity: The Apparel Group partnership provides an important Middle East expansion platform.
Product diversification: The company is expanding beyond water into carbonated beverages and premium hydration.
Investment Concerns
No IPO plan: Management has explicitly stated that Bisleri intends to remain private.
Profit decline: FY2025 PAT declined from approximately ₹307 crore to ₹253 crore.
Margin contraction: Operating margin declined to approximately 12.2%.
High valuation uncertainty: There is no transparent market price.
Competition: The beverage industry has powerful multinational competitors.
Plastic-related risks: PET packaging remains a major environmental and regulatory issue.
Liquidity: Unlisted shareholders may face difficulty finding buyers.
Investment View
Bisleri International is an unusual unlisted investment opportunity.
It is not a typical high-growth startup.
It is a mature, profitable consumer franchise with:
Strong brand + large distribution + manufacturing scale + debt-free balance sheet + high consumer trust.
The company’s FY2021–FY2025 revenue trajectory has been impressive, with sales rising from approximately ₹1,133 crore to ₹3,218 crore.
The balance sheet is also a major positive, with approximately ₹1,259 crore of net worth and no reported borrowings in FY2025.
However, the latest year also highlights an important concern:
Revenue grew strongly, but profitability declined.
Therefore, the next phase of the investment story depends on whether the company can convert its large investment programme into higher revenue without sacrificing margins.
The international expansion through Apparel Group is particularly interesting because it can potentially create a second growth engine outside India.
The biggest issue for unlisted investors is the company’s stated intention to remain private.
This means the investment should not be based on an IPO thesis.
Overall Assessment
| Parameter | Assessment |
|---|---|
| Brand Strength | ⭐⭐⭐⭐⭐ |
| Consumer Trust | ⭐⭐⭐⭐⭐ |
| Distribution | ⭐⭐⭐⭐⭐ |
| Manufacturing Network | ⭐⭐⭐⭐⭐ |
| Revenue Growth | ⭐⭐⭐⭐ |
| Profitability | ⭐⭐⭐⭐ |
| Balance Sheet | ⭐⭐⭐⭐⭐ |
| ROE | ⭐⭐⭐⭐ |
| Product Diversification | ⭐⭐⭐⭐ |
| International Opportunity | ⭐⭐⭐⭐ |
| Industry Opportunity | ⭐⭐⭐⭐⭐ |
| Management/Execution | ⭐⭐⭐⭐ |
| Valuation Visibility | ⭐⭐⭐ |
| Unlisted Liquidity | ⭐ |
| IPO Visibility | ⭐ |
| Overall Business Quality | ⭐⭐⭐⭐⭐ |
| Overall Investment Risk | Medium–High |
Conclusion
Bisleri International is one of India’s most recognisable privately held consumer businesses.
The company has built a formidable competitive position through:
Brand recognition
Consumer trust
130 operational plants
5,980 distributors
8,270 distribution trucks
Large retail reach
Premium water
New beverage categories
International expansion
FY2025 revenue reached approximately ₹3,218 crore, while PAT stood at approximately ₹253 crore and net worth reached approximately ₹1,259 crore.
The balance sheet is particularly strong, with no reported borrowings and approximately 20% ROE.
The next stage of the company’s growth could be driven by the planned manufacturing investments, premiumisation, new beverages and expansion into the Middle East and Africa.
The Apparel Group partnership is particularly important because it gives Bisleri a strategic route into the UAE and potentially the wider Middle East and Africa markets.
However, investors should be careful about one major factor:
Bisleri is currently not positioning itself for an IPO.
Management has explicitly stated that it intends to remain privately held.
Therefore, Bisleri should be considered primarily as a high-quality private consumer business, not as an IPO-bound company.
Our view: Bisleri International is a strong-quality unlisted FMCG business with an exceptional brand and distribution moat, but the attractiveness of any unlisted transaction would depend heavily on the actual purchase price, liquidity terms and the ability of the company to restore margin growth.
Disclaimer: This report is for educational and informational purposes only and should not be considered investment advice or a recommendation to buy or sell securities. Bisleri International is privately held and does not have a continuously traded market price. Historical Tata transaction discussions and illustrative valuation scenarios should not be interpreted as current fair value. Investors should independently verify the latest audited financial statements, shareholding, valuation, transaction terms and liquidity before making any investment decision.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
