
Sector: Hospitality Technology / Travel / Hotels & Vacation Rentals
Status: Active & Unlisted — IPO Process Underway
Company: Oravel Stays Limited
Brand / New Corporate Identity: PRISM
Flagship Brand: OYO
CIN: U63090GJ2012PLC107088
Incorporated: 2012
Founder & Group CEO: Ritesh Agarwal
Registered Office: Ahmedabad, Gujarat
Corporate Office: Gurugram, Haryana
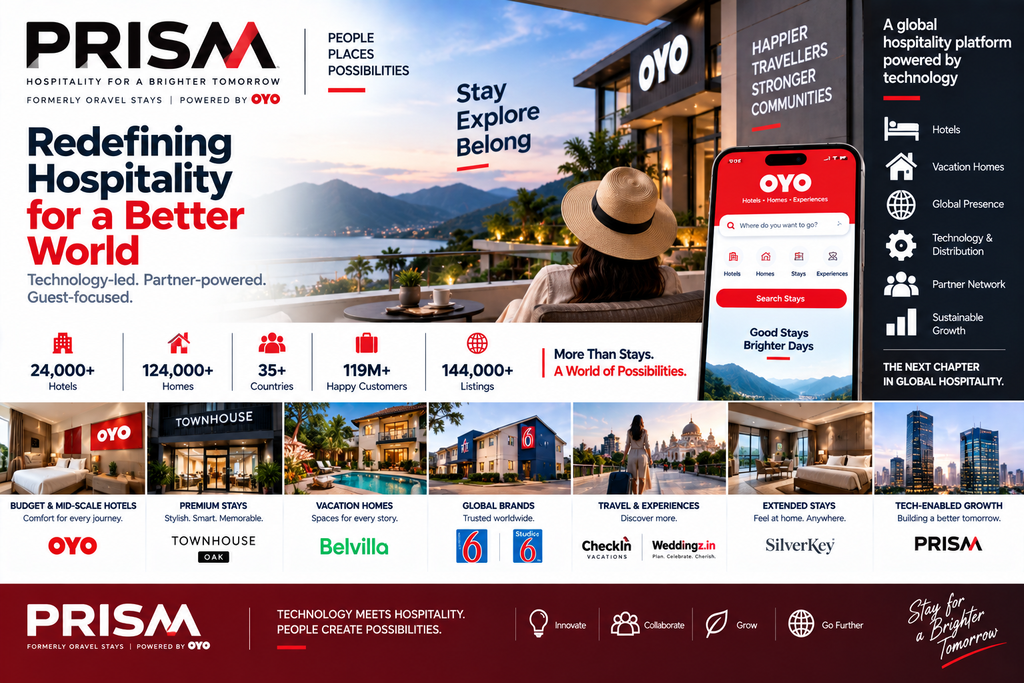
Global Presence: 35+ countries
1. About the Company
PRISM, formerly known as Oravel Stays Limited, is the parent company of OYO and has evolved from an Indian budget-hotel aggregation platform into a global, technology-enabled hospitality company.
The company operates an asset-light technology platform connecting hotel owners, vacation-home operators and other accommodation providers with travellers.
Its technology stack covers:
- Property onboarding
- Distribution
- Booking
- Revenue management
- Dynamic pricing
- Customer acquisition
- Payments
- Customer support
- Partner management
- Analytics
- Procurement
The company has increasingly moved away from the earlier minimum-guarantee-heavy model toward management, franchise and partner-led models, reducing the amount of capital required from the company to expand its network.
PRISM currently operates across more than 35 countries and has built a portfolio of brands spanning economy hotels, premium hotels, vacation homes, extended stays and travel services.
2. OYO → Oravel Stays → PRISM
There is often confusion between the three names.
| Name | Meaning |
|---|---|
| OYO | Flagship consumer-facing hotel/hospitality brand |
| Oravel Stays Limited | Legal corporate entity |
| PRISM | New corporate identity / brand platform |
| PRISM IPO | Proposed IPO of Oravel Stays Limited |
Oravel Stays announced the corporate rebranding to PRISM in September 2025, reflecting the company’s evolution beyond the original OYO hotel-booking business.
Therefore, for UnlistedCart, the security should be presented as:
PRISM (formerly Oravel Stays Limited) — Parent of OYO
3. Business Model
PRISM has evolved into a multi-vertical hospitality platform.
| Vertical | Major Brands / Businesses |
|---|---|
| Economy Hotels | OYO, Collection O, Hotel O, Spot On |
| Premium / Mid-Market Hotels | Townhouse, Townhouse Oak, Palette |
| Luxury | Sunday |
| US Economy Hotels | Motel 6, Studio 6 |
| Vacation Homes | Belvilla, DanCenter |
| Premium Urban Homes | CheckMyGuest |
| Extended Stay | Studio 6, SilverKey |
| Weddings | Weddingz.in |
| Corporate Travel | CheckIn For Business |
| Travel / Holidays | CheckIn Vacations |
| Listings | Hospitality listing/subscription businesses |
The company describes PRISM as a technology platform spanning short stays, extended living, luxury escapes, workspaces, celebration spaces and vacation homes.
4. Global Scale
PRISM has developed a significant international footprint.
As of December 31, 2025, the company reported approximately:
- 24,303 hotels
- 124,668 homes
- 144,583 listings
- 14,937 India storefronts
- Presence across 35+ countries
- 43 brands across its broader ecosystem
The company has also served more than 119 million unique customers since 2012.
The scale is particularly notable because the company operates a common technology backbone from India across multiple international markets.
5. G6 Hospitality — A Major Transformation
One of the most important strategic developments was PRISM’s acquisition of G6 Hospitality in the United States.
G6 operates the:
- Motel 6
- Studio 6
brands.
The acquisition gave PRISM a significant established US hospitality footprint.
In FY26, G6 generated approximately:
₹14,107 Cr Gross Booking Value
compared with approximately ₹3,529 Cr in FY25, reflecting the benefit of its first full year within the group.
PRISM says it integrated G6’s technology stack into its unified platform within approximately one year.
This is strategically important because it demonstrates that PRISM is increasingly becoming a global hospitality technology platform, rather than simply an Indian hotel aggregator.
6. FY26 Financial Performance
FY26 represented a major financial inflection point.
| ₹ Crore | FY25 | FY26 | Growth |
|---|---|---|---|
| Revenue from Operations | 6,253 | 9,358 | +49.7% |
| EBITDA | ~953 | 2,594 | >2x |
| PAT | 245 | 994 | ~4.1x |
| Gross Booking Value | 16,279 | 30,683 | +88.5% |
| Operating Cash Flow | 321 | 2,511 | ~7.8x |
FY26 revenue from operations increased approximately 50%, while GBV nearly doubled.
This is a significant improvement compared with OYO’s historical financial profile.
7. Profitability — The Important Caveat
The headline FY26 PAT of:
₹994 Cr
looks extremely strong.
However, investors need to examine the quality of that profit.
FY26 included approximately:
₹595–678 Cr of deferred-tax benefit/credit
depending on the reporting presentation.
Profit before tax was approximately ₹399 Cr, meaning a substantial portion of the reported PAT came from a tax-related accounting benefit rather than operating earnings.
Therefore:
Reported PAT ≠ Normalised PAT
For valuation purposes, investors should pay more attention to:
EBITDA + operating cash flow + PBT + normalised PAT
rather than simply applying a P/E multiple to ₹994 Cr.
This is one of the most important analytical points in the PRISM story.
8. EBITDA Improvement
The company’s EBITDA increased from approximately:
₹953 Cr → ₹2,594 Cr
between FY25 and FY26.
That represents a dramatic improvement.
The EBITDA margin also expanded materially.
The improvement was supported by:
- G6 acquisition
- Higher business volumes
- Premium hotels
- Company-serviced hotels
- Operating leverage
- Technology integration
- Improved property economics
- Better pricing and revenue management
PRISM’s management has highlighted technology-led operating leverage and centralized operations from India as important drivers.
9. Gross Booking Value
GBV is one of the most important operating metrics for a hospitality marketplace.
FY26:
₹30,683 Cr
versus:
₹16,279 Cr in FY25
representing approximately 88.5% growth.
This growth was driven by:
- G6
- International hotels
- Company-serviced hotels
- Homes
- Higher booking volumes
- Premiumisation
The business is therefore scaling significantly faster than revenue.
10. Operating Cash Flow
This is another major positive.
Operating cash flow increased from:
₹321 Cr in FY25
to:
₹2,511 Cr in FY26
This is a substantial improvement in cash generation.
For a company that historically consumed significant cash, this is an important change in investment quality.
It suggests that the recent profitability improvement is increasingly being supported by actual operating cash generation.
11. India Business
India remains strategically important despite the growing international contribution.
PRISM has been expanding its company-serviced hotel model, where it has greater operational involvement than the traditional asset-light franchise/listing model.
Company-serviced hotel storefronts increased from:
1,053 in March 2025
to:
1,573 by December 2025
This model is being scaled through brands such as:
- Sunday
- Palette
- Clubhouse
- Townhouse
- Townhouse Oak
The company-serviced hotel business generated approximately ₹1,346 Cr GBV in 9M FY26, compared with ₹818 Cr in FY25.
12. International Business
International markets have become a major growth engine.
For the nine months ended December 2025, approximately ₹5,814 Cr of revenue came from overseas markets.
The United States became particularly important following the G6 acquisition.
FY26 further strengthened this trend, with G6 becoming one of the largest contributors to group GBV.
Strategic implication
PRISM is no longer simply:
“India’s budget hotel company.”
It is increasingly:
A global hospitality technology and operating platform built from India.
13. Technology Advantage
PRISM operates a centralized technology ecosystem covering:
- Booking
- Pricing
- Revenue management
- Reservations
- Customer support
- Partner management
- Marketing
- Procurement
- Finance
The company says this technology infrastructure runs across its global asset base.
This creates potential operating leverage because technology developed centrally in India can be deployed across multiple international markets without replicating the entire corporate infrastructure country by country.
14. Competitive Advantages
1. Technology Platform
The company has developed a sophisticated hospitality technology stack over more than a decade.
2. Global Brand Portfolio
The combination of OYO, Motel 6, Studio 6, Belvilla, Townhouse and Sunday provides exposure to different consumer segments.
3. Asset-Light Model
Property owners generally provide much of the physical capital.
4. Global Distribution
PRISM has access to a large global supply network.
5. Revenue Management
Dynamic pricing and technology-led revenue optimisation can improve property-level economics.
6. Centralised Operations
Large parts of technology, finance, customer support and operations are centralized in India.
7. Improving Cash Generation
FY26 operating cash flow of ₹2,511 Cr is a major positive.
15. Shareholding Pattern
The updated IPO documents show the following major shareholders on a fully diluted basis:
| Shareholder | Approx. Stake |
|---|---|
| SVF India Holdings / SoftBank | 40.04% |
| RA Hospitality Holdings | 20.12% |
| Ritesh Agarwal — Direct | 6.59% |
| Oravel Employee Welfare Trust | 5.38% |
| Patient Capital | 3.81% |
| Five Stars Capital | 2.77% |
| Lightspeed | 1.74% |
| A1 Holdings / Grab | 1.62% |
| Airbnb | 1.22% |
| Peak XV Partners | 1.06% |
Promoter group ownership was approximately 66.76% before the IPO.
A particularly important point:
SoftBank and Ritesh Agarwal are NOT selling shares in the proposed IPO.
The proposed issue is structured as a fresh issue rather than an OFS.
16. IPO Status — Major Catalyst
This is one of the strongest parts of the current PRISM story.
PRISM filed its Updated Draft Red Herring Prospectus-I (UDRHP-I) with SEBI on 30 June 2026.
Proposed IPO Size
Up to:
₹6,650 Cr
The IPO is proposed to consist entirely of a fresh issue.
There is currently no OFS component.
The company may also undertake a pre-IPO placement of up to:
₹1,330 Cr
If completed, that amount would reduce the eventual fresh issue size.
17. Use of IPO Proceeds
The largest proposed use of proceeds is debt reduction.
Approximately:
₹4,987.5 Cr
of the IPO proceeds is proposed to be used for repayment/prepayment of borrowings of the Singapore subsidiary.
The balance is intended for general corporate purposes.
Why this matters
This is potentially transformational.
Debt reduction could:
- Reduce interest expense
- Improve PAT
- Strengthen the balance sheet
- Improve credit metrics
- Increase financial flexibility
- Improve future cash generation
PRISM reportedly paid approximately ₹1,414 Cr in interest in FY26, making deleveraging particularly relevant.
18. Current Unlisted Share Price
As of 10 September 2026, current private-market references indicate approximately:
₹24.50/share
with reported recent range of roughly ₹23–₹54 over the past year.
The current indicative market capitalisation based on this reference is approximately:
₹38,881 Cr
according to current unlisted-market data.
Important
This is an indicative OTC/private-market price, not an exchange-traded price.
The actual executable price can vary depending on:
- Quantity
- Seller
- Settlement terms
- Share class
- Transfer conditions
- IPO expectations
- Market demand
Therefore, ₹24.50 should be used as a working valuation reference, not a guaranteed transaction price.
19. Indicative Valuation
At approximately ₹24.50/share and current share count, the implied equity value is approximately:
₹38,900 Cr
Using FY26 reported PAT of ₹994 Cr:
Headline P/E ≈ 39x
However, this P/E is misleading because FY26 PAT benefited substantially from the deferred-tax credit.
Using approximately ₹399 Cr PBT as a rough normalised profitability reference:
Valuation / PBT ≈ 97x
This is not a conventional P/E, but it demonstrates why investors should not simply value PRISM at 39x earnings without adjusting for the tax benefit.
Valuation Snapshot
| Parameter | Approx. |
|---|---|
| Current OTC Reference | ₹24.50 |
| Indicative Market Cap | ~₹38,900 Cr |
| FY26 Revenue | ₹9,358 Cr |
| FY26 EBITDA | ₹2,594 Cr |
| FY26 PAT | ₹994 Cr |
| FY26 PBT | ~₹399 Cr |
| Headline P/E | ~39x |
| Operating Cash Flow | ₹2,511 Cr |
| IPO Size | Up to ₹6,650 Cr |
| Proposed Debt Repayment | ~₹4,987.5 Cr |
20. Historical Valuation Context
OYO’s valuation history has been extremely volatile.
The company had previously targeted a valuation of approximately:
$12 billion
during its earlier IPO attempt.
The current IPO process has been associated with a much lower valuation expectation, with reports indicating approximately $7–8 billion.
This reset is important.
It indicates that the company has moved away from the extremely high-growth, high-burn valuation narrative of 2021 and toward a more conventional:
profitability + cash flow + deleveraging + operating leverage
investment thesis.
21. Investment Positives
1. Major Financial Turnaround
Revenue has grown sharply while EBITDA and cash generation have improved substantially.
2. FY26 Operating Cash Flow
₹2,511 Cr operating cash flow is one of the strongest signals that the business model has matured.
3. Global Scale
35+ countries and more than 174,000 assets on the company’s current platform messaging demonstrate substantial international scale.
4. G6 Acquisition
Motel 6 and Studio 6 provide a large established US footprint and significantly increase PRISM’s global relevance.
5. Strong IPO Catalyst
The UDRHP has been filed with SEBI and the company has moved materially closer to listing.
6. Fresh Capital
Unlike an OFS-heavy IPO, the proposed issue sends the majority of proceeds to the company.
7. Debt Reduction
Nearly ₹5,000 Cr of proposed IPO proceeds could be directed toward debt repayment.
8. Technology-Led Operating Leverage
A centralized platform can potentially scale globally without proportionally increasing corporate overhead.
22. Key Risks
1. Debt
PRISM still carries substantial borrowings, largely related to the G6 acquisition.
Current reports indicate approximately ₹7,810 Cr of borrowings.
2. Interest Cost
FY26 finance costs were approximately ₹1,414 Cr.
Debt repayment is therefore critical to the future earnings profile.
3. Deferred-Tax Benefit
The FY26 ₹994 Cr PAT should not be treated entirely as recurring earnings.
A significant portion of the difference between PBT and PAT came from a deferred-tax credit.
4. International Exposure
International markets now contribute substantially to revenue.
Currency movements, geopolitical issues, tourism cycles, local regulation and macroeconomic conditions can therefore affect results.
5. Hospitality Cyclicality
Travel and hotel demand can weaken during:
- Recessions
- Geopolitical events
- Pandemics
- Airline disruptions
- Economic slowdowns
6. Partner Dependence
The business relies on third-party hotel and property owners.
Failure to maintain partner relationships or adequate supply can affect platform performance.
7. Integration Risk
The company has acquired businesses such as G6 and other international hospitality/home platforms.
Integration, technology migration and operational alignment remain execution risks.
8. Competition
PRISM competes with:
- Booking platforms
- Online travel agencies
- Hotel chains
- Airbnb
- Direct hotel websites
- Regional hospitality platforms
23. What Has Changed in the OYO Story?
The old OYO story was:
Rapid expansion → heavy cash burn → minimum guarantees → losses → restructuring
The current PRISM story is increasingly:
Asset-light platform → management/franchise model → global scale → EBITDA growth → cash generation → debt reduction → IPO
This is a fundamentally different investment proposition.
That transformation is the primary reason PRISM deserves renewed attention.
24. What Investors Should Track
For FY27 and beyond, investors should monitor:
- Revenue growth
- GBV growth
- EBITDA margin
- Normalised PAT
- Operating cash flow
- Debt reduction
- Interest expense
- G6 performance
- India company-serviced hotels
- Homes segment growth
- International revenue
- Customer acquisition costs
- Hotel-owner retention
- IPO price band
- Final IPO valuation
Most Important KPI
Normalised free cash flow after interest and debt reduction.
The company has already demonstrated that it can generate accounting profits.
The next question is whether it can sustainably generate high-quality free cash flow after servicing its debt.
25. Investment View
Global Hospitality Technology Platform — High-Potential Pre-IPO Opportunity
PRISM is one of the more interesting Indian pre-IPO stories because the business has undergone a substantial transformation.
It has moved from being primarily known as an aggressive budget-hotel aggregator to becoming a global technology-enabled hospitality platform with:
OYO + Motel 6 + Studio 6 + Belvilla + Sunday + Townhouse + Palette + vacation homes + corporate travel + technology infrastructure.
FY26 demonstrated strong momentum:
- Revenue: ₹9,358 Cr
- EBITDA: ₹2,594 Cr
- GBV: ₹30,683 Cr
- Operating Cash Flow: ₹2,511 Cr
- Reported PAT: ₹994 Cr
The IPO is also materially more credible than OYO’s earlier attempts because the company is now profitable on an operating basis and generating significant cash.
However, investors must not overlook two issues:
1. FY26 PAT contains a substantial deferred-tax benefit.
2. The company still carries significant debt.
The proposed IPO addresses the second issue directly, with approximately ₹4,987.5 Cr earmarked for debt repayment.
26. Overall Assessment
| Factor | Assessment |
|---|---|
| Business Transformation | ⭐⭐⭐⭐⭐ |
| Revenue Growth | ⭐⭐⭐⭐⭐ |
| EBITDA Growth | ⭐⭐⭐⭐⭐ |
| Global Scale | ⭐⭐⭐⭐⭐ |
| Cash Generation | ⭐⭐⭐⭐⭐ |
| Technology Platform | ⭐⭐⭐⭐ |
| IPO Visibility | ⭐⭐⭐⭐⭐ |
| Balance Sheet | ⭐⭐⭐ |
| Earnings Quality | ⭐⭐⭐ |
| Competitive Moat | ⭐⭐⭐⭐ |
| Current Valuation | ⭐⭐⭐ |
| Liquidity | ⭐⭐ |
| Overall Risk | Medium–High |
27. Final Research View
PRISM is no longer the same OYO that investors saw during the 2021 IPO attempt.
The business has matured significantly.
The strongest evidence is the combination of:
₹9,358 Cr revenue + ₹2,594 Cr EBITDA + ₹2,511 Cr operating cash flow + ₹30,683 Cr GBV.
The proposed ₹6,650 Cr IPO, with nearly ₹5,000 Cr earmarked for debt repayment, could further strengthen the balance sheet and reduce interest costs.
At the current indicative unlisted price of around ₹24.50, the implied valuation is approximately ₹38,900 Cr.
That valuation is not obviously cheap when compared with reported FY26 earnings, particularly because of the deferred-tax benefit. But the valuation becomes more interesting if investors believe:
- EBITDA can continue growing,
- G6 can sustain strong economics,
- debt falls materially after the IPO,
- interest costs decline,
- operating cash flow remains strong,
- and PRISM sustains its global expansion without returning to the old cash-burning model.
Our View
Business Quality: Strong
Growth: Strong
Turnaround: Very Strong
Cash Flow: Strong
IPO Visibility: Very High
Debt: Key concern
Valuation: Reasonable-to-premium depending on IPO pricing
Risk: Medium–High
Long-Term Potential: Attractive
Recommended UnlistedCart Positioning
PRISM (OYO) — Global Hospitality Technology Platform | High-Visibility Pre-IPO Opportunity
This is a much stronger positioning than simply calling it “OYO Unlisted Shares.”
The company has formally filed its UDRHP with SEBI, making the IPO catalyst substantially more concrete than the earlier OYO attempts.
Disclaimer
This report is prepared for research and informational purposes only and does not constitute investment advice, an offer to buy or sell securities, or a guarantee of future returns. Unlisted-share prices are indicative OTC/private-market references and may differ materially from executable transaction prices. IPO filing/SEBI observations do not guarantee a particular IPO date, price or listing valuation. Investors should independently verify the latest UDRHP/RHP, financial statements, capital structure, share availability, transfer restrictions, taxation, debt position and final IPO terms before investing.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
