
Deepak Houseware & Toys Limited
India’s Fast-Growing Toy Manufacturing Story | Import Substitution + Manufacturing Scale + Rapid Profit Growth
Company: Deepak Houseware & Toys Limited
Brand: Urban Tots
Formerly: Deepak Houseware & Toys Private Limited
CIN: U25111RJ2020PLC070129
ISIN: INE0MQ801018
Incorporated: 6 August 2020
Commercial Operations: 2021
Registered Office: Bhiwadi, Rajasthan
Sector: Consumer Discretionary / Toys & Children’s Products
Status: Unlisted
Face Value: ₹1
Promoters: Deepak Chaudhary & Satya Chaudhary
Current Indicative OTC Price: ~₹72–₹85/share
IPO Status: No DRHP filed
About the Company
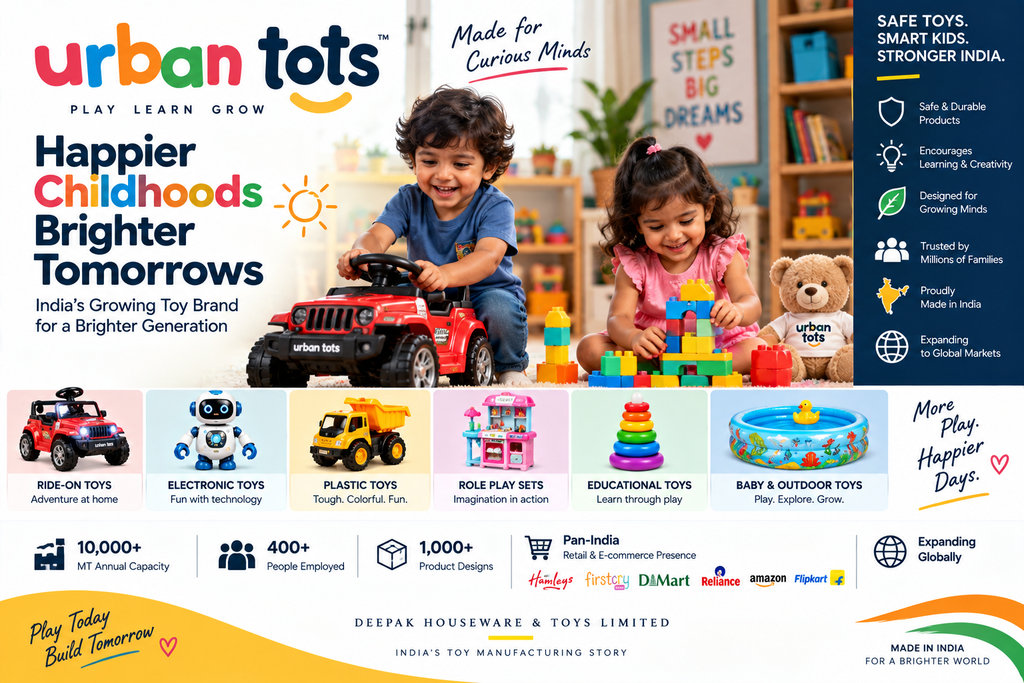
Urban Tots is the consumer-facing brand of Deepak Houseware & Toys Limited, a Rajasthan-based toy manufacturer focused on producing toys in India.
The company manufactures and sells:
- Plastic toys
- Electronic toys
- Battery-operated toys
- Ride-on toys
- Role-play sets
- Educational toys
- Baby pools
- Activity products
- Other children’s products
Its products are distributed through organised retailers and e-commerce platforms, including Hamleys, FirstCry, DMart, Reliance Retail, Flipkart and Amazon, according to company and industry sources.
The company has positioned itself around a simple theme:
Made in India toys for the next generation.
Its long-term objective is to build a large Indian toy manufacturing and consumer brand platform with global ambitions. The company’s website currently states a vision of becoming India’s No. 1 brand with a global presence over the next five years.
Important Corporate Development
Urban Tots was originally incorporated as Deepak Houseware & Toys Private Limited.
During FY24, the company applied to convert into a public company, and the Registrar of Companies issued a fresh Certificate of Incorporation dated 2 May 2024, changing the name to Deepak Houseware & Toys Limited.
This conversion is strategically relevant because it makes the company structurally better positioned for a future capital-market transaction.
However:
⚠️ IPO is NOT confirmed
Current market sources indicate no DRHP has been filed.
Therefore, Urban Tots should currently be presented as an:
Unlisted Growth Company / Potential Future IPO Candidate
—not as a confirmed pre-IPO listing.
Business Model
Urban Tots operates primarily as a manufacturing-led toy company.
The business model can broadly be represented as:
Product Design → Mould Development → Manufacturing → Branding → Distribution → Retail / E-commerce
The company has in-house capabilities around product mould development and also provides OEM/private-label manufacturing solutions.
Major Product Categories
| Category | Products |
|---|---|
| Ride-On Toys | Battery-powered bikes, cars and ride-ons |
| Plastic Toys | Large-format and conventional toys |
| Electronic Toys | Battery-operated and interactive products |
| Role Play | Pretend-play products |
| Educational Toys | Learning-focused products |
| Baby Products | Pools and children’s activity products |
| Outdoor Products | Play and recreational products |
| OEM | Private-label manufacturing |
The company says its catalogue contains 1,000+ products, including ride-ons and educational toys.
Manufacturing Facility
The company’s main manufacturing operation is located in the RIICO Industrial Area, Pathredi, Bhiwadi, Rajasthan.
The facility covers approximately 36,000 square yards, according to company/industry information.
The company’s current website states:
- 10,000+ metric tonnes annual production capacity
- 400+ employees
- 60+ machines referenced in market/company material
- Dedicated capabilities for toy manufacturing
- OEM/private-label production
This manufacturing scale is one of the most important elements of the investment thesis.
Customer & Distribution Network
Urban Tots has developed a broad distribution network.
Modern Retail
Products are available through retailers such as:
- Hamleys
- FirstCry
- DMart
- Reliance Retail
E-Commerce
The company also sells through:
- Amazon
- Flipkart
- Other online channels
This combination gives Urban Tots exposure to both organised physical retail and India’s rapidly expanding e-commerce market.
Product Expansion Strategy
Urban Tots has indicated plans to expand beyond its current plastic/electronic toy base.
Potential new categories include:
Wooden Toys
The company has discussed developing dedicated wooden-toy production capabilities.
Metallic Toys
It has also discussed entering metallic toys.
This is strategically important because expanding materials and product categories can:
- Increase average selling price
- Reduce dependence on a single material
- Broaden customer segments
- Increase product differentiation
- Improve export opportunities
FY25 Financial Performance
FY25 was another year of extremely strong growth.
Financial Snapshot
₹ Crore
| Particular | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue from Operations | 49.15 | 78.82 | 124.79 |
| Total Income | 49.70 | 79.51 | 125.29 |
| EBITDA* | ~7.97 | ~12.01 | ~19.94 |
| PBT | 4.98 | 8.23 | 13.70 |
| PAT | 4.18 | 7.10 | 11.31 |
| EPS | ₹0.76–0.80 | ₹1.28 | ₹2.03 |
*EBITDA approximated from reported profit before depreciation, finance costs, exceptional items and tax.
The FY25 audited annual report reports revenue of ₹124.79 crore, PBT of ₹13.70 crore and PAT of ₹11.31 crore.
Revenue Growth
Revenue has increased dramatically:
FY23: ₹49.15 Cr
↓
FY24: ₹78.82 Cr
↓
FY25: ₹124.79 Cr
FY24 growth:
~60.4%
FY25 growth:
~58.3%
This represents approximately 59% revenue CAGR from FY23 to FY25.
For a manufacturing company operating in the toy sector, this is a very strong growth trajectory.
Profit Growth
PAT:
FY23: ₹4.18 Cr
↓
FY24: ₹7.10 Cr
↓
FY25: ₹11.31 Cr
FY25 PAT growth:
~59.3%
PBT increased from ₹8.23 crore to ₹13.70 crore:
~66.6% growth
The company’s own annual report highlights the 66.6% increase in PBT.
Margin Profile
FY25:
Revenue: ₹124.79 Cr
Profit Before Tax: ₹13.70 Cr
PAT: ₹11.31 Cr
Approximate margins:
PBT Margin: ~11.0%
PAT Margin: ~9.1%
The company has therefore managed to maintain a healthy net margin despite its rapid expansion.
Cash Flow
One area investors should examine carefully is working capital.
FY25 operating cash flow:
₹9.50 Cr
versus:
₹4.44 Cr in FY24
Operating cash flow therefore more than doubled.
However, the company simultaneously invested heavily in capacity.
FY25 investing cash flow:
-₹13.81 Cr
primarily because of approximately ₹14.00 crore of fixed-asset purchases.
This indicates that Urban Tots is still in a growth + capacity-building phase rather than a mature cash-harvesting phase.
Balance Sheet
FY25
| Particular | Amount |
|---|---|
| Total Assets | ₹112.78 Cr |
| Net Worth | ₹46.38 Cr |
| Long-Term Borrowings | ₹10.00 Cr |
| Short-Term Borrowings | ₹25.18 Cr |
| Total Debt | ₹35.17 Cr |
| Trade Receivables | ₹36.23 Cr |
| Inventory | ₹16.43 Cr |
| Cash & Equivalents | ₹0.25 Cr |
| Trade Payables | ₹25.69 Cr |
The company had approximately ₹46.38 crore of shareholders’ funds against ₹35.17 crore of total debt, producing a reported debt-equity ratio of approximately 0.76x.
Working Capital — Important Risk
Trade receivables increased sharply:
FY24: ₹20.32 Cr
FY25: ₹36.23 Cr
while revenue increased from ₹78.82 crore to ₹124.79 crore.
The company reported a trade-receivables turnover ratio of 4.41x in FY25 versus 4.97x in FY24.
This is something investors should monitor as the company scales.
Why?
Rapid sales growth can look excellent in the P&L while cash gets locked up in:
Receivables + Inventory
Urban Tots has improved operating cash flow, but continued growth will require disciplined working-capital management.
Return Ratios
FY25:
ROE: ~24%
ROCE: ~20%
Both improved from FY24.
The company reported ROE of 24% and ROCE of 20% for FY25.
This is an encouraging sign because the business is generating meaningful returns on the capital invested into the manufacturing platform.
Shareholding Pattern
The FY25 audited annual report shows:
| Shareholder | Holding |
|---|---|
| Deepak Chaudhary | 47.86% |
| Satya Chaudhary | 31.92% |
| Other Shareholders | ~20.22% |
Combined promoter holding:
~79.78%
Some current private-market databases show slightly different promoter percentages, so the latest depository/company records should be used for a transaction-level cap table.
Capital Raise / Private Placement
During FY25, shareholders approved a proposal to issue 6 lakh equity shares at ₹90 per share, including ₹89 premium, through preferential/private placement.
However, the FY25 annual report states that the paid-up share capital had not increased by year-end, so this should not be treated as completed capital issuance in the FY25 financial statements.
This distinction is important when calculating current market capitalisation and dilution.
Current Unlisted Share Price
As of 12 September 2026, current OTC references vary significantly.
Recent references:
₹72.33 — Moneycontrol
₹76 — BuyUnlistedShares
₹85 — Planify
These are private-market/OTC indicative references, not exchange-traded prices.
⚠️ Important
Because the quoted prices differ materially, investors should not treat ₹85 as the universally executable market price.
For valuation purposes, a reasonable current reference range is:
₹72–₹85/share
until an actual transaction price is verified.
Indicative Market Capitalisation
Using FY25 audited shares outstanding:
5.572 crore shares
At ₹72.33:
≈ ₹403 Cr
At ₹76:
≈ ₹423 Cr
At ₹85:
≈ ₹474 Cr
This broadly aligns with the private-market databases showing market capitalisation around ₹404–423 crore at their respective quoted prices.
Valuation
FY25 EPS:
₹2.03
Therefore:
| Price | Approx. P/E |
|---|---|
| ₹72.33 | ~35.6x |
| ₹76 | ~37.4x |
| ₹85 | ~41.9x |
At the current range, Urban Tots is therefore not a cheap stock on trailing earnings.
The market is already assigning a meaningful growth premium.
Price-to-Book
FY25 book value:
~₹8.32/share
At ₹76:
P/B ≈ 9.1x
At ₹85:
P/B ≈ 10.2x
This means the investment case depends heavily on future earnings growth, not current asset value.
Why Is the Market Giving a Premium Valuation?
There are several reasons.
1. Very High Revenue Growth
~59% CAGR from FY23–FY25.
2. Strong PAT Growth
~65% CAGR from FY23–FY25.
3. India’s Toy Manufacturing Opportunity
India is actively trying to develop domestic manufacturing and reduce dependence on imported toys.
4. Large Manufacturing Platform
10,000+ metric-ton annual capacity according to the company’s current website.
5. Strong Distribution
Presence across modern retail and e-commerce.
6. Product Expansion
Potential entry into wooden and metallic toys.
7. Potential IPO
Conversion into a public company provides structural readiness for a future IPO, although no DRHP has been filed.
Government & Industry Tailwinds
India’s toy industry has benefited from a broader policy push toward domestic manufacturing.
The structural themes include:
- Import substitution
- Make in India
- Manufacturing incentives
- Quality standards
- Rising disposable income
- Organised retail
- E-commerce
- Export potential
- Increasing demand for branded toys
Urban Tots is positioned directly within these themes.
Investment Positives
| Positive | Why It Matters |
|---|---|
| ~59% Revenue CAGR | Extremely strong recent growth |
| ~65% PAT CAGR | Profit growth broadly keeping pace |
| ₹125 Cr Revenue | Meaningful scale achieved quickly |
| ₹11.3 Cr PAT | Profitable growth model |
| 24% ROE | Strong capital efficiency |
| 20% ROCE | Good operating returns |
| 10,000+ MT Capacity | Significant manufacturing scale |
| 400+ Employees | Established operating platform |
| Modern Retail | Hamleys, FirstCry, DMart, Reliance |
| E-commerce | Amazon, Flipkart and others |
| Product Diversification | Plastic, electronic, ride-ons, educational |
| OEM Capability | Additional manufacturing revenue opportunity |
| Domestic Manufacturing Theme | Benefits from import-substitution trend |
| Future Category Expansion | Wooden + metallic toys |
| Promoter Ownership | ~80% promoter holding |
| Potential IPO | Public-company structure already established |
Key Risks / Concerns
1. Valuation
At ₹72–₹85, the stock trades at approximately 36–42x FY25 earnings.
A lot of future growth is already reflected in the price.
2. Working Capital
Receivables increased sharply to ₹36.2 crore.
As the company grows, working-capital requirements could become increasingly important.
3. Debt
Debt-equity of approximately 0.76x is manageable but not insignificant for a relatively young company.
4. Capital Expenditure
FY25 investing cash flow was negative ₹13.8 crore because of substantial fixed-asset investment.
Continued expansion could require additional debt/equity capital.
5. Customer Concentration
Large organised retailers can provide scale but may also exert pressure on pricing, payment terms and working capital.
6. Competition
The Indian toy market includes:
- Large multinational brands
- Established Indian manufacturers
- Chinese imports
- Numerous regional manufacturers
- New D2C brands
7. Consumer Preferences
Toy demand is highly dependent on trends, characters, entertainment franchises and changing children’s preferences.
8. Raw Material Risk
Plastic and other input prices can affect gross margins.
9. Unlisted Liquidity
Selling shares can take time and OTC prices may differ substantially between buyers and sellers.
10. IPO Uncertainty
An IPO should not be assumed until the company actually files regulatory documents.
What Could Drive Future Growth?
1. Capacity Expansion
More manufacturing capacity could support continued revenue growth.
2. Product Diversification
Wooden and metallic toys could increase addressable market.
3. Export Growth
A larger Indian manufacturing platform could support exports.
4. Private Label / OEM
Manufacturing for established retailers and brands can provide additional volume.
5. E-Commerce
Online toy penetration remains a major growth opportunity.
6. Organised Retail
Expansion with large retail chains can increase distribution significantly.
7. Urban Tots Brand
Building Urban Tots into a recognised consumer brand could eventually improve margins versus being purely a contract manufacturer.
IPO Status
Potential Future IPO — Not Confirmed
The company converted from private limited to limited status in May 2024, which is structurally consistent with preparing for a larger capital-market journey.
However:
DRHP: Not Filed
Therefore:
IPO = Potential catalyst, not current fact.
Investors should not pay a premium solely because an intermediary describes Urban Tots as a “pre-IPO” company.
Key Metrics to Monitor
| KPI | FY25 |
|---|---|
| Revenue | ₹124.79 Cr |
| Revenue Growth | ~58% |
| PAT | ₹11.31 Cr |
| PAT Growth | ~59% |
| PBT | ₹13.70 Cr |
| PBT Growth | ~67% |
| EPS | ₹2.03 |
| ROE | ~24% |
| ROCE | ~20% |
| Debt/Equity | ~0.76x |
| Operating Cash Flow | ₹9.50 Cr |
| Trade Receivables | ₹36.23 Cr |
| Inventory | ₹16.43 Cr |
| Net Worth | ₹46.38 Cr |
| Shares | 5.572 Cr |
| Current OTC Reference | ₹72–₹85 |
| Indicative Market Cap | ₹403–474 Cr |
| Indicative FY25 P/E | ~36–42x |
Investment View
Urban Tots — High-Growth Indian Toy Manufacturing Opportunity
Urban Tots is one of the more interesting emerging names in India’s toy-manufacturing ecosystem.
The company has achieved something meaningful in a relatively short period:
₹49 Cr revenue in FY23 → ₹79 Cr in FY24 → ₹125 Cr in FY25
while PAT increased:
₹4.2 Cr → ₹7.1 Cr → ₹11.3 Cr
The growth is supported by a tangible manufacturing base, organised retail distribution, e-commerce presence and the broader shift toward domestic toy manufacturing.
The company is also expanding its manufacturing capabilities and product portfolio, while maintaining healthy return ratios.
But there is one major catch:
The valuation is no longer cheap.
At ₹72–₹85, the company trades around 36–42x FY25 earnings.
Therefore, the future investment return will depend on Urban Tots continuing to deliver strong double-digit/high-growth earnings for several years.
Our Classification
Business Quality: ⭐⭐⭐⭐
Revenue Growth: ⭐⭐⭐⭐⭐
Profit Growth: ⭐⭐⭐⭐⭐
Manufacturing Capability: ⭐⭐⭐⭐½
Industry Tailwinds: ⭐⭐⭐⭐½
Balance Sheet: ⭐⭐⭐½
Cash Flow: ⭐⭐⭐
Valuation: ⭐⭐⭐
Liquidity: ⭐⭐
Overall Risk: 🟠 High
UnlistedCart View: HIGH-GROWTH STORY — VALUATION DISCIPLINE REQUIRED
Urban Tots is best viewed as a growth-at-a-reasonable-price only if earnings growth remains exceptionally strong.
The company has the ingredients for a compelling long-term story:
Indian manufacturing + toy industry growth + strong distribution + rapid revenue growth + profitable operations + capacity expansion + potential IPO.
But investors should not ignore the valuation.
At ~40x FY25 earnings, the market is already expecting significant future growth.
Bottom Line
Urban Tots has evolved from a relatively small toy manufacturer into a business generating ₹125 crore+ annual revenue and ₹11 crore+ PAT, with approximately ₹9.5 crore of operating cash flow and a growing manufacturing footprint.
The company’s biggest opportunity is to become a scaled Indian toy manufacturing and consumer brand platform, benefiting from domestic manufacturing, organised retail, e-commerce and export opportunities.
The biggest question for investors is no longer:
“Can Urban Tots grow?”
The historical numbers suggest that it can.
The more important question is:
“Can Urban Tots sustain high growth long enough to justify a 36–42x earnings valuation?”
That is where the investment decision becomes interesting.
UnlistedCart Positioning:
Indian Toy Manufacturing Growth Story — High Growth, Strong Execution & Potential Future IPO
Risk: High
Liquidity: Low
IPO: Potential, not confirmed
Primary Thesis: Earnings growth + manufacturing scale + Indian toy industry expansion
Disclaimer
This report is for informational and research purposes only and does not constitute investment advice, an offer, solicitation or recommendation to buy or sell securities. Urban Tots shares are unlisted and OTC/private-market prices are indicative only; different platforms currently show materially different reference prices. Investors should independently verify the latest financial statements, share capital, depository records, transferability, taxation, liabilities and any future IPO filings before making an investment decision.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
