
Sector: Renewable Energy / Solar EPC / Independent Power Producer
Status: Unlisted
Headquarters: Jaipur, Rajasthan
CIN: U40108RJ2015PLC048401
Founded: 2015
Business Model: Solar EPC + IPP/RESCO + Solar Projects
Face Value: ₹10 per share based on the company’s IPO documents
1. Company Overview
Solar91 Cleantech Limited is an Indian renewable-energy company focused primarily on solar power solutions for commercial and industrial customers.
The company was incorporated in 2015 as Solar91 Cleantech Private Limited and was converted into a public limited company in July 2024. Its principal business has historically been solar Engineering, Procurement and Construction (EPC), while it has also been expanding into the Independent Power Producer (IPP) model.
Under the EPC model, Solar91 designs, procures equipment for, constructs and maintains solar projects for customers. Under the IPP model, the company develops solar projects through subsidiaries/SPVs and generates recurring revenue by selling electricity under long-term Power Purchase Agreements (PPAs).
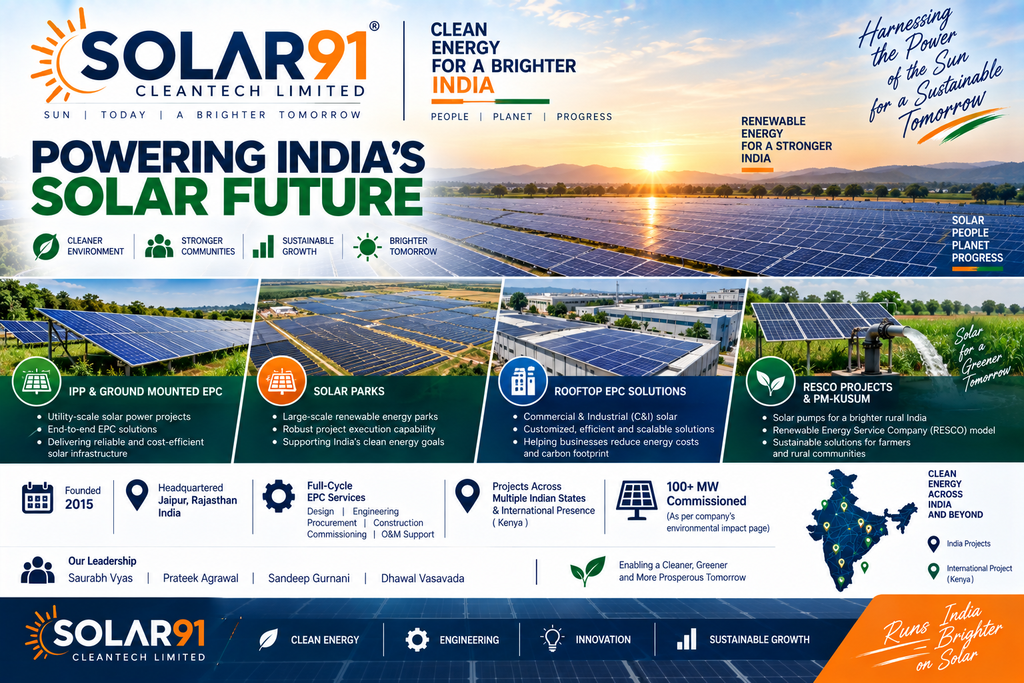
The company’s current website describes its activities across IPP and ground-mounted EPC, solar parks, rooftop EPC and RESCO projects.
2. Business Model
A. Solar EPC
Solar91 provides end-to-end solar EPC services, including:
- Project design and engineering
- Procurement of solar modules and other equipment
- Project construction
- Grid connection
- Commissioning
- Operation and maintenance
The company has historically focused on Commercial & Industrial customers, including sectors such as agro-processing and textiles. Its DRHP stated that it had commissioned 191 plants across 13 Indian states and one project in Kenya as of the document date.
B. Independent Power Producer
The IPP model is strategically important because it can create recurring electricity-sale revenue rather than one-time EPC revenue.
Solar91 creates project-specific SPVs/subsidiaries that develop solar assets and enter into PPAs with electricity distribution companies or other customers.
The company had commissioned two IPP projects at the time of its DRHP.
C. RESCO Projects
Under the RESCO model, the developer finances and operates the solar asset while the customer purchases the generated electricity.
This model can provide longer-duration revenue visibility but requires substantially more capital than conventional EPC.
3. Solar91’s Project Footprint
Solar91 has gradually expanded beyond conventional rooftop EPC into larger ground-mounted and IPP projects.
The company’s website currently highlights:
- Ground-mounted solar projects
- Rooftop solar
- Solar parks
- RESCO projects
- PM-KUSUM-related solar opportunities
The company also states that it has commissioned 180+ MW of solar plants, while its green-impact page says that more than 100 MW had been commissioned over its first eight years. The difference likely reflects subsequent project additions and changes in the company’s reporting period.
4. Financial Performance
Consolidated Financial Snapshot
| ₹ Crore | FY22 | FY23 | FY24 | FY25 |
|---|---|---|---|---|
| Revenue from Operations | 41.57 | 37.58 | 42.77 | 82.19 |
| Total Income | 42.01 | ~37.8 | 42.97 | 82.81 |
| EBITDA | ~0.61 | ~0.83 | 3.85 | ~11.7 |
| PBT | 0.46 | ~0.30 | 3.14 | 11.29 |
| PAT | 0.34 | 0.20 | 2.33 | 5.70 |
| Operating Cash Flow | -3.75 | -3.34 | 3.97 | -8.19 |
FY24 figures are consistent with the company’s IPO documents, which reported revenue of ₹42.77 crore, EBITDA of ₹3.85 crore and PAT of ₹2.33 crore.
FY25 revenue increased to approximately ₹82.19 crore, while PAT increased to approximately ₹5.70 crore.
Revenue Growth
Revenue increased approximately 92% YoY in FY25.
This is a significant acceleration compared with the relatively flat revenue base of FY22–FY24.
However, investors should distinguish between revenue growth and cash generation because operating cash flow turned negative in FY25.
5. Profitability
Solar91’s profitability has improved substantially from the low-margin period of FY22–FY23.
FY24:
- EBITDA: ~₹3.85 crore
- EBITDA margin: ~9%
- PAT: ~₹2.33 crore
- ROE: ~49.5%
FY25:
- PBT: ~₹11.29 crore
- PAT: ~₹5.70 crore
- PAT margin: ~6.9%
The IPO documents show that FY24 EBITDA had increased sharply from ₹0.83 crore in FY23 to ₹3.85 crore, while PAT increased from ₹0.20 crore to ₹2.33 crore.
6. Cash Flow – Important Area to Monitor
The biggest financial point that deserves attention is the difference between accounting profit and operating cash flow.
FY25 operating cash flow was approximately:
₹(8.19) crore
compared with approximately ₹3.97 crore positive CFO in FY24.
The FY25 cash-flow commentary attributes the deterioration largely to working-capital absorption, including increases in inventory and trade receivables.
For an EPC business, this is important because rapid project growth can require substantial working capital before customer collections are received.
Therefore:
Revenue growth → positive
Profit growth → positive
Operating cash conversion → requires monitoring
7. Balance-Sheet & Capital Requirements
Solar EPC and IPP businesses have different capital characteristics.
The EPC business primarily requires working capital for:
- Inventory
- Project execution
- Customer receivables
- Vendor payments
The IPP/RESCO model requires much larger capital investment because Solar91 has to finance the solar asset and recover the investment through electricity sales over several years.
The company’s FY25 cash-flow statement shows significant financing activity, including approximately ₹67 crore of borrowings and ₹15 crore of share-capital issuance during the year.
This indicates that expansion is increasingly dependent on external capital.
8. IPO History
Solar91 filed a Draft Red Herring Prospectus for a proposed SME IPO.
The proposed issue consisted of:
Fresh Issue: 54.36 lakh equity shares
Proposed Issue Size: approximately ₹106 crore
Price Band: ₹185–₹195 per share
Face Value: ₹10
Proposed Exchange: BSE SME
The proceeds were proposed to be used primarily for:
- Investment in subsidiary
- Working capital requirements
- General corporate purposes
However, the proposed IPO was postponed in December 2024 after BSE indicated that further examination was required following questions raised in the media/complaints.
Consequently, the old ₹185–₹195 IPO price should not be treated as the current fair value or current market price.
9. Current Unlisted Share Price
Current unlisted-market indications vary by intermediary.
One unlisted-share platform reported:
Indicative price: ₹468 per share as of 19 September 2026.
Another intermediary reported approximately:
₹463.32 as of 12 September 2026.
Moneycontrol’s unlisted-share page displayed a materially different indicative figure of ₹596.50, illustrating the lack of a centralized exchange price for Solar91.
Therefore, a practical reference range from the sources checked is approximately:
₹460–₹600 per share
rather than a single precise market price.
These are indicative OTC/unlisted quotations, not NSE/BSE traded prices.
10. Indicative Valuation
FY25 reported EPS was approximately ₹3.91 on the current consolidated financial presentation.
At an indicative price of ₹468:
Approximate P/E = ₹468 ÷ ₹3.91 ≈ 120x
This is substantially above the valuation multiples at which many mature conventional EPC businesses trade.
However, the comparison is not straightforward because Solar91 is attempting to transition toward an IPP/RESCO model, where future earnings could potentially contain a greater recurring component.
The valuation therefore appears to incorporate expectations of significant future growth rather than simply reflecting FY25 earnings.
11. IPO Valuation vs Current Unlisted Valuation
The proposed IPO price band was:
₹185–₹195
Current indicative OTC quotations around:
₹460–₹600
represent a substantial premium to the proposed IPO range.
But this should not automatically be interpreted as a fundamental re-rating.
Several things have changed since the IPO documents:
- FY25 revenue has increased materially
- FY25 earnings have increased
- Solar91 has expanded its project portfolio
- The company is pursuing larger IPP/RESCO opportunities
- Working-capital requirements have increased
- The IPO has not yet taken place
The key question is therefore whether future earnings and cash flows can grow sufficiently to support the current unlisted valuation.
12. Growth Drivers
1. India’s Solar Capacity Expansion
India’s long-term renewable-energy expansion provides a large addressable market for EPC companies and solar developers.
Solar91’s business is positioned toward commercial, industrial and distributed solar applications.
2. C&I Solar
Commercial and industrial consumers increasingly use captive and third-party renewable power to reduce electricity costs and improve renewable-energy usage.
This provides an addressable market for rooftop, ground-mounted and RESCO projects.
3. IPP Transition
Moving from pure EPC toward IPP can potentially increase the proportion of recurring revenue.
The trade-off is that the company must invest considerably more capital upfront.
4. PM-KUSUM
Solar91 participates in PM-KUSUM-related solar projects, including solar pumps and distributed solar installations. The company’s website describes PM-KUSUM as a major opportunity and highlights its EPC role in the programme.
5. BESS / Solar + Storage
Solar91 has also appeared among bidders/winners associated with solar-plus-storage and standalone battery-storage opportunities, including a GUVNL tender referenced in an NSE filing.
This could provide an additional growth avenue beyond conventional solar EPC.
13. Competitive Landscape
Solar91 operates in a competitive renewable-energy ecosystem.
Relevant listed/industry peers cited in its own IPO documents included:
- Oriana Power Limited
- Waaree Renewable Technologies Limited
The company itself cautioned in its IPO documents that these businesses are not strictly comparable, although they were included for broader industry comparison.
Other competitors can include larger EPC contractors, renewable developers, rooftop solar companies and regional EPC players.
14. Key Risks
Working-Capital Risk
The FY25 negative operating cash flow despite higher profits is a key issue to monitor.
Capital Intensity
The shift toward IPP and RESCO requires significantly more capital than conventional EPC.
Customer & Project Concentration
Large projects can cause revenue to fluctuate depending on project awards, execution and commissioning schedules.
Margin Pressure
Solar EPC is competitive and margins can be affected by:
- Module prices
- Commodity prices
- Labour costs
- Financing costs
- Competitive bidding
- Project delays
Debt & Financing Risk
Greater reliance on borrowings to fund expansion can increase interest costs and balance-sheet risk.
Regulatory Risk
Solar projects are influenced by:
- Government policy
- Net-metering regulations
- Open-access rules
- Electricity tariffs
- DISCOM financial health
- Renewable-energy procurement policies
IPO Uncertainty
Solar91’s earlier IPO was postponed, so investors should not assume that an eventual listing will occur on the original timeline or at the earlier proposed valuation.
15. What to Monitor Before Buying Unlisted Shares
For Solar91, I would track these numbers every year:
| Metric | Why it matters |
|---|---|
| Revenue growth | Measures project execution |
| EBITDA margin | Shows EPC profitability |
| PAT growth | Measures earnings scalability |
| Operating cash flow | Tests quality of earnings |
| Receivables | Indicates collection risk |
| Inventory | Indicates working-capital intensity |
| Net debt | Measures financial leverage |
| IPP capacity | Determines recurring revenue potential |
| PPA tenure | Determines revenue visibility |
| ROCE | Measures capital efficiency |
| IPO progress | Determines future liquidity |
| Share dilution | Important for per-share value |
16. Investment Perspective
Solar91 presents a combination of high revenue growth, improving profitability and a transition from EPC toward IPP/RESCO.
The FY25 numbers show a clear improvement in scale:
Revenue: ₹42.77 Cr → ₹82.19 Cr
PAT: ₹2.33 Cr → ₹5.70 Cr
However, the company’s FY25 operating cash flow of approximately ₹(8.19) crore demonstrates that growth is consuming working capital.
At current unlisted quotations around ₹460–₹600, the valuation is substantially higher than the proposed 2024 IPO price band and implies a high earnings multiple on FY25 profits.
Therefore, the central valuation question is not simply whether Solar91 can grow revenue. It is whether the company can:
grow revenue → maintain margins → convert profits into cash → scale IPP assets → generate attractive ROCE.
The transition toward IPP/RESCO could materially change the company’s earnings profile, but it also increases capital requirements and execution risk.
17. Corporate Details
Company: Solar91 Cleantech Limited
CIN: U40108RJ2015PLC048401
Registered Office: D-802, Sector-5, Malviya Nagar, Jaipur, Rajasthan – 302017
Website: Solar91 Cleantech – Official Website
Investor Relations: Solar91 Investor Relations
Annual Reports: Solar91 Annual Reports
DRHP/RHP: Solar91 IPO Documents
18. Conclusion
Solar91 Cleantech is a renewable-energy company that has evolved from a relatively small solar EPC player toward a broader EPC + IPP + RESCO business model.
Its FY25 performance shows substantial revenue and profit growth, while its expanding IPP strategy could provide recurring electricity-sale revenue in the future.
At the same time, the current unlisted valuation requires careful consideration because the shares are being quoted at a significant premium to the previously proposed IPO price range, while FY25 operating cash flow was negative.
The key factors for future value creation will be sustainable earnings growth, working-capital discipline, successful IPP execution, cash-flow conversion and eventual improvement in liquidity through a successful listing or other capital-market event.
Disclaimer
This report is for educational and informational purposes only. It is not investment advice or a recommendation to buy, sell or hold Solar91 Cleantech Limited shares.
Solar91 Cleantech Limited is currently unlisted, and unlisted-share prices are indicative OTC quotations rather than exchange-traded prices. Such quotations may differ materially between intermediaries and may have limited liquidity.
Financial figures should be cross-checked against the company’s latest audited financial statements and regulatory filings before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
