
Business & Unlisted/Thinly Traded Share Analysis
Company: The Ramaraju Surgical Cotton Mills Limited
Incorporated: 20 February 1939
CIN: L17111TN1939PLC002302
ISIN: INE328E01027
Registered Office: Rajapalayam, Tamil Nadu
Exchange Status: Listed on Metropolitan Stock Exchange of India (MSEI) under RAMARAJU; not listed on NSE/BSE. The shares are described by unlisted-share platforms as “listed but not traded.”
Face Value: ₹10 per share
Promoter Holding: 54.69% as of June 2026.
Group: Ramco Group
Management: P.R. Venketrama Raja – Chairman; Nalina Ramalakshmi and N.R.K. Ramkumar Raja – Managing Directors.
Official Website: Ramaraju Surgical Cotton Mills
1. Company Overview
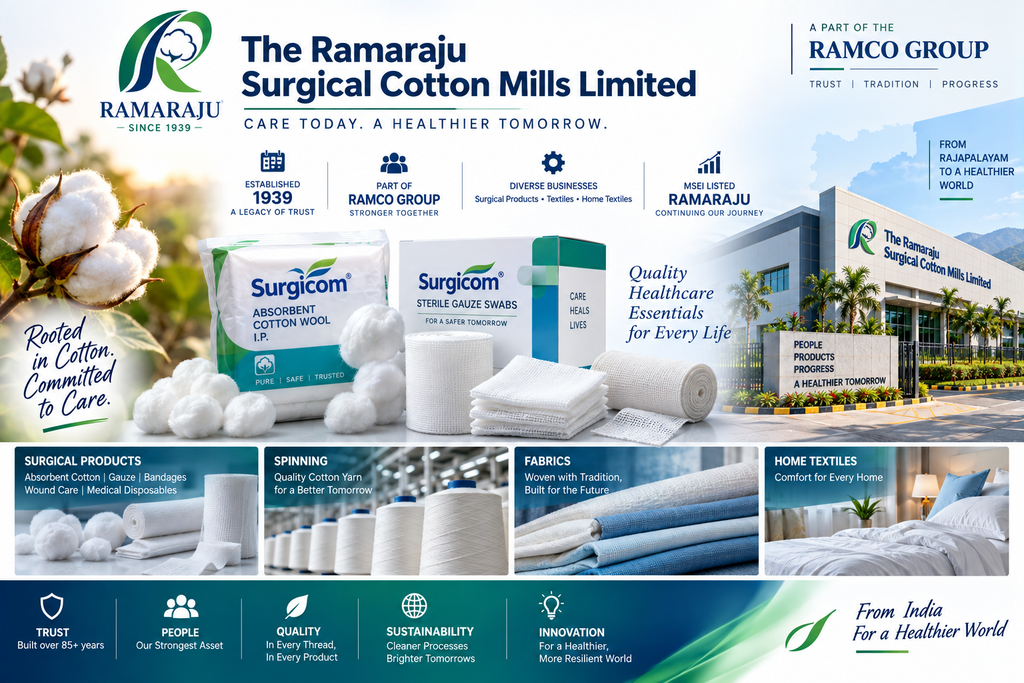
The Ramaraju Surgical Cotton Mills Limited was established in 1939 in Rajapalayam, Tamil Nadu and is part of the Ramco Group. The company originally focused on absorbent cotton and surgical products and subsequently diversified into cotton spinning, weaving, fabrics and home textiles.
Today, the company operates through three principal businesses:
- Surgical Products – Surgicom
- Spinning – Sudarsanam Spinning Mills
- Fabrics & Home Textiles – Sudarsanam Fabrics
It also has wind and solar power assets primarily supporting captive power requirements.
The company states that it offers more than 200 products and has a workforce of around 2,200 employees.
2. What Does Ramaraju Surgical Make?
A. Surgical & Medical Products
The Surgicom division manufactures medical and wound-care products including:
- Absorbent cotton wool
- Cotton balls
- Absorbent gauze
- Gauze swabs
- Roller bandages
- Sterile dressing pads
- Mopping pads
- Eye pads
- Cotton gauze pads
- Plaster of Paris
- Custom medical-grade cotton products
The company’s products are supplied to hospitals, pharmacies and consumers.
The company had installed capacity of approximately 805 MT of medical-grade bleached cotton and around 5.85 million sq. metres of bandage and gauze products as of December 2023.
B. Spinning
The company manufactures:
- Ring-spun cotton yarn
- Open-end yarn
- Combed and carded yarn
- Compact and normal yarn
- Single and multi-ply yarn
- Yarn for weaving and knitting
The company states that it produces nearly 400 tonnes of superfine ring-spun yarn and about 400 tonnes of open-end yarn per month.
C. Fabrics & Home Textiles
The textile division produces:
- Bed linen
- Shirting fabrics
- Jacquard fabrics
- Medical-grade gauze fabric
- Greige fabrics
- Home-textile products
The company has invested in wider-width weaving, sizing and warping capabilities to cater to export-oriented home-textile customers.
3. Manufacturing Footprint
The company’s surgical manufacturing facilities are located at Rajapalayam and Perumalpatti in Tamil Nadu.
Its textile operations are spread across:
- Rajapalayam
- Subramaniapuram
- Perumalpatti
- Thirumalagiri Village, Andhra Pradesh
The company also operates wind-power facilities and solar capacity for captive consumption.
4. FY2026 Financial Performance
Consolidated Financials
| Particulars | FY2025 | FY2026 |
|---|---|---|
| Revenue from Operations | ₹401.09 Cr | ₹498.80 Cr |
| Other Income | ₹5.03 Cr | ₹5.47 Cr |
| Total Income | ₹406.12 Cr | ₹504.26 Cr |
| Profit/Loss Before Tax | -₹43.52 Cr | -₹50.09 Cr |
| PAT | -₹29.21 Cr | -₹34.96 Cr |
| Total Assets | ₹724.76 Cr | ₹858.36 Cr |
| Total Equity | ₹235.73 Cr | ₹200.38 Cr |
| Borrowings | ₹434.42 Cr | ₹573.81 Cr |
FY2026 revenue increased strongly, but the company remained loss-making at the consolidated level. Finance costs also increased substantially, while consolidated borrowings rose from about ₹434 Cr to ₹574 Cr.
Important Point
The company’s FY2026 consolidated loss was approximately ₹35 Cr, compared with a loss of approximately ₹29 Cr in FY2025. Therefore, the revenue recovery has not yet translated into consolidated profitability.
5. Segment Performance
FY2026 revenue was primarily driven by the textile business, while the surgical division remained profitable at the segment level.
| Segment | FY2026 External Revenue | Segment Result |
|---|---|---|
| Textiles | ₹443.94 Cr | -₹26.60 Cr |
| Surgical | ₹54.86 Cr | ₹15.56 Cr |
| Windmill | — | ₹6.26 Cr |
The surgical business remains a comparatively stable and profitable component of the company, while textiles account for the majority of revenue but have historically faced margin pressure.
CRISIL also reported that consolidated revenue increased approximately 26% to ₹500 Cr in FY2026, with home textiles contributing about ₹181 Cr, fabrics ₹124 Cr, surgical products ₹55 Cr and spinning approximately ₹140 Cr.
6. FY2027 Outlook
There are some signs of operational recovery.
According to CRISIL, Ramaraju entered FY2027 with approximately ₹140 Cr of consolidated revenue in Q1 FY2027, supported by execution of the remaining portion of a large U.S. home-textile order.
CRISIL also reported that the company had already received approximately US$3.5 million of orders to be executed by Q3 FY2027, with potential new/replacement U.S. orders of around US$20 million expected to support FY2027 revenue.
The company’s operating margin improved to approximately 5–6% in Q1 FY2027, according to CRISIL, primarily because of better capacity utilisation and U.S.-based orders.
7. Surgical Business – Key Strength
The surgical division is strategically important because it provides a more specialised healthcare-related business alongside the cyclical textile operations.
Its Surgicom brand has been developed over decades and covers absorbent cotton, gauze, bandages and wound-care products. The company has also reported compliance with medical-device quality standards for its surgical division.
This creates exposure to the healthcare consumables market while the larger textile business provides scale.
8. Ramco Group Connection
Ramaraju Surgical is part of the wider Ramco Group ecosystem.
Its annual report shows investments/relationships with several group-associated companies, including Rajapalayam Mills, Ramco Industries and The Ramco Cements.
The company also holds investments in Ramco-group companies. CRISIL estimated the value of its Ramco-group shareholdings at approximately ₹285 Cr as of June 2026, of which around ₹140 Cr was unencumbered.
These investments are potentially important because the company has indicated that monetisation of investments can be used to support debt reduction.
9. Debt & Credit Profile
This is currently one of the most important areas to monitor.
CRISIL reaffirmed the company’s bank-facility ratings in August 2026 at:
Long Term: CRISIL BBB / Negative
Short Term: CRISIL A3+
The total rated bank facilities were increased to approximately ₹620.43 Cr.
CRISIL highlighted:
- High debt
- Elevated interest costs
- Negative cash-accrual-to-debt metrics
- Large working-capital requirements
- High utilisation of bank limits
- Exposure to cotton and yarn-price volatility
- Dependence on refinancing and/or monetisation of investments
As of March 2026, consolidated borrowings in the annual report were approximately ₹573.81 Cr.
10. Working Capital Risk
Textiles are working-capital intensive, particularly when large export orders are executed.
The company’s consolidated trade receivables increased from approximately ₹86 Cr in FY2025 to ₹184 Cr in FY2026, while inventories increased from ₹132 Cr to ₹157 Cr.
This explains part of the increase in working-capital borrowing.
For investors, the important metric to monitor is therefore not only revenue growth but also:
Revenue growth → EBITDA → operating cash flow → receivables → debt reduction
11. Shareholding
As of 30 June 2026:
| Category | Holding |
|---|---|
| Promoter & Promoter Group | 54.69% |
| Public | 45.31% |
| Total Shares | 58,15,127 |
The largest individual promoter holding was that of R. Nalina Ramalakshmi at 47.27%, followed by N.R.K. Ramkumar Raja and related promoter holdings.
12. Current Share Price & Valuation
A major point of clarification:
Ramaraju Surgical is not an NSE/BSE-listed stock. Its shares are listed on MSEI, where trading liquidity is extremely limited. MSEI currently identifies the company under the symbol RAMARAJU.
An indicative unlisted-share price reported by Moneycontrol was around ₹237.17 per share, with:
- Indicative market value: ~₹138 Cr
- Book value: ~₹342.46/share
- P/B: ~0.69x
- P/S: ~0.27x
- P/E: Not meaningful because of losses
These are indicative partner-derived rates rather than an actively traded NSE/BSE market price.
Based on the reported price, the company is trading at a substantial discount to its consolidated book value, but the discount needs to be considered alongside the company’s losses, leverage and very limited liquidity.
13. Rights Issue History
In 2024, the company raised approximately ₹37.07 Cr through a rights issue of 18,17,227 equity shares at ₹204 per share.
The rights issue was oversubscribed by approximately 136%, and the shares received listing and trading approval from MSEI in April 2024.
This ₹204 price is a historical capital-raising reference and should not be treated as the current fair value of the company.
14. Key Growth Drivers
1. U.S. Home-Textile Orders
Large U.S. customer orders have been an important driver of recent revenue growth.
2. Capacity Utilisation
Improvement in utilisation of spinning, weaving and home-textile capacity could improve operating leverage.
3. Surgical Healthcare Business
Surgicom provides exposure to relatively specialised medical consumables with an established product portfolio.
4. Ramco Group Ecosystem
The company’s relationship with the wider Ramco Group provides access to an established industrial ecosystem and investment portfolio.
5. Investment Monetisation
Sale of selected investments could potentially be used to reduce debt. The board had approved a proposal in February 2026 to sell investments in associate companies for up to ₹100 Cr.
15. Key Risks
High Debt
Debt of approximately ₹574 Cr against a business that is still reporting consolidated losses remains a major risk.
Textile Cyclicality
Cotton and yarn prices can significantly impact margins. CRISIL notes that cotton constitutes around 95% of raw-material cost.
Working Capital
Receivables increased significantly in FY2026, creating additional funding requirements.
Limited Trading Liquidity
Although technically MSEI-listed, the stock is not traded like a normal NSE/BSE security. Exit liquidity can therefore be limited.
Consolidated Losses
Revenue has recovered, but the company continues to report losses after finance costs.
Execution Risk
The investment case depends significantly on successful execution of textile/home-textile orders and improvement in capacity utilisation.
16. Overall Company Snapshot
| Parameter | Status |
|---|---|
| Established | 1939 |
| Ramco Group | Yes |
| Surgical Products | Strong established business |
| Textile Business | Large revenue contributor |
| FY26 Revenue | ₹498.80 Cr |
| FY26 Consolidated PAT | -₹34.96 Cr |
| FY26 Borrowings | ~₹573.81 Cr |
| Promoter Holding | 54.69% |
| MSEI Listed | Yes |
| NSE/BSE Listed | No |
| Indicative Share Price | ~₹237 |
| Indicative Market Value | ~₹138 Cr |
| P/B | ~0.69x |
| DRHP / IPO | No current IPO process identified |
| Main Opportunity | Textile recovery + U.S. orders + surgical business |
| Main Risk | High leverage + losses + working capital |
UnlistedCart Takeaway
Ramaraju Surgical Cotton Mills is a 1939-established Ramco Group company with a differentiated combination of medical consumables and textile manufacturing.
The interesting part of the story is the combination of an established Surgicom surgical-products franchise, a large textile manufacturing base and potential recovery in home-textile exports.
However, the financial picture requires close monitoring. FY2026 revenue increased substantially, but consolidated losses widened to around ₹35 Cr and borrowings rose to roughly ₹574 Cr. The next phase of the story therefore depends heavily on better capacity utilisation, execution of U.S. orders, margin improvement and debt reduction.
One important clarification for investors: Ramaraju Surgical is technically listed on MSEI, not NSE/BSE. It is therefore commonly offered in the “unlisted shares” market because there is no regular NSE/BSE trading liquidity, but it should not technically be described as an entirely unlisted company.
Disclaimer: Unlisted/MSEI-thinly traded share prices are indicative and may differ significantly between buyers and sellers. Limited liquidity can make entry and exit difficult. Valuation should be assessed alongside debt, profitability, cash flows, promoter holding, business performance and the investor’s own risk profile.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
