
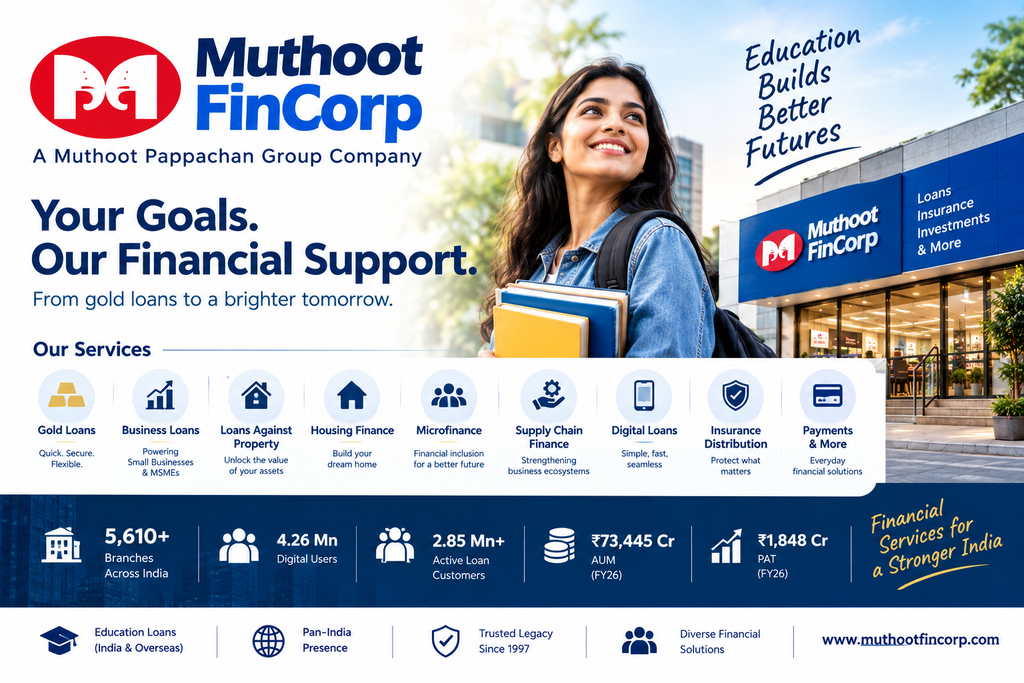
Company Overview
Muthoot FinCorp Limited (MFL) is a diversified Indian Non-Banking Financial Company (NBFC) and the flagship financial-services company of the Muthoot Pappachan Group (MPG).
The company was incorporated in 1997 and has built its core business around gold loans, while progressively expanding into other retail and MSME financial-services segments.
Its businesses include:
- Gold loans
- Business loans
- Loans against property
- Housing finance
- Microfinance
- Supply-chain finance
- Digital loans
- Personal finance
- Insurance distribution
- Payments
- Savings and other financial services
Muthoot FinCorp operates through a combination of a large physical branch network and its digital platform Muthoot FinCorp ONE, following a “phygital” model. As of 31 March 2026, the company had 5,610 branches, 4.26 million digital users and AUM of approximately ₹73,445 crore.
Official Website:
Muthoot FinCorp
Important Clarification: Muthoot FinCorp vs Muthoot Finance
Investors should not confuse Muthoot FinCorp Limited with Muthoot Finance Limited.
They are different companies belonging to different branches of the Muthoot family.
| Particular | Muthoot FinCorp | Muthoot Finance |
|---|---|---|
| Group | Muthoot Pappachan Group | Muthoot M. George Group |
| Status | Unlisted | Listed |
| Core Business | Gold loans + diversified lending | Primarily gold loans |
| Stock Exchange | Not listed currently | NSE & BSE |
| Headquarters | Thiruvananthapuram | Kochi |
The company discussed in this report is Muthoot FinCorp Limited, the Muthoot Pappachan Group company. CDSL’s current records also show Muthoot FinCorp as not listed.
Business Model
Muthoot FinCorp’s core model is lending to individuals and small businesses against gold jewellery.
The company provides liquidity against pledged gold while earning interest income from the loan portfolio.
Gold loans remain the company’s primary business and the key driver of its customer acquisition, branch network and overall profitability.
The company has subsequently diversified into other secured and unsecured lending products.
Major Business Segments
1. Gold Loans
The flagship business.
Customers pledge gold jewellery as collateral and receive financing against it.
Gold loans provide:
- Quick access to credit
- Secured lending
- Shorter processing times
- Physical collateral
- Strong branch-level customer relationships
As of March 2026, the company had 3,781 gold-loan branches, which management describes as the core engine of customer acquisition, servicing and collateral handling.
2. Business & MSME Finance
The company provides financing to:
- Small businesses
- Traders
- Self-employed individuals
- MSMEs
- Entrepreneurs
3. Loans Against Property
Financing against residential and commercial property.
4. Housing Finance
Housing-related lending through the group’s housing-finance business.
5. Microfinance
The group has a microfinance business serving customers who may have limited access to traditional banking credit.
6. Digital Lending
Muthoot FinCorp ONE enables customers to digitally access loan products and related financial services.
Distribution Network
Muthoot FinCorp has built a large pan-India physical distribution network.
FY2026 Scale
- 5,610 total branches
- 3,781 gold-loan branches
- 47,323 employees
- 4.26 million digital users
- 8.22 million+ unique customers served during the last three financial years
- 2.85 million+ active unique customers with loan accounts as of March 2026
The company acquired approximately 1.73 million new customers with loan accounts during FY2026.
The combination of physical branches and digital channels is an important part of the company’s distribution strategy.
Muthoot FinCorp ONE
Muthoot FinCorp ONE is the company’s digital platform.
It is designed to provide customers with a digital journey covering various lending products and selected financial services.
The platform supports:
- Digital customer onboarding
- Loan applications
- Digital KYC
- Loan servicing
- Payments
- Account management
- Digital lending journeys
The company had approximately 4.26 million users on the platform as of March 2026.
FY2026 Financial Performance
Muthoot FinCorp delivered a significant improvement in profitability during FY2026.
| Particulars | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Revenue from Operations | ₹6,543 Cr | ₹8,498 Cr | ₹11,204 Cr |
| PAT | ₹1,048 Cr | ₹608 Cr | ₹1,848 Cr |
| Net Worth | ₹5,811 Cr | ₹6,363 Cr | ₹8,218 Cr |
| Total Assets | ₹38,704 Cr | ₹45,456 Cr | ₹67,669 Cr |
| AUM* | — | — | ₹73,445 Cr |
*Reported AUM includes the broader managed portfolio and should not be directly equated with balance-sheet assets.
FY2026 revenue from operations grew approximately 31.8%, while PAT increased more than threefold from FY2025.
Profitability
FY2026 PAT was approximately ₹1,847.62 crore, compared with ₹607.99 crore in FY2025.
This represents PAT growth of approximately 204% YoY.
The improvement was supported by:
- Strong gold-loan growth
- Higher interest income
- Better operating leverage
- Improved profitability of the lending portfolio
- Expansion of the overall AUM
Gold Loan Growth
Gold loans remain the most important part of the Muthoot FinCorp story.
According to the CRISIL analysis cited in the company’s IPO documents, Muthoot FinCorp’s gold-loan AUM grew at approximately 59.04% CAGR between March 2024 and March 2026.
This was described as the fastest gold-loan AUM growth among the peer group covered in the analysis.
The structural drivers include:
- Rising household demand for secured credit
- Formalisation of gold lending
- Faster digital processing
- Large physical branch network
- Strong brand recognition
- Ability to serve customers underserved by traditional banks
AUM
As of 31 March 2026, Muthoot FinCorp reported AUM of approximately:
₹73,444.72 Crore
This represents a substantial increase in the company’s lending scale.
CRISIL separately reported managed assets of approximately ₹64,058 crore on a standalone basis under its rating methodology, which includes specific adjustments and differs from the company’s reported AUM definition.
Therefore, investors should always compare AUM figures using the same reporting definition.
Q1 FY2027 Performance
The company maintained strong momentum during the first quarter of FY2027.
For the quarter ended 30 June 2026:
| Particular | Q1 FY2027 |
|---|---|
| Total Income | ₹3,158.83 Cr |
| PAT | ₹705.48 Cr |
| Net Worth | ₹7,908.46 Cr |
| Capital Adequacy Ratio | 18.06% |
| Gross Stage 3 | 0.77% |
| Net Stage 3 | 0.40% |
PAT increased almost three times YoY, from ₹179.3 crore in Q1 FY2026 to ₹705.48 crore in Q1 FY2027.
Total income approximately doubled YoY.
Asset Quality
Asset quality is one of the most important factors to monitor in any gold-loan NBFC.
CRISIL reported:
| Metric | FY2024 | FY2025 | FY2026 | Q1 FY2027 |
|---|---|---|---|---|
| Gross NPA | 1.6% | 2.0% | 1.0% | 0.8% |
| Managed Assets | ₹27,746 Cr | ₹40,343 Cr | ₹64,058 Cr | ₹60,011 Cr |
The reported Gross NPA ratio improved significantly during FY2026 and stood at approximately 0.8% in Q1 FY2027 under CRISIL’s methodology.
The company therefore needs to maintain disciplined underwriting and collateral management as the loan book expands.
Capital Adequacy
Muthoot FinCorp reported a capital adequacy ratio of 18.06% as of June 2026.
The proposed IPO is directly linked to the company’s capital requirements.
The company proposes to use the IPO proceeds primarily to strengthen its Tier-I capital base, which can support:
- Future lending
- AUM expansion
- Digital platform expansion
- Diversification into additional financial products
- Regulatory capital requirements
Funding & Debt Market Access
Muthoot FinCorp has demonstrated access to the debt capital markets.
During FY2026 and Q1 FY2027, the company raised capital through:
- Non-convertible debentures
- Private placements
- Other debt instruments
During Q1 FY2027 alone, it raised approximately:
- ₹446.24 Cr through a public NCD issue
- ₹100 Cr through private placement
- ₹500 Cr through another private placement
The company’s ability to access multiple funding channels is important for an NBFC because funding costs directly affect lending margins.
Credit Ratings
Muthoot FinCorp benefits from established credit ratings across its debt instruments.
CRISIL’s July 2026 rating rationale highlighted:
- Strong market position in gold loans
- Significant scale
- Improving profitability
- Strong capitalisation
- Diversified funding access
The company’s credit profile is an important part of its ability to scale the lending franchise.
Industry Opportunity
India’s organised gold-loan market has been expanding as households increasingly use gold jewellery as collateral for formal credit.
The DRHP, citing CRISIL’s industry assessment, expects India’s organised gold-loan market to continue expanding through FY2029.
Key structural drivers include:
Financial Inclusion
Gold loans provide access to formal credit for customers who may not have conventional income documentation or strong credit histories.
Gold Ownership
India has a very large household gold stock, providing a significant collateral base.
Faster Credit
Gold loans can generally be processed faster than many traditional secured loans.
Formalisation
The migration from informal lenders towards organised NBFCs and banks can expand the addressable market.
Competitive Advantages
1. Large Branch Network
5,610 branches provide substantial customer reach.
2. Strong Gold-Loan Franchise
The gold-loan business remains the company’s primary growth engine.
3. Brand Recognition
The Muthoot Pappachan Group has a long operating history, with roots going back to 1887.
4. Phygital Model
Combining branches with digital distribution allows the company to serve customers through both physical and digital channels.
5. Diversification
Beyond gold loans, the company has developed businesses in:
- MSME finance
- Housing
- Microfinance
- LAP
- Supply-chain finance
- Digital lending
This can potentially reduce dependence on a single product over the long term.
Major Growth Drivers
Gold Loan AUM Expansion
The company’s gold-loan portfolio has grown rapidly, providing the primary growth engine.
Branch Expansion
Additional branches can increase geographic penetration and customer acquisition.
Digital Adoption
Muthoot FinCorp ONE can reduce friction in customer onboarding and servicing.
Cross-Selling
The existing customer base can potentially be used to cross-sell:
- Insurance
- Savings
- Other loans
- Payments
- Financial services
MSME Lending
The company’s expansion into business and MSME finance provides another avenue for AUM growth.
Key Risks
1. Gold Price Risk
Gold is the primary collateral for the company’s flagship lending business.
A sharp decline in gold prices can affect collateral coverage and recovery values.
2. Credit Risk
Although gold loans are secured, borrowers can still default.
Asset quality needs continuous monitoring, particularly as the company expands beyond traditional gold loans.
3. Regulatory Risk
NBFCs are subject to RBI regulations relating to:
- Capital adequacy
- Gold-loan practices
- Customer protection
- Lending norms
- Provisioning
- Liquidity
- Governance
Regulatory changes can affect profitability and operating practices.
4. Funding Cost
NBFC profitability is sensitive to borrowing costs.
An increase in interest rates or funding spreads can put pressure on margins.
5. Concentration in Gold Loans
Gold remains the core business.
Therefore, changes in:
- Gold prices
- Customer behaviour
- Competition
- RBI regulations
- Gold-loan pricing
can affect the company materially.
6. Competition
Muthoot FinCorp competes with:
- Banks
- Gold-loan NBFCs
- Other NBFCs
- Digital lenders
- Informal lenders
The gold-loan market is highly competitive.
7. Diversification Risk
While diversification creates new growth opportunities, newer businesses such as microfinance and unsecured/digital lending can carry different credit-risk characteristics from the traditional secured gold-loan business.
IPO Status
One of the biggest developments for Muthoot FinCorp is its proposed IPO.
The company filed its Draft Red Herring Prospectus (DRHP) with SEBI on 12 August 2026.
Proposed IPO
Issue Size: Up to ₹3,000 Cr
Issue Type: Fresh Issue
Offer for Sale: None
Proposed Listing: NSE and BSE
The company may also consider a pre-IPO placement of up to ₹600 crore, which, if completed, would reduce the size of the fresh issue accordingly.
Use of IPO Proceeds
The net proceeds are proposed to be used primarily to:
- Strengthen Tier-I capital
- Meet future capital requirements
- Support onward lending
- Fund business expansion
- Expand the digital platform
- Support the diversified lending portfolio
IPO Status as of 23 September 2026
The company has filed its DRHP, but the final:
- IPO price band
- Issue dates
- Lot size
- Listing date
have not yet been announced.
Therefore, Muthoot FinCorp continues to be an unlisted company at present.
Unlisted Share Price & Valuation
Unlisted-market prices can change frequently and are not equivalent to a final IPO valuation.
A current Moneycontrol unlisted-share page shows an indicative price of approximately ₹230 per share, with a reported market capitalisation of approximately ₹4,455 Cr based on its displayed share count. These figures should be independently verified before quoting or transacting because unlisted-market prices are indicative and can change without the transparency of an exchange-traded market.
Importantly, the company has also undertaken a 1:5 stock split, reducing the face value from ₹10 to ₹2; investors should therefore confirm the applicable post-split share count and price before comparing historical quotations.
Investment Perspective
Muthoot FinCorp represents exposure to India’s gold-loan and diversified retail-credit ecosystem.
The major investment themes are:
Gold loan growth + financial inclusion + large branch network + digital lending + MSME credit + strong AUM growth + proposed IPO.
The company has demonstrated substantial operating growth:
- ₹73,445 Cr AUM
- ₹11,204 Cr FY2026 operating revenue
- ₹1,848 Cr FY2026 PAT
- 5,610 branches
- 4.26 million digital users
- ₹705 Cr Q1 FY2027 PAT
- 18.06% capital adequacy
The IPO is particularly important because the proposed ₹3,000 crore fresh capital raise is intended to strengthen Tier-I capital and support future lending growth.
For an unlisted investor, however, the key variables remain:
entry valuation + IPO pricing + asset quality + funding cost + gold prices + regulatory environment + future AUM growth.
An unlisted-market purchase should not be evaluated solely on the expectation of an IPO; the underlying financial performance and the price paid for the shares remain important.
Company Snapshot
| Particular | Details |
|---|---|
| Company | Muthoot FinCorp Limited |
| Group | Muthoot Pappachan Group |
| Incorporated | 1997 |
| Industry | NBFC / Financial Services |
| Core Business | Gold Loans |
| Status | Unlisted Public Company |
| FY2026 Revenue from Operations | ₹11,203.81 Cr |
| FY2026 PAT | ₹1,847.62 Cr |
| FY2026 Net Worth | ₹8,218 Cr |
| FY2026 AUM | ₹73,444.72 Cr |
| Q1 FY2027 PAT | ₹705.48 Cr |
| Q1 FY2027 CAR | 18.06% |
| Branches | 5,610 |
| Gold-Loan Branches | 3,781 |
| Digital Users | 4.26 Mn |
| FY2026 Gold Loan AUM CAGR | 59.04% |
| IPO Size | Up to ₹3,000 Cr |
| OFS | Nil |
| Proposed Exchanges | NSE & BSE |
| IPO Status | DRHP filed |
| IPO Price Band | Not announced |
| IPO Date | Not announced |
Important Links
Muthoot FinCorp Official Website
Muthoot FinCorp
Muthoot FinCorp ONE
Muthoot FinCorp ONE
Muthoot FinCorp Investor / Corporate Information
Muthoot FinCorp Corporate Information
SEBI – Muthoot FinCorp Filings
SEBI Filings
CRISIL – Muthoot FinCorp Rating Rationale
CRISIL Rating Rationale
CDSL – Muthoot FinCorp Corporate Details
CDSL – Muthoot FinCorp
Muthoot FinCorp IPO – DRHP Information
Muthoot FinCorp IPO / DRHP Overview
Disclaimer
This report is for informational and educational purposes only and should not be considered investment advice, an offer to buy or sell securities, or a guarantee of returns.
Unlisted securities involve higher risks including limited liquidity, limited price discovery, valuation uncertainty, transfer restrictions, lack of an established public market and uncertainty regarding IPO/listing timelines.
Financial figures and company information have been compiled from company disclosures, SEBI filings, CRISIL ratings and other publicly available sources. IPO size, price band, valuation, timing and listing plans may change. Unlisted share prices are indicative and may differ materially from any eventual IPO price.
Investors should independently verify the latest company and regulatory disclosures before making any investment decision.
For more such unlisted stocks visit
