
Unlisted Equity Research Report | Updated September 2026
Category: EdTech / Digital Education / e-Governance / IT Services
Status: Active & Unlisted Public Company
CIN: U80302PN2001PLC135348
ISIN: INE03KR01016
Incorporated: 20 August 2001
Registered Office: Pune, Maharashtra
Face Value: ₹10 per share
Promoter: Government of Maharashtra
Government Holding: 37.13%
Shares Outstanding: 80,80,195
IPO Status: No IPO currently planned
About the Company
Maharashtra Knowledge Corporation Limited (MKCL) is a technology and knowledge company promoted by the Government of Maharashtra and incorporated in 2001.
The company was created to use technology to bridge the digital, knowledge and development opportunity divide, with its core activities spanning:
- Digital education
- IT literacy
- Skill development
- Higher-education technology
- e-Governance
- Digital examination systems
- Recruitment platforms
- Citizen services
- SaaS platforms
MKCL is an unlisted public company. Importantly, the company itself states that it currently has no plans to undertake an IPO.
Key Highlights
| Particular | Details |
|---|---|
| Founded | 2001 |
| Headquarters | Pune |
| Status | Unlisted Public Company |
| FY26 Revenue from Operations | ₹201.47 Cr |
| FY26 Total Income | ₹242.65 Cr |
| FY26 EBITDA | ~₹80.45 Cr |
| FY26 PBT | ~₹73.17 Cr |
| FY26 Consolidated PAT | ~₹60.73 Cr |
| FY26 EPS | ~₹75.15 |
| FY26 Cash Equivalents | ~₹168.3 Cr |
| Debt / Equity | 0x |
| Net Worth | ~₹674.6 Cr |
| Current OTC Reference | ~₹435–₹444/share |
| Indicative Market Cap | ~₹351–359 Cr |
| Indicative FY26 P/E | ~5.8–5.9x |
| Indicative P/B | ~0.5–0.6x |
| IPO | No current plan |
FY26 financial figures are based on current financial databases reflecting the company’s latest FY26 filings; MKCL’s official website confirms that its 25th Annual Report for FY2025-26 has been released.
What Makes MKCL Different?
MKCL is not a conventional EdTech company.
It sits at the intersection of:
Government + Education + Technology + Skill Development + Digital Governance
The Government of Maharashtra owns 37.13%, while ten state universities collectively hold 33.91%. This gives MKCL a highly unusual shareholder structure for an unlisted technology company.
The model combines government credibility and institutional relationships with commercial operations and technology development.
Core Business Model
MKCL’s operations can broadly be divided into four areas.
1. Digital Literacy & Education
The company’s flagship product is:
MS-CIT — Maharashtra State Certificate in Information Technology
Launched in 2001, MS-CIT has become one of India’s largest mass IT-literacy programs.
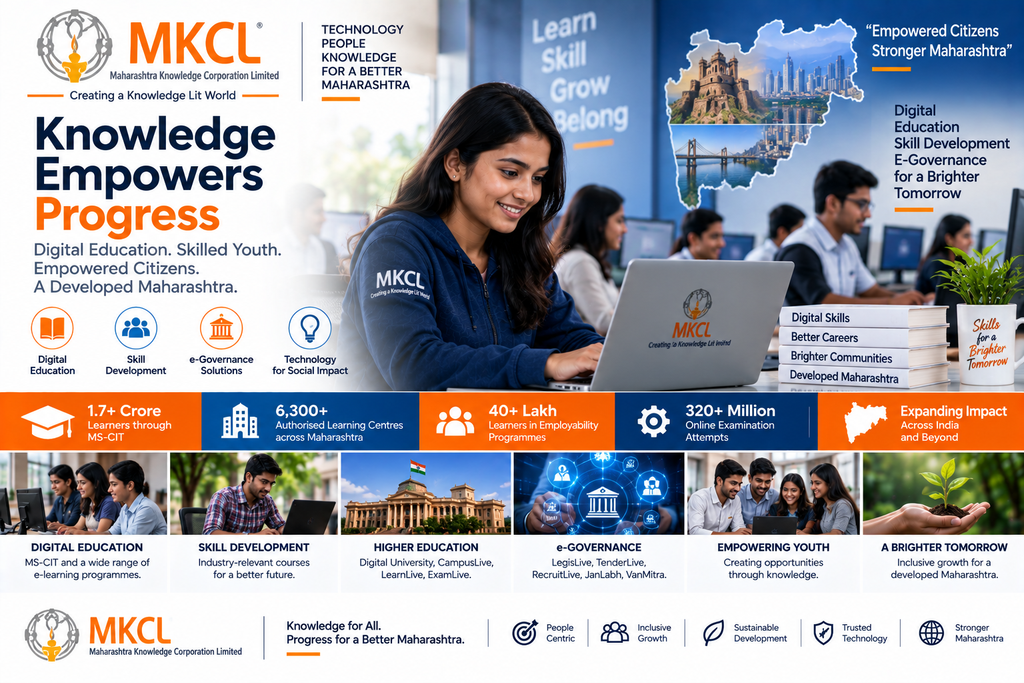
MKCL reported more than 1.7 crore learners completing MS-CIT over the previous 24 years, while FY25 alone recorded approximately 7.99 lakh MS-CIT learners.
The programme operates through MKCL’s extensive authorised learning-centre network.
2. Employability & Skill Development
MKCL operates multiple skill-development brands including:
- KLiC
- DEEP
- iLike
- Mastering
- CCTP
- MS-ACIT
- Other AI-powered courses
The company says more than 40 lakh learners have completed its digital employability courses over the last 15 years.
The courses cover areas such as:
- Data Science
- Digital Design
- Accounting
- Cybersecurity
- Software Development
- Digital Freelancing
- Management
- New Collar Jobs
- Career Readiness
The current product portfolio includes 265 AI-powered eLearning courses for digital skills and employability.
3. Higher Education Technology
MKCL’s Digital University platform provides technology for the university lifecycle.
The platform covers:
Admission → Student Management → Academics → Examination → Credits → Analytics → Certification → Graduation
MKCL describes Digital University as an integrated, NEP-2020-compliant student-facilitation framework.
Other platforms include:
CampusLive
SaaS platform for administrative and academic services for higher-education institutions.
LearnLive
Academic lifecycle management for colleges, programmes, students and teachers.
ExamLive
Secure examination and certification framework covering:
- AI-enabled question-bank creation
- Online examinations
- AI-based proctoring
- Automated evaluation
- Results
- Analytics
- Certification
MKCL reports more than 320 million online examination attempts through ExamLive.
4. e-Governance
MKCL also builds technology platforms for government departments and public institutions.
Key products include:
LegisLive
Digital platform for legislative-secretariat operations.
TenderLive
Electronic tendering and procurement platform.
RecruitLive
Online recruitment and selection platform.
VanMitra
Digital platform for processing forest-rights claims.
JanLabh
Citizen-facing platform for discovering government welfare schemes.
These products provide MKCL with an additional revenue stream beyond education.
Distribution Network
One of MKCL’s strongest competitive advantages is its physical-digital distribution network.
The company reports:
6,300+ Authorised Learning Centres
spread across all blocks of Maharashtra.
These centres collectively have more than:
75,000 internet-ready computers
This network provides MKCL with a significant last-mile advantage for delivering digital education and skill programmes in urban as well as semi-urban/rural markets.
This is difficult for a purely online EdTech company to replicate.
Geographic Expansion
Although its strongest presence is in Maharashtra, MKCL is not restricted to one state.
The company has joint ventures/projects in:
- Odisha
- Haryana
- Bihar
- Kerala
- Tripura
- Other states
It also has international activity through MKCL Arabia Ltd. in Saudi Arabia.
This creates an opportunity to replicate the Maharashtra model in other markets.
Financial Performance
Revenue Trend
| ₹ Crore | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Revenue from Operations | 120.17 | 177.51 | 234.52 | 276.05 | 201.47 |
| EBITDA | 43.94 | 67.25 | 82.55 | 89.95 | 80.45 |
| PBT before Exceptional | 41.09 | 61.15 | 75.56 | 83.72 | 73.17 |
| Consolidated PAT | 37.79 | 47.68 | 62.59 | 32.04 | 60.73 |
| EPS | 46.77 | 63.35 | 77.48 | 39.65 | 75.16 |
FY22–FY26 figures show that MKCL’s operating scale expanded substantially over the period, although FY26 revenue declined from the unusually strong FY25 base.
FY26 Revenue Decline — Important Point
FY26 revenue from operations declined approximately:
₹276.05 Cr → ₹201.47 Cr
or around 27% YoY.
At first glance, this looks concerning.
However, the earnings picture is much stronger.
FY26 consolidated PAT increased from approximately:
₹32.04 Cr → ₹60.73 Cr
or approximately 90%.
Why?
Because FY25 contained a major one-time expense.
FY25 GST Exceptional Item
During FY25, MKCL paid approximately:
₹46.15 Cr
under the GST Amnesty Scheme.
The charge related to GST matters covering earlier financial years and materially reduced FY25 reported profitability.
The company stated that it chose the amnesty route after prolonged litigation and uncertainty around the GST issue.
Therefore, FY25 PAT of ₹32.05 Cr does not represent the underlying earning power of the business.
Before the exceptional charge, FY25 PBT was approximately ₹83.73 Cr.
This is why FY26’s ₹60.73 Cr consolidated PAT should be interpreted differently from a simple “90% profit growth” headline.
Better Interpretation
FY25 reported PAT: depressed by ₹46.15 Cr exceptional GST payment
FY26 PAT: largely normalised after the one-time charge
This makes FY26 a better reference point for evaluating the company’s current earnings capacity.
Profitability
FY26:
EBITDA: ~₹80.45 Cr
EBITDA Margin: ~40% on revenue from operations
PBT: ~₹73.17 Cr
Consolidated PAT: ~₹60.73 Cr
The combination of high margins and an asset-light technology/education model is one of MKCL’s most attractive features.
Balance Sheet
MKCL has an unusually strong balance sheet for an unlisted technology company.
FY26
Net Worth: ~₹674.6 Cr
Debt: ₹0
Debt/Equity: 0x
Cash Equivalents: ~₹168.3 Cr
Current financial databases show no borrowings and a large accumulated reserve base.
This significantly reduces financial risk.
Cash & Investment Position
The company has accumulated substantial financial resources over its operating history.
FY25 alone showed significant bank deposits and financial investments. At March 2025, the company reported approximately:
- ₹23.57 Cr cash and cash equivalents
- ₹66.50 Cr bank deposits with maturity up to 12 months
- ₹19.99 Cr other current financial assets
The broader investment/treasury portfolio is substantially larger.
By FY26, current financial databases report approximately ₹168.3 Cr in cash equivalents.
This treasury position is an important part of the valuation.
Operating Cash Flow
FY25 was a weak year for operating cash flow because working capital increased sharply.
Operating cash flow fell to approximately:
-₹36.34 Cr
from:
₹83.25 Cr in FY24
The major issue was a substantial increase in trade receivables.
However, FY26 operating cash flow recovered to approximately:
₹42.24 Cr
according to current FY26 financial data.
Equity Research Interpretation
The FY26 recovery is encouraging, but operating cash conversion should continue to be monitored.
A business with high accounting profitability should ideally convert a substantial portion of that profit into cash over time.
Revenue Mix
FY25 revenue from operations was approximately ₹276.06 Cr.
The largest contributor was:
ALC Network Business Development Program
Revenue:
₹218.89 Cr
This includes:
- MS-CIT
- SARTHI-CSMS-DEEP
- KLiC
- Work-based degree programmes
- Registration/LMS fees
Other segments included:
Nationwide Business Development Program
₹44.06 Cr
Higher Education Transformation Program
₹10.38 Cr
e-Governance
Approximately ₹2.15 Cr
This demonstrates that the ALC/learning-centre network remains the economic engine of MKCL.
MS-CIT
MS-CIT remains the company’s most important franchise.
FY25:
7,98,647 learners
compared with:
7,36,493 learners in FY24
An increase of approximately 62,154 learners / 8.4%.
MS-CIT generated approximately:
₹119.83 Cr
of FY25 revenue.
The programme therefore represented roughly 43% of FY25 revenue from operations.
This demonstrates both the strength and the concentration of the MKCL business model.
SARTHI / CSMS-DEEP
Another major growth contributor has been the CSMS-DEEP programme.
FY25 completed modules increased to:
1,27,419
from:
84,326
in FY24.
This generated approximately:
₹85.53 Cr
of FY25 revenue.
Therefore, a significant portion of FY25’s revenue growth came from government-linked skill-development programmes.
This creates strong growth opportunities but also introduces programme-duration and government-project concentration risk.
Shareholding Pattern
MKCL has an unusual and strategically important ownership structure.
| Shareholder Group | Holding |
|---|---|
| Government of Maharashtra | 37.13% |
| 10 State Universities | 33.91% |
| Others / Individuals / Institutions | ~28.96% |
| Total | 100% |
The Government of Maharashtra owns exactly 30 lakh shares.
The ten universities collectively hold approximately 27.40 lakh shares.
Why This Matters
Government + universities together represent approximately:
71% of the equity
This gives MKCL a very distinctive institutional shareholder base.
It can provide credibility and access to large educational/government projects, but it also means the company is not structured like a conventional promoter-led technology company.
Valuation
Current unlisted-market references are approximately:
₹435–₹444/share
Recent sources include:
- ~₹435 — BuyUnlistedShares
- ~₹435 — UnlistedZone
- ~₹443.67 — Moneycontrol
- ~₹470 — another current market database reference
These are OTC/private-market references, not exchange prices.
For valuation purposes, a reasonable working range is:
₹435–₹445/share
Indicative Market Capitalisation
At ₹435:
80,80,195 shares × ₹435
≈
₹351 Cr
At ₹444:
≈
₹359 Cr
This is a relatively small market capitalisation compared with the company’s accumulated net worth and cash/investment base.
P/E Valuation
Using FY26 EPS of approximately:
₹75.15
At ₹435:
P/E ≈ 5.8x
At ₹444:
P/E ≈ 5.9x
Current market databases similarly show P/E around 5.8–6.3x.
This is relatively inexpensive for a profitable, debt-free technology/education platform.
Price-to-Book
FY26 book value is approximately:
₹834–₹847/share
Against a market price around ₹435–₹444:
P/B ≈ 0.5–0.6x
That means the company is currently trading at a substantial discount to book value.
This is one of the strongest valuation arguments in the MKCL investment case.
But Why Does MKCL Trade Below Book Value?
The discount can potentially be explained by several factors:
- Unlisted liquidity
- No regular exchange price discovery
- No IPO plan
- Government/institution-heavy ownership
- Limited public float
- Revenue cyclicality from government programmes
- Significant treasury assets that do not necessarily generate high ROE
- Limited visibility on future capital allocation
Therefore, a low P/B ratio does not automatically mean the stock is undervalued.
Dividend
MKCL has historically paid dividends.
FY24 dividend:
₹2.50/share
FY25 final dividend:
₹1/share
The FY25 reduction was understandable given the exceptional GST payment and lower reported PAT.
Current FY26 market databases report approximately:
₹1.50/share
as the latest dividend reference.
At ₹435, a ₹1.50 dividend represents only approximately 0.35% yield.
Therefore, MKCL should not currently be positioned as a high-dividend stock.
The stronger investment argument is:
Cash-rich balance sheet + low valuation + recurring education franchise + government ecosystem
rather than dividend yield.
Investment Positives
1. Government of Maharashtra Backing
The Government owns 37.13%, providing significant institutional credibility.
2. Strong Institutional Ecosystem
Ten state universities hold another 33.91%.
This is a unique competitive advantage in education technology.
3. Strong Brand
MS-CIT has become synonymous with basic IT literacy in Maharashtra, according to the company’s own annual report.
4. Massive Distribution Network
6,300+ authorised learning centres and 75,000+ computers provide significant last-mile reach.
5. Proprietary Technology
MKCL owns/develops platforms including:
- ERA
- Digital University
- ExamLive
- LearnLive
- CampusLive
- TenderLive
- RecruitLive
- LegisLive
- VanMitra
This gives the company a technology/IP component beyond simple training services.
6. Zero Debt
The balance sheet has no conventional borrowings.
7. Strong Net Worth
FY26 shareholder funds are approximately ₹675 Cr, substantially above the current OTC market capitalisation.
8. Significant Cash / Investments
The company has accumulated a sizeable treasury over two decades.
9. FY26 Profit Normalisation
FY25 earnings were severely affected by the ₹46.15 Cr GST exceptional charge.
FY26 consolidated PAT recovered to approximately ₹60.73 Cr.
10. Expansion Beyond Maharashtra
MKCL has expanded through projects and joint ventures in multiple Indian states and Saudi Arabia.
Key Risks & Concerns
1. FY26 Revenue Decline
Revenue fell approximately 27% in FY26.
This is the biggest operating concern.
Investors should understand whether the decline represents:
- Completion of large programmes
- Normalisation after unusually high FY25 revenue
- Government-project timing
- Changes in learner volumes
- Changes in project mix
before extrapolating FY26 numbers.
2. Government Programme Dependence
A substantial portion of revenue comes from government-linked education and skill-development programmes.
Changes in:
- Government budgets
- Policy
- Programme approvals
- Contracts
- Payment cycles
can materially affect revenue.
3. MS-CIT Concentration
MS-CIT alone generated roughly ₹120 Cr in FY25.
This creates a meaningful concentration around one flagship programme.
4. Working-Capital Volatility
FY25 operating cash flow was negative because of a substantial increase in receivables.
5. Low ROE Relative to Book Value
The company has a very large accumulated net worth.
Consequently, even with good profits, ROE remains relatively modest.
FY26 ROE is reported around 9%.
6. Treasury Drag
A large cash/investment position is financially comforting, but if capital remains underutilised, it can suppress return on equity.
7. No IPO Catalyst
This is particularly important for UnlistedCart.
MKCL itself states:
“Presently, the Company does not have any plans of making Public Issue through IPO.”
Therefore, investors should not buy MKCL purely on an assumed IPO story.
8. Unlisted Liquidity
The shares are not exchange traded.
The investor may face difficulty finding a buyer at the desired price.
9. Valuation Can Remain Discounted
Even though MKCL trades below book value, the discount can persist because there is no immediate listing catalyst.
Investment Thesis
Bull Case
The bull case is based on MKCL becoming a broader digital public-infrastructure and education technology platform.
The company already has:
Government relationships + university relationships + learning-centre network + proprietary technology + large learner base
If MKCL successfully expands:
- Digital University
- AI-powered education
- Online examinations
- e-Governance
- Government skill programmes
- SaaS platforms
- Other-state operations
then the business could generate a higher proportion of recurring technology revenue.
At the current valuation, even moderate earnings growth could potentially create attractive long-term returns.
Bear Case
The bear case is that MKCL remains heavily dependent on:
MS-CIT + government skill programmes + Maharashtra
and that revenue remains volatile.
If revenue continues to decline, the large book value may not translate into high shareholder returns.
The low valuation could therefore represent a structural discount rather than an obvious mispricing.
What Makes the Current Valuation Interesting?
At roughly ₹435–₹445/share:
Market Cap
~₹351–359 Cr
FY26 Consolidated PAT
~₹60.7 Cr
FY26 EPS
~₹75
P/E
~5.8–5.9x
Book Value
~₹835–₹847/share
P/B
~0.5x
Debt
Zero
Net Worth
~₹675 Cr
This creates a rare situation:
Market Capitalisation < Net Worth
while the company is still profitable and generating cash.
That is the central valuation argument for MKCL.
Investment Scorecard
| Parameter | View |
|---|---|
| Business Quality | ⭐⭐⭐⭐☆ |
| Government / Institutional Support | ⭐⭐⭐⭐⭐ |
| Brand / Distribution | ⭐⭐⭐⭐⭐ |
| Technology/IP | ⭐⭐⭐⭐☆ |
| Revenue Growth | ⭐⭐⭐☆☆ |
| Profitability | ⭐⭐⭐⭐☆ |
| Balance Sheet | ⭐⭐⭐⭐⭐ |
| Cash Position | ⭐⭐⭐⭐⭐ |
| Valuation | ⭐⭐⭐⭐⭐ |
| IPO Visibility | ⭐☆☆☆☆ |
| Liquidity | ⭐⭐☆☆☆ |
| Overall Risk | Medium–High |
Investment Category
Cash-Rich EdTech & Digital-Governance Platform — Value-Oriented Unlisted Opportunity
Investment View
MKCL is one of the more unusual companies in India’s unlisted market.
It is neither a conventional EdTech start-up nor a traditional government company.
It is a government-promoted technology platform with commercial operations, a large education distribution network, proprietary technology and significant accumulated financial reserves.
The FY26 numbers are particularly interesting.
Revenue declined from ₹276 Cr to approximately ₹201 Cr, but consolidated PAT increased to approximately ₹60.7 Cr as the FY25 one-time GST burden disappeared.
This means investors should not interpret FY26 simply as “90% profit growth.”
The more useful conclusion is:
FY25 was artificially depressed by a large exceptional GST charge, while FY26 shows a return toward MKCL’s underlying profitability.
At roughly 5.8–6x FY26 earnings and only ~0.5x book value, the valuation is potentially attractive.
However, there is no confirmed IPO catalyst, and revenue has declined sharply in FY26.
Therefore, the investment case depends more on:
Earnings normalisation + balance-sheet value + future programme growth + capital allocation
than on an IPO exit.
What We Would Monitor
1. FY27 revenue growth
2. MS-CIT learner volumes
3. SARTHI/DEEP programme renewals
4. Government project pipeline
5. Operating cash flow
6. Receivables
7. Digital University / ExamLive monetisation
8. Growth outside Maharashtra
9. Use of cash and investments
10. Any change in IPO policy
Final Takeaway
Maharashtra Knowledge Corporation Limited is a rare combination of education, technology, government infrastructure and financial strength.
Its strongest competitive advantages are:
Government of Maharashtra backing + 10 university shareholders + 6,300+ learning centres + MS-CIT brand + proprietary technology + zero debt + large accumulated reserves.
The key concern is the 27% FY26 revenue decline and the company’s dependence on government-linked programmes.
At the same time, the valuation is difficult to ignore.
At around ₹435–₹445/share, MKCL is valued at approximately ₹350–360 Cr, against FY26 consolidated profit of approximately ₹60.7 Cr and net worth of approximately ₹675 Cr.
Overall View:
A potentially attractive value-oriented unlisted company, but not an IPO-driven opportunity.
The strongest case for MKCL is:
“High-quality institutional franchise + strong balance sheet + low valuation.”
The biggest question is:
“Can MKCL restart revenue growth after the FY26 decline and deploy its substantial balance-sheet resources efficiently?”
Investment View: Selective Accumulation / Long-Term Value Opportunity
How to Invest
MKCL shares are currently unlisted.
Current OTC references are approximately ₹435–₹445/share, depending on intermediary and transaction date. These are private-market indications, not exchange-traded prices.
The commonly reported minimum transaction lot is approximately 25–100 shares depending on intermediary, so investors should verify the actual seller’s lot and terms before placing an order.
Before investing, verify:
- ISIN: INE03KR01016
- Exact number of shares
- Seller ownership
- Latest shareholding
- Current negotiated price
- Demat transfer process
- Transfer restrictions
- Latest FY26 audited statements
- Applicable taxes
- Dividend record
- No-IPO status
Disclaimer
This report is prepared for informational and research purposes only and should not be considered investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Unlisted-share prices are indicative private-market references and may differ materially between buyers and sellers. Financial data from third-party platforms may also differ in presentation; investors should rely on the latest audited financial statements and official company filings for final investment decisions.
Unlisted securities involve higher liquidity and exit risk than listed securities. Investors should independently verify the latest financials, shareholding, ISIN, transferability, valuation, taxation and applicable regulatory requirements before investing.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
