
Unlisted Specialty Chemicals & Precipitated Silica Company
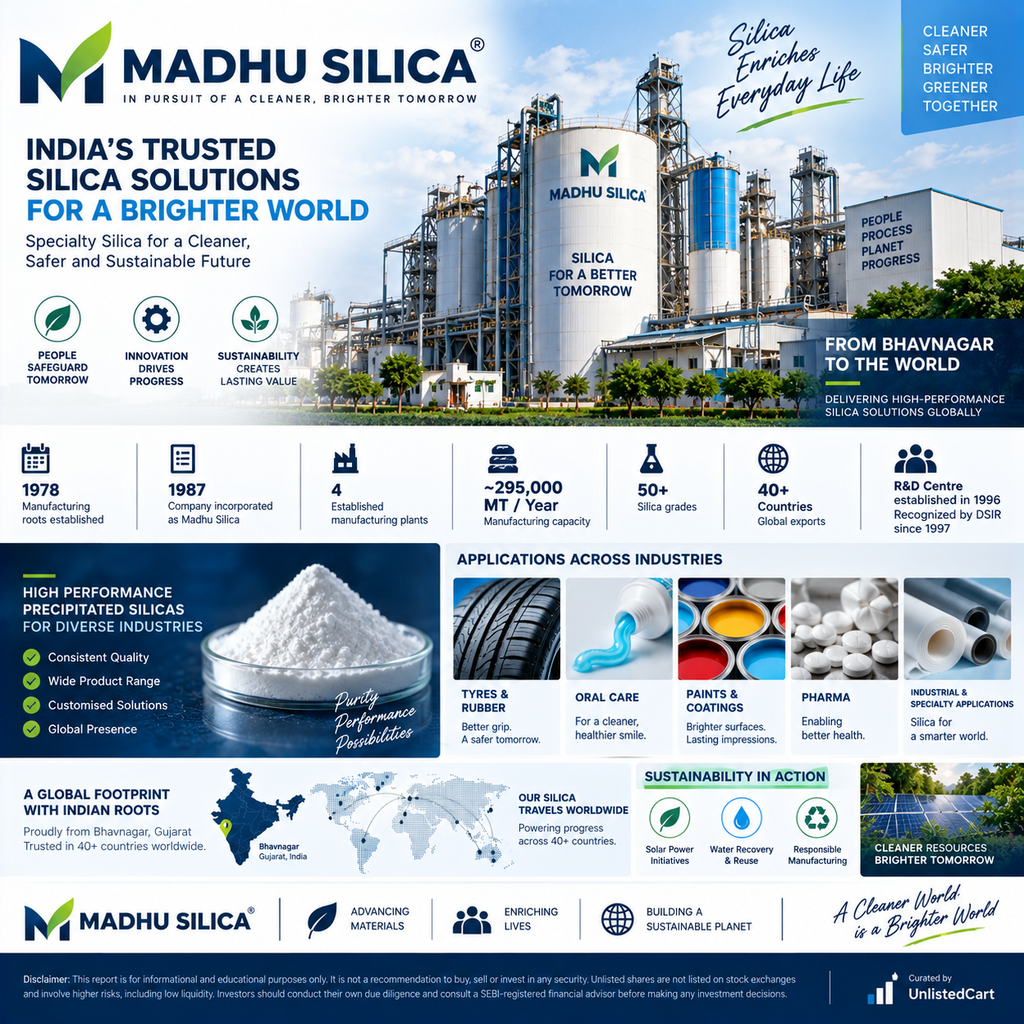
Madhu Silica Private Limited (MSPL) is an unlisted Indian specialty-chemical manufacturer headquartered in Bhavnagar, Gujarat. The company is focused primarily on precipitated silica and silicates, which are used across tyres, oral care, food, pharmaceuticals, paints, paper, detergents, cosmetics, pesticides, footwear and other industrial applications.
Madhu Silica – Official Website
Company Snapshot
| Particular | Details |
|---|---|
| Company | Madhu Silica Private Limited |
| CIN | U24299GJ1987PTC010073 |
| Incorporation | 20 October 1987 |
| Registered Office | Plot No. 147, GIDC Estate, Vartej, Bhavnagar, Gujarat |
| Status | Unlisted Private Company |
| Industry | Specialty Chemicals / Precipitated Silica |
| Paid-up Capital | ~₹9.25 Cr |
| Authorised Capital | ~₹10.20 Cr |
| Promoter Group | Ramesh Shah family / HUF |
| Managing Director | Darshak Rameshchandra Shah |
| Chairman / Whole-Time Director | Rameshchandra Vinaychand Shah |
| Latest reported revenue | ₹1,820.79 Cr – FY25 |
| Employees | ~1,104 |
| Credit Rating | CARE AA+; Stable / CARE A1+ |
The company remains an unlisted private limited company. MCA-based company information reports FY25 revenue of ₹1,820.79 Cr, while paid-up capital stood at approximately ₹9.25 Cr.
What Does Madhu Silica Do?
Madhu Silica manufactures precipitated silica, a specialty material used as a functional ingredient or additive across multiple industries.
The company states that it manufactures more than 50 grades of precipitated silica and serves customers in more than 40 countries.
Its major application areas include:
- Tyres & rubber
- Oral & dental care
- Food & anti-caking
- Pharmaceuticals
- Detergents
- Cosmetics
- Paints & coatings
- Paper
- Pesticides
- Animal feed
- Polymers & plastics
- Dry bonding applications
Why Is Precipitated Silica Important?
Precipitated silica is used to modify the physical and performance characteristics of products.
In tyres, silica can help reduce rolling resistance and consequently support fuel efficiency. Demand for silica is also linked to the increasing adoption of green-tyre technology. CARE Ratings identified the growth of green tyres and EVs as supportive factors for the long-term demand outlook for the industry.
In consumer and industrial applications, silica can provide properties such as:
- Anti-caking
- Absorption
- Flow improvement
- Reinforcement
- Rheology control
- Surface modification
Product & End-Market Diversification
One of the important characteristics of Madhu Silica is that its products are used across multiple industries.
According to CARE Ratings, FY24 revenue contribution was approximately:
| Application | Revenue Contribution – FY24 |
|---|---|
| Tyres | 35% |
| Oral Healthcare | 25% |
| Footwear & Rubber | 11% |
| Food / Free Flow | 10% |
| Paint & Paper | 8% |
| Detergents | 2% |
| Other industries | Balance |
The company also sells aluminosilicates for applications in the paint and paper industries.
This diversification reduces dependence on any single end-use industry.
Domestic & Export Presence
Madhu Silica has a meaningful international business.
CARE Ratings reported that approximately 57% of FY24 sales were domestic and 43% were exports, with exports reaching markets across Asia, Europe and the US.
The company’s own website says its products are exported to more than 40 countries.
Major Customers
CARE Ratings identified long-standing relationships with several major global and Indian companies, including:
- Unilever
- Hindustan Unilever
- Colgate-Palmolive
- Continental Tyres
- CEAT
- MRF
- Goodyear
- Apollo Tyres
- Asian Paints
- GSK
CARE noted that the company has had a relationship with the Unilever group for more than three decades.
These customer relationships can be particularly valuable in specialty chemicals because qualification and approval processes can create barriers to switching suppliers.
Manufacturing Capacity
CARE Ratings reported installed capacity of approximately 270,000 tonnes per annum as of March 31, 2024, while the company’s website currently describes four established plants with aggregate capacity of approximately 295,000 MT/annum, including an expansion completed in 2019.
The company’s manufacturing base is located in Bhavnagar, Gujarat.
Research & Development
R&D is an important part of the company’s business model.
Madhu Silica established its R&D centre in 1996, and the facility has been recognised by the Department of Scientific & Industrial Research (DSIR), Government of India, since 1997.
The R&D centre includes:
- Analytical laboratory
- Rubber application laboratory
- Toothpaste application section
- Instrumentation laboratory
- Pilot plant
The focus is on developing new applications, customised products, product characterisation and process improvements.
Financial Performance
FY23–FY24
CARE Ratings reported the following standalone financials:
| ₹ Crore | FY23 | FY24 |
|---|---|---|
| Operating Income | 1,644.19 | 1,502.86 |
| PBILDT | 406.81 | 390.40 |
| PAT | 340.34 | 368.06 |
| PBILDT Margin | 24.74% | 25.98% |
| PAT Margin | 20.70% | 24.49% |
| Net Worth | — | 1,885 |
| Fund-based Debt | Nil | Nil |
Despite a 9% decline in revenue during FY24, the company improved its operating margin and PAT margin. CARE attributed the revenue decline largely to a reduction in realisations caused by lower raw-material prices, partly offset by approximately 6% volume growth.
FY25
MCA-based company information reports FY25 revenue of ₹1,820.79 Cr, representing approximately 11% YoY growth over FY24.
Detailed FY25 profitability figures are not freely disclosed in the same source, so they should not be estimated or mixed with the older CARE figures.
H1 FY25 Performance
CARE reported provisional H1 FY25 revenue of approximately:
₹790.25 Cr
compared with ₹748 Cr in H1 FY24.
PBILDT was approximately ₹252 Cr and PAT was ₹279.58 Cr for H1 FY25.
The unusually high PAT relative to operating profit was influenced by non-operating income, including income from the company’s investment portfolio.
Balance Sheet Strength
One of the most notable aspects of Madhu Silica’s financial profile is its relatively conservative leverage.
CARE reported:
Net Worth: ₹1,885 Cr
as of March 31, 2024
Fund-Based Borrowings: Nil
The company had accumulated substantial reserves through internal accruals, while CARE noted that the company had not relied materially on debt-funded capex.
CARE also reported investments of approximately ₹1,549 Cr as of September 30, 2024, spread across quoted and unquoted investments.
Credit Rating
Madhu Silica has a strong external credit rating.
CARE Ratings reaffirmed:
CARE AA+; Stable
Long-Term
CARE A1+
Short-Term
The rated bank facilities were increased to approximately ₹200 Cr in November 2024.
The rating reflects:
- Long operating track record
- Leadership position in domestic precipitated silica
- Strong profitability
- Conservative leverage
- Established customer relationships
- Diversified end-user industries
- Strong liquidity
Promoter & Management
The company is promoter-controlled.
As of March 31, 2024, CARE reported that Ramesh Shah, his family members and the family-formed HUF collectively held 100% of the equity.
Current management includes:
- Rameshchandra Vinaychand Shah – Whole-Time Director
- Darshak Rameshchandra Shah – Managing Director
- Neepa Udaykant Mehta – Director
Company records show Darshak Shah has been associated with the company since 1997.
Competitive Position
Madhu Silica’s competitive position is supported by several factors.
1. Long operating history
The business traces its silica manufacturing roots back several decades, with the company stating that precipitated silica manufacturing began in 1978 and Madhu Silica was established under its present name in 1987.
2. Domestic leadership
CARE describes MSPL as the largest player in India’s precipitated silica industry.
3. Customer qualification
Specialty chemical products often require customer testing and approval before being adopted. CARE noted that technical competency, stringent quality requirements and lengthy product-approval processes can act as entry barriers.
4. Diversified applications
The company is not dependent exclusively on tyres; oral care, food, footwear, paints, paper, detergents, cosmetics and other applications contribute to demand.
5. Export footprint
Exports account for a substantial part of sales and provide geographic diversification.
Key Growth Drivers
Green Tyres
Silica is increasingly used in tyre formulations to improve rolling resistance characteristics. The expansion of green-tyre technology could support long-term demand.
EV Adoption
CARE has identified EV growth as a potential medium-term demand driver for precipitated silica.
Oral Care
The company supplies specialised dental silica used in toothpaste applications.
Specialty Applications
Increasing use in pharmaceuticals, food, cosmetics, paints and industrial formulations can support diversification beyond conventional rubber applications.
Key Risks
Raw Material Price Volatility
The major raw materials include sodium silicate and sulphuric acid. Changes in their prices can affect profitability. CARE noted that the company has historically been able to pass a significant portion of cost increases to customers, but maintaining that ability remains important.
Foreign Exchange Risk
Approximately 43% of FY24 sales came from exports, creating exposure to currency movements. The company uses forward contracts and foreign-currency working-capital arrangements to partially mitigate this risk.
Product Concentration
Although end applications are diversified, the company remains concentrated in precipitated silica compared with larger global specialty-chemical groups such as Evonik and Solvay. CARE specifically identifies this as a constraint.
Global Competition
Global competitors operate across larger geographical footprints and broader specialty-chemical portfolios.
Unlisted Liquidity
Madhu Silica is privately held and its shares are not traded on NSE or BSE. Therefore, liquidity can be substantially lower than listed securities.
IPO / Listing Status
Madhu Silica is currently an unlisted private company.
I could not verify a current SEBI DRHP or formal IPO timetable from reliable primary sources as of September 2026. Therefore, any unlisted-market discussion suggesting a confirmed IPO date, issue size or listing valuation should be treated as unverified unless supported by an official filing.
Important Valuation Point
Madhu Silica should not be valued simply by applying a listed chemical-company multiple to its revenue.
For an unlisted investor, the valuation analysis should consider:
- Latest audited FY25 financial statements
- FY26 profitability
- Net cash / debt position
- Investment portfolio
- Promoter ownership
- Number of outstanding shares
- Any recent private transactions
- Any proposed restructuring or IPO
- Liquidity discount
- Comparable specialty-chemical companies
The company has historically maintained a strong balance sheet and substantial investments, which means enterprise value and equity value need to be considered separately.
Investment Snapshot
| Parameter | Observation |
|---|---|
| Business | Precipitated silica & silicates |
| Industry | Specialty / Industrial Chemicals |
| Operating History | ~4 decades under current company structure |
| FY25 Revenue | ₹1,820.79 Cr |
| FY24 Operating Income | ₹1,502.86 Cr |
| FY24 PAT | ₹368.06 Cr |
| FY24 Net Worth | ₹1,885 Cr |
| FY24 Fund Debt | Nil |
| FY24 Export Contribution | ~43% |
| Manufacturing Capacity | ~270,000 MTPA reported by CARE for FY24 |
| Products | 50+ silica grades |
| Export Presence | 40+ countries |
| Credit Rating | CARE AA+ / Stable; A1+ |
| Listed | No |
| IPO | No verified current DRHP identified |
UnlistedCart Takeaway
Madhu Silica is an established Indian specialty-chemical manufacturer with a leadership position in precipitated silica, a diversified customer base, significant export exposure and a historically strong balance sheet.
The combination of high operating margins, zero fund-based debt as reported for FY24, strong net worth, established global customers, R&D capabilities and multiple end-use applications makes the company structurally different from a conventional commodity-chemical manufacturer.
At the same time, investors should monitor raw-material prices, export-related currency risk, product concentration, global competition and the price at which unlisted shares are actually available. The reported FY25 revenue of ₹1,820.79 Cr indicates continued scale growth, but a proper investment valuation requires the latest audited profitability and share-level transaction data.
Useful Links
Madhu Silica – Official Website
Madhu Silica – Company Overview
Madhu Silica – Products & Applications
CARE Ratings – Madhu Silica Rating Report
Company Information – Madhu Silica Private Limited
Disclaimer
This report is for informational and educational purposes only and should not be construed as investment advice, a recommendation, solicitation or an offer to buy or sell securities.
Madhu Silica Private Limited is an unlisted private company, and its shares are not traded on NSE/BSE. Any unlisted share price or transaction indication may differ materially from the company’s fundamental value because of limited liquidity, availability of sellers, transaction size, negotiation, transfer restrictions and other market factors.
Financial information in this report has been compiled from publicly available company information, credit-rating reports and corporate databases. Where different sources report different financial figures or reporting periods, the figures have been identified separately rather than combined.
Past financial performance is not indicative of future results. Investors should independently verify the latest audited financial statements, shareholding, valuation, taxation, legal status, transferability of shares and other relevant documents before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
