
Sector: Modular Furniture / Home Interiors / Furniture Manufacturing
Status: Unlisted Public Company
CIN: U31009HR2024PLC121198
ISIN: INE0YET01012
Incorporated: 1 May 2024
Registered Office: Manesar, Haryana
Face Value: ₹10/share
Paid-up Capital: ₹12.27 Cr
Equity Shares: 1.2267 Cr
Indicative Unlisted Price: ~₹88–₹117/share
Indicative Market Capitalisation: ~₹108–₹143 Cr
DRHP: Not filed / no confirmed IPO timetable
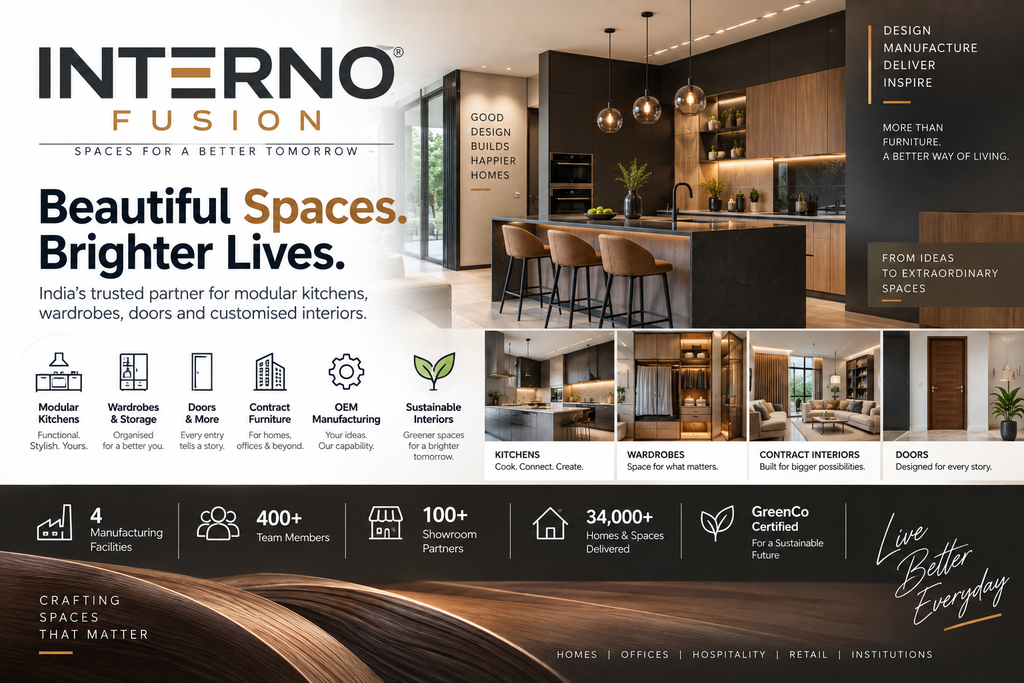
Interno Fusion is an Indian manufacturer of modular kitchens, wardrobes, doors and customised furniture solutions, serving residential, hospitality, retail, commercial and institutional customers. The business traces its operating history to 2012, when Fusion Kitchen was established, and adopted the Interno Fusion name in 2024.
About the Company
Interno Fusion operates across the complete furniture value chain—from design and engineering to manufacturing, finishing, installation and after-sales support.
Unlike a pure furniture retailer, the company focuses heavily on manufacturing and institutional/contract requirements. Its capabilities include customised modular solutions for showroom partners, mass production for large projects and OEM manufacturing.
The company operates manufacturing facilities in and around Manesar and Farukhnagar, Haryana, and says its products are available through 100+ showrooms across India.
Key Highlights
| Particular | Details |
|---|---|
| Industry | Modular Furniture & Interior Products |
| Core Products | Kitchens, wardrobes, doors, customised furniture |
| Operating History | 12+ years |
| Factories | 4 |
| Manufacturing Area | ~1.36 lakh sq. ft. reported by market sources |
| Showroom Partners | 100+ |
| Employees | 400+–500+ reported |
| Orders Completed | 34,000+ |
| Green Certification | GreenCo certified |
| Manufacturing Model | In-house + OEM + project manufacturing |
| Customers | Residential, hospitality, retail, commercial & institutional |
| Listing | Unlisted |
| DRHP | Not filed |
The company’s official website currently highlights 4 factories, 34,000+ orders and 400+ employees, while it describes its infrastructure as a large-scale integrated manufacturing operation.
Business Model
Interno Fusion operates through multiple channels.
1. Modular Kitchens
The company manufactures customised modular kitchens ranging from traditional Indian designs to contemporary formats.
Its production capabilities include:
- Modular cabinets
- Kitchen shutters
- Storage systems
- Counter solutions
- Accessories
- Custom configurations
2. Wardrobes & Storage
Interno Fusion manufactures modular wardrobes and storage systems designed for residential and commercial interiors.
3. Doors
The company manufactures premium interior doors and related products.
4. Contract Furniture
Large-scale projects require standardised furniture production at volume.
Interno Fusion provides manufacturing solutions for:
- Hotels
- Residential projects
- Offices
- Retail spaces
- Institutions
5. OEM Manufacturing
The company can manufacture products for other brands and showroom networks, allowing it to participate in the organised furniture ecosystem without necessarily owning the entire retail relationship.
6. Design-to-Installation
Its offering extends beyond manufacturing into:
Concept → Design → Engineering → Production → Finishing → Installation → After-sales
This integrated model can improve control over quality and project execution.
Manufacturing Capability
Interno Fusion’s operating infrastructure is one of its key differentiators.
Market sources report annual production capacity of approximately:
| Product | Annual Capacity |
|---|---|
| Modular Kitchens | ~7,800 |
| Wardrobes | ~12,400 |
| Doors | ~6,200 |
| Other Furniture Units | ~6,200 |
| Wood Boards Processed | ~3.2 lakh |
The company operates multiple production facilities around Manesar/Farukhnagar and uses automated/precision manufacturing equipment.
Its official website says Interno Fusion has approximately 2.60 lakh sq. ft. of infrastructure, although some unlisted-market sources cite a smaller manufacturing-area figure; the difference likely reflects differing definitions of total infrastructure versus specific production facilities.
Customer & Distribution Model
Interno Fusion has exposure to both B2B and B2C-linked demand.
B2B / Institutional
- Real-estate developers
- Hospitality
- Offices
- Institutions
- OEM customers
- Interior-design companies
Showroom / Retail Ecosystem
The company says its products are available through 100+ showroom partners nationwide.
This gives Interno Fusion an interesting position:
Manufacturing backbone + showroom ecosystem + contract projects + OEM capability
Sustainability
Interno Fusion has been recognised as a GreenCo-certified company and says it focuses on:
- Efficient resource utilisation
- Eco-friendly materials
- Waste reduction
- Sustainable manufacturing
- Environmental management
The company also highlights ISO certification and an integrated management system covering quality, environment, health and safety.
Financial Snapshot
FY25 – Standalone
The latest available statutory financial data for the current legal entity shows:
| ₹ Crore | FY25 |
|---|---|
| Revenue from Operations | ₹64.67 Cr |
| Other Income | ₹0.03 Cr |
| Total Income | ₹64.70 Cr |
| EBITDA | ~₹4.65 Cr |
| EBITDA Margin | 8.12% |
| PBT | ₹2.77 Cr |
| PAT | ₹1.95 Cr |
| PAT Margin | 3.01% |
| EPS | ~₹1.59 |
| Net Worth | ~₹22.20 Cr |
| Total Assets | ~₹36.71 Cr |
Balance Sheet
| Particular | FY25 |
|---|---|
| Shareholders’ Funds | ₹22.20 Cr |
| Long-term Borrowings | ₹1.52 Cr |
| Short-term Borrowings | ₹1.66 Cr |
| Total Debt | ~₹3.18 Cr |
| Inventory | ₹23.20 Cr |
| Trade Receivables | ₹6.27 Cr |
| Cash & Equivalents | ₹0.17 Cr |
| Total Assets | ₹36.71 Cr |
Important Financial Observation
The business is profitable, but cash generation needs attention.
FY25 operating cash flow was approximately -₹14.78 Cr, while inventory stood at ₹23.2 Cr.
For a manufacturing business, inventory and working-capital requirements can materially influence actual shareholder returns.
Historical / Management Growth Story
Several unlisted-market sources cite:
| FY | Revenue |
|---|---|
| FY24 | ~₹98 Cr |
| FY25 | ~₹151 Cr* |
| FY26E | ~₹210 Cr |
*These figures appear in market/investor materials and do not directly reconcile with the ₹64.67 Cr FY25 statutory financials of the current legal entity. This may reflect the underlying operating business, restructuring/transfer arrangements or a different reporting perimeter.
For UnlistedCart, I would not present ₹151 Cr FY25 as audited revenue unless the underlying consolidated/transfer documentation is independently verified.
The safer figure to publish as the statutory FY25 number is ₹64.67 Cr revenue and ₹1.95 Cr PAT.
Shareholding Pattern
As of March 31, 2025, WWIPL reports:
| Category | Holding |
|---|---|
| Promoters | 77.68% |
| Public | 22.32% |
| Total | 100% |
Other current market sources show somewhat different promoter percentages, so the latest filed shareholding should be checked before executing a transaction.
Capital Raise
Interno Fusion raised approximately ₹11 Cr during 2024 through multiple private-placement transactions.
Reported allotments included:
- ₹5.02 Cr at ₹37/share
- ₹4.01 Cr at ₹37/share
- ₹1.81 Cr at ₹59/share
The company has subsequently invested in manufacturing capacity and business expansion.
Valuation
Current unlisted-market prices show large discrepancies.
| Source | Indicative Price |
|---|---|
| UnlistedZone | ~₹88 |
| Moneycontrol | ~₹116.85 |
| Neoma Capital | ~₹277* |
*The Neoma page appears to use a materially different valuation/share-count basis, so it should not be directly compared with the statutory 1.2267 Cr shares without reconciliation.
Using the current statutory share count of approximately 1.2267 Cr shares:
At ₹88/share
Market Cap ≈ ₹108 Cr
At ₹116.85/share
Market Cap ≈ ₹143 Cr
At ₹116.85 and FY25 EPS of approximately ₹1.59, the implied P/E would be roughly 73x on the current entity’s FY25 earnings.
This is a premium valuation for a furniture manufacturer.
Why Investors May Find It Interesting
1. India’s Modular Furniture Opportunity
Indian consumers are increasingly moving from traditional carpentry toward:
- Modular kitchens
- Factory-made wardrobes
- Branded interiors
- Customised furniture
- Integrated interior solutions
2. Manufacturing Advantage
Interno Fusion is building an integrated manufacturing platform rather than relying purely on third-party suppliers.
3. Multiple Customer Segments
The company can sell through:
Showrooms + OEM + Developers + Hospitality + Commercial + Institutional
4. Scale Potential
Four factories and a large manufacturing footprint provide the ability to service larger orders as demand grows.
5. Organised Market Shift
India’s furniture industry remains fragmented, giving organised manufacturers an opportunity to gain share through:
- Quality
- Standardisation
- Faster delivery
- Technology
- Design
- Installation support
6. Sustainability Positioning
GreenCo certification and resource-efficiency initiatives can become increasingly relevant for institutional and premium customers.
Key Risks
| Risk | Why It Matters |
|---|---|
| Low Profit Margin | FY25 PAT margin was only ~3%. |
| Negative Operating Cash Flow | FY25 operating cash flow was ~-₹14.8 Cr. |
| Working Capital | Inventory of ₹23.2 Cr is significant relative to revenue. |
| Customer Concentration | Heavy dependence on large B2B/platform customers can create revenue volatility. |
| Unlisted Liquidity | Exit depends on finding private buyers. |
| Valuation Risk | At ₹100+ the implied earnings multiple becomes demanding. |
| Furniture Competition | Fragmented market with intense local and organised competition. |
| Raw Material Risk | Wood-based products are sensitive to input-cost movements. |
| Real Estate Cyclicality | Housing and construction cycles influence demand. |
| IPO Uncertainty | No DRHP has been publicly verified. |
| Execution Risk | Scaling factories and showroom relationships requires capital and operational discipline. |
Customer Concentration – Important Risk
This deserves particular attention.
Recent unlisted-market research indicates that Interno Fusion has exposure to large customers/platforms including HomeLane, Livspace and Asian Paints’ kitchen business, and that a reduction in one customer’s order volumes affected revenue.
This creates a classic B2B-manufacturer risk:
Strong customer relationships can accelerate growth—but losing one major account can materially impact revenue.
Investors should therefore monitor customer concentration rather than looking only at total order numbers.
IPO / Pre-IPO Status
Interno Fusion is currently unlisted.
Moneycontrol currently shows DRHP Status: No, meaning there is no publicly verified DRHP on that platform.
Therefore, the appropriate UnlistedCart wording is:
“Unlisted Furniture & Interior Manufacturing Company with potential future IPO optionality.”
Do not advertise a fixed IPO date or guaranteed listing.
Investment Rationale
Bull Case
India’s modular furniture market expands
→ Organised manufacturers gain market share
→ Interno Fusion expands production
→ More showroom/OEM/project customers
→ Better capacity utilisation
→ Operating margins improve
→ Scale creates stronger profitability
→ Potential future IPO
Bear Case
Customer concentration
→ Order volatility
→ High inventory
→ Negative operating cash flow
→ Low PAT margins
→ Valuation compression
→ Difficult exit because shares are unlisted
Our Assessment
| Parameter | Rating |
|---|---|
| Industry Opportunity | ⭐⭐⭐⭐⭐ |
| Manufacturing Capability | ⭐⭐⭐⭐☆ |
| Product Portfolio | ⭐⭐⭐⭐☆ |
| Brand / Distribution | ⭐⭐⭐⭐☆ |
| Revenue Visibility | ⭐⭐⭐☆☆ |
| Profitability | ⭐⭐☆☆☆ |
| Cash Flow | ⭐⭐☆☆☆ |
| Balance Sheet | ⭐⭐⭐☆☆ |
| Valuation Comfort | ⭐⭐☆☆☆ |
| Liquidity | ⭐⭐☆☆☆ |
| IPO Visibility | ⭐⭐☆☆☆ |
| Overall Risk | Medium–High |
Investment View
Interno Fusion is an interesting manufacturing story, but investors should not confuse revenue scale with profitability.
The company has built:
4 factories + 100+ showroom partners + OEM capability + project manufacturing + modular kitchens + wardrobes + doors
and has been operating in the sector for more than a decade.
But the latest statutory financials show:
₹64.67 Cr revenue → ₹1.95 Cr PAT
with ~3% net margin and negative operating cash flow.
Therefore, the investment thesis depends heavily on:
- Revenue growth
- Better capacity utilisation
- Margin expansion
- Customer diversification
- Working-capital control
- Stronger operating cash flow
Final Verdict
Business: ⭐⭐⭐⭐☆
Industry: ⭐⭐⭐⭐⭐
Growth Potential: ⭐⭐⭐⭐☆
Profitability: ⭐⭐☆☆☆
Valuation: ⭐⭐☆☆☆
Liquidity: ⭐⭐☆☆☆
Risk: Medium–High
UnlistedCart Positioning
“India’s Modular Furniture & Interior Manufacturing Play — Growth Opportunity with Execution & Working-Capital Risk.”
This is not a pure premium-consumer brand play. The more interesting thesis is the company’s potential to become a large-scale manufacturing and B2B interior-solutions platform.
How to Invest
Interno Fusion is currently unlisted, so shares are transferred through off-market transactions rather than NSE/BSE.
Current indicative prices vary substantially across intermediaries, approximately ₹88–₹117 in some current sources.
Before investing, verify:
- Exact executable price
- Quantity available
- Latest shareholding
- Latest audited financials
- Customer concentration
- Current debt
- Working-capital position
- Any promoter pledge/encumbrance
- Latest valuation
- IPO/DRHP status
Disclaimer
This profile is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. Interno Fusion Limited is an unlisted security and carries liquidity, valuation, customer-concentration, working-capital and execution risks. Unlisted-market prices are indicative and can vary materially between intermediaries. Investors should independently verify the latest audited financial statements, shareholding, capital structure, valuation and IPO filings before investing.
Official company website: Interno Fusion
For much unlisited stocks visit https://unlistedcart.com/unlisted-shares/
