
Unlisted Equity Research Report | Updated September 2026
Category: Telecom Infrastructure / ISP / Enterprise IT Services
Status: Active & Unlisted Public Company
IPO Status: DRHP Filed – NSE Emerge
CIN: U64200HR2019PLC081805
Former Name: HCIN Networks Private Limited
Brand: Hi-COM
Incorporated: 2 August 2019
Registered Office: Gurugram, Haryana
Promoters: Vikas and Shalini
Face Value: ₹10
ISIN: INE0U7Y01027
About the Company
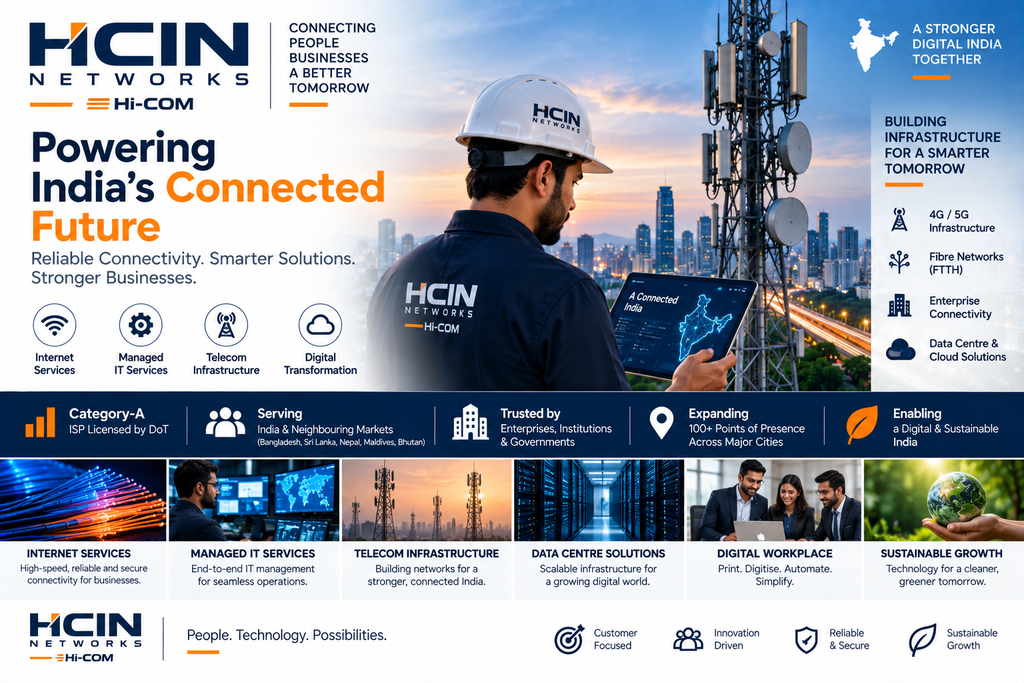
HCIN Networks Limited, operating under the Hi-COM brand, is an Indian telecom and enterprise technology company providing connectivity, managed IT and telecom infrastructure solutions.
The company was incorporated in 2019 as HCIN Networks Private Limited and was converted into a public limited company in 2024. Its current CIN is U64200HR2019PLC081805.
HCIN operates as a Category-A Internet Service Provider (ISP) licensed by the Department of Telecommunications, giving it authorisation to provide internet services across India. The Department of Telecommunications’ 2026 ISP list continues to show HCIN Networks Limited as a Category-A, national-area ISP.
The business combines recurring connectivity services with project-based telecom infrastructure and enterprise IT services.
Key Highlights
| Particular | Details |
|---|---|
| Incorporated | 2019 |
| Current Status | Active & Unlisted |
| FY24 Revenue from Operations | ₹25.39 Cr |
| FY24 PAT | ₹7.08 Cr |
| FY24 EBITDA | ₹8.87 Cr |
| FY24 EBITDA Margin | ~36.0% |
| FY24 PAT Margin | ~28.0% |
| FY24 Net Worth | ~₹21.19 Cr |
| Current Indicative Price | ~₹175/share |
| Indicative Market Cap | ~₹225 Cr |
| Indicative P/E on FY24 PAT | ~32x |
| IPO | DRHP filed |
| Proposed Exchange | NSE Emerge |
| Proposed Fresh Issue | Up to 55 lakh shares |
| Lead Manager | Swastika Investmart |
FY24 financials above are from the company’s NSE-filed DRHP and restated financial statements.
Business Model
HCIN operates across three primary segments:
1. Internet Services
The company provides enterprise connectivity solutions including:
- Internet Leased Lines
- Business Broadband
- SD-WAN
- Enterprise connectivity
- FTTH networks
- Network access solutions
Internet connectivity provides the company with a potentially recurring revenue component.
2. Managed IT Services
HCIN provides:
- Managed IT infrastructure
- Remote IT support
- Data-centre management
- IT system integration
- IT security
- Network management
- Hardware/software integration
The company works with providers of hardware, software, storage, networking, security, voice and consulting solutions. It also operates a 24/7 post-sales support function.
3. Telecom Infrastructure
This is an important part of the growth story.
HCIN undertakes:
- FTTH network deployment
- Optical-fibre networks
- Tower construction
- Ground tower infrastructure
- Telecom O&M
- 5G infrastructure support
- Solar upgrades
- Telecom network deployment
The company works with telecom operators and B2B customers for infrastructure deployment and maintenance.
Why the Business Could Benefit
India’s telecom ecosystem is undergoing continued investment in:
4G → 5G → Fibre → Enterprise Connectivity → Data Centres → Cloud → Network Security
HCIN operates across several of these layers.
This gives the company an opportunity to participate in the broader digital-infrastructure expansion rather than relying only on consumer broadband.
Customer Profile
HCIN has worked with enterprise and institutional customers/projects including names such as:
- ABB
- Decathlon
- Federal Bank
- MAX Hospital
- Shell
- Airtel
- Nagarjuna
- Bhavya Bharat
The company stated in its DRHP that new ISP customers and projects contributed materially to FY24 growth.
However, customer concentration remains an important consideration.
For FY24, approximately 69.26% of revenue came from the top 10 customers, and the company also disclosed that many customer relationships are not supported by long-term written supply agreements.
Financial Performance
Revenue & Profitability
| ₹ Crore | FY22 | FY23 | FY24 |
|---|---|---|---|
| Revenue from Operations | 6.86 | 15.97 | 25.39 |
| EBITDA | 0.31 | 0.49 | 8.87 |
| EBITDA Margin | 4.6% | 3.1% | ~36.0% |
| PAT | 0.10 | 0.002 | 7.08 |
| PAT Margin | 1.5% | ~0% | ~27.9% |
HCIN’s reported FY24 performance represents a very sharp improvement over FY23.
Revenue increased approximately 59%, while EBITDA increased dramatically from ₹0.49 Cr to about ₹8.87 Cr. FY24 PAT reached approximately ₹7.08 Cr.
Important Equity-Research Observation
The sharp jump in FY24 profitability deserves deeper analysis.
The business moved from an EBITDA margin of roughly 3% in FY23 to ~36% in FY24.
That is a very significant change for a telecom/IT infrastructure company.
Therefore, investors should examine:
- Project mix
- Gross margins
- Revenue recognition
- One-off project contribution
- Recurring ISP revenue
- Working-capital requirements
- Sustainability of FY24 margins
before extrapolating FY24 earnings indefinitely.
FY25 Financial Data — Important Data Caveat
Some current third-party databases report substantially different FY25 numbers.
For example, Inc42 currently displays ₹32.7 Cr total revenue and ₹2 Cr PAT in one section, while the same page’s FAQ reports ₹39.3 Cr revenue and ₹3.2 Cr PAT.
Because these figures do not reconcile, this report does not use either third-party FY25 number for valuation calculations.
For valuation purposes, the cleaner reference remains the audited/restated FY24 financials disclosed in the company’s NSE DRHP.
This is an important distinction for an investor because using ₹3.2 Cr instead of ₹7.08 Cr PAT would materially change the apparent valuation.
Balance Sheet & Working Capital
Working capital is one of the most important areas to monitor.
The DRHP shows net working capital of approximately:
| Period | Net Working Capital |
|---|---|
| FY22 | ₹0.32 Cr |
| FY23 | ₹1.93 Cr |
| FY24 | ₹13.79 Cr |
| June 2024 | ₹22.85 Cr |
The company stated that its working-capital requirement was expected to rise further as it expanded operations. It proposed using IPO proceeds partly for working capital.
This indicates that growth is capital-intensive.
Revenue growth alone therefore should not be viewed as equivalent to free-cash-flow growth.
Expansion Plan
One of the more interesting expansion plans disclosed in the DRHP was the proposed establishment of approximately 100 Points of Presence (PoPs) across major metropolitan markets, including:
- Delhi-NCR
- Bengaluru
- Mumbai
- Hyderabad
- Chennai
- Kolkata
The objective is to create strategic network-access points and improve the company’s ability to provide telecom and IT services across major business centres.
If executed successfully, this could increase the recurring connectivity component of the business and improve geographic diversification.
IPO Status
DRHP Filed — IPO Not Yet Completed
HCIN Networks filed its Draft Red Herring Prospectus on 14 November 2024 for a proposed SME IPO on NSE Emerge.
The DRHP proposed a fresh issue of up to 55 lakh equity shares with no offer-for-sale component.
Book Running Lead Manager: Swastika Investmart Limited
Registrar: Maashitla Securities Private Limited
The company’s own investor page currently maintains IPO-related documents including DRHP/RHP/prospectus sections.
However, current public IPO databases still do not show a confirmed issue price, opening date, allotment date or listing date.
Therefore:
IPO is planned / process initiated, but listing is not confirmed.
Investors should not assume that a DRHP automatically means a near-term listing.
Proposed Use of IPO Funds
The DRHP indicated that the company intended to use IPO proceeds primarily for:
- Expansion of working capital
- Network/PoP expansion
- Business expansion
- General corporate purposes
The DRHP specifically highlighted the increasing working-capital requirement associated with the company’s expansion.
Shareholding
The company had a highly promoter-dominated ownership structure before the proposed IPO.
Historical shareholding disclosed in the DRHP shows Shalini holding 99.98% at the relevant earlier period.
The proposed fresh issue would substantially increase the public shareholding if the IPO proceeds.
For an investor, this creates two contrasting factors:
Positive: Promoters have significant economic ownership.
Concern: Public float is currently extremely limited, contributing to private-market liquidity risk.
Unlisted Share Price
As of September 10, 2026, Planify reports an indicative HCIN Networks price of approximately ₹174.40/share, while UnlistedZone reports approximately ₹175/share as of September 9, 2026. Moneycontrol shows approximately ₹175.75.
Therefore, a reasonable current private-market reference is:
~₹175/share
This is an indicative OTC/private-market reference, not an NSE/BSE traded price.
Indicative Valuation
Using approximately:
₹175/share × 1.28768 Cr shares
gives an indicative equity value of approximately:
₹225 Cr
Using FY24 PAT of approximately ₹7.08 Cr:
Indicative FY24 P/E ≈ 32x
This is not a low valuation for a small telecom/IT infrastructure company.
However, the market may be pricing in:
- IPO optionality
- Future revenue growth
- Expansion of recurring ISP revenues
- 100-PoP expansion
- 5G infrastructure opportunity
- Improved scale economics
- Higher future earnings
Valuation Perspective
At ~₹175, HCIN Networks should not be evaluated simply on FY24 P/E.
The more important question is whether the company can sustain the FY24 profitability improvement.
Bull Case
If the company can:
- Maintain strong revenue growth
- Convert infrastructure projects into recurring customers
- Expand its ISP/leased-line business
- Successfully deploy new PoPs
- Maintain healthy EBITDA margins
- Reduce working-capital intensity
then future earnings could potentially justify the current valuation.
Bear Case
If FY24’s unusually high margins were partly project-driven and normalised margins fall materially, then the current valuation could prove demanding.
Investment Positives
1. High Revenue Growth
Revenue from operations grew from approximately ₹6.86 Cr in FY22 to ₹25.39 Cr in FY24.
2. Strong FY24 Profitability
FY24 PAT of ₹7.08 Cr represented a major improvement over previous years.
3. Category-A ISP Licence
The company holds a national-area Category-A ISP licence, providing an important regulatory platform for its connectivity business.
4. Multiple Business Verticals
The company isn’t dependent on a single service.
It combines:
ISP + Managed IT + Telecom Infrastructure + Fibre + Data Centre + Network Security
5. 5G & Fibre Opportunity
The increasing deployment of fibre and next-generation telecom networks creates a long-term opportunity for infrastructure vendors and service providers.
6. IPO Optionality
The DRHP provides a defined pathway toward an NSE Emerge listing, although the actual IPO timetable remains uncertain.
7. Enterprise Customer Base
The company has worked with established enterprise customers, providing potential credibility for further B2B expansion.
Key Concerns
1. Customer Concentration
Top 10 customers contributed around 69.26% of FY24 revenue. This is a meaningful concentration risk.
2. Working-Capital Intensity
Net working capital rose sharply as the business expanded.
This means accounting profit may not translate into equivalent free cash flow.
3. Margin Sustainability
The jump from approximately 3% EBITDA margin in FY23 to ~36% in FY24 is exceptionally large.
Investors should determine whether this is sustainable.
4. Small Scale
Even after significant growth, HCIN remains a relatively small company compared with established telecom infrastructure and IT-services players.
5. Competition
The company operates in markets containing much larger players with significantly greater financial resources and network scale.
6. Technology Risk
Telecom infrastructure evolves rapidly.
The company must continually invest in:
- Fibre
- 5G
- Network security
- Data centres
- SD-WAN
- Cloud connectivity
to remain competitive.
7. IPO Uncertainty
A DRHP is not a guarantee of listing.
There is currently no verified final issue price or confirmed listing date.
8. Unlisted Liquidity
The shares are not traded on NSE/BSE today.
Private-market exit depends on finding a buyer and completing the transfer process.
9. Related-Party Transactions
The DRHP contains several related-party transactions involving promoter/director-linked entities. Investors should examine the nature, pricing and recurrence of these transactions before investing.
Share Details
| Particular | Details |
|---|---|
| Company | HCIN Networks Limited |
| Former Name | HCIN Networks Private Limited |
| CIN | U64200HR2019PLC081805 |
| ISIN | INE0U7Y01027 |
| Face Value | ₹10 |
| Shares Outstanding | 1,28,76,800 |
| Status | Unlisted |
| Indicative Price | ~₹175 |
| Indicative Market Cap | ~₹225 Cr |
| Proposed IPO | Up to 55 lakh fresh shares |
| Exchange Proposed | NSE Emerge |
| Lead Manager | Swastika Investmart |
| Brand | Hi-COM |
Current ISIN and share-count references are reported by current unlisted-market sources.
Investment View
HCIN Networks — High-Growth Telecom Infrastructure Opportunity with IPO Optionality
HCIN Networks is an interesting small-cap unlisted telecom infrastructure and enterprise connectivity business.
The company has demonstrated strong revenue growth, achieved a substantial improvement in profitability in FY24, holds a national-area Category-A ISP licence and operates across several attractive areas including fibre, enterprise connectivity, managed IT, data centres and 5G infrastructure.
The proposed 100-PoP expansion and IPO pathway add further optionality.
However, the investment case is not without significant risks.
The biggest areas requiring deeper analysis are:
Customer concentration → Working capital → Margin sustainability → Related-party transactions → IPO execution
The FY24 margin expansion is particularly important. If the higher profitability is sustainable, the current valuation can be viewed differently; if margins normalise sharply, the current ~32x FY24 P/E becomes considerably less comfortable.
Investment Scorecard
| Parameter | View |
|---|---|
| Business Opportunity | ⭐⭐⭐⭐☆ |
| Revenue Growth | ⭐⭐⭐⭐☆ |
| Profitability | ⭐⭐⭐⭐☆ |
| Balance Sheet | ⭐⭐⭐☆☆ |
| Recurring Revenue Visibility | ⭐⭐⭐☆☆ |
| IPO Visibility | ⭐⭐⭐⭐☆ |
| Valuation Comfort | ⭐⭐⭐☆☆ |
| Liquidity | ⭐⭐☆☆☆ |
| Overall Risk | High |
Investment Category
High-Growth Telecom / Enterprise Connectivity / Pre-IPO Opportunity
Overall View
Interesting business — but valuation should be assessed against sustainable earnings rather than the headline FY24 profit.
For investors considering HCIN Networks, the opportunity becomes more attractive if the company demonstrates:
- Continued double-digit revenue growth
- Normalised EBITDA margins remaining healthy
- Better operating cash flow
- Lower customer concentration
- Controlled working-capital requirements
- Clear progress toward the proposed NSE Emerge IPO
How to Invest
HCIN Networks shares are currently unlisted and are available through private-market transactions rather than NSE/BSE.
Current indicative market references are around ₹174–176/share, but these should not be treated as executable exchange prices.
Before purchasing, investors should verify:
- ISIN
- Exact security
- Current seller quote
- Number of shares
- Demat availability
- Transfer process
- Latest financial statements
- Any lock-in/restrictions
- Transaction charges
- IPO status at the time of purchase
Final Takeaway
HCIN Networks is a relatively small but rapidly expanding telecom and enterprise technology company positioned around India’s digital-infrastructure cycle.
Its combination of Category-A ISP licensing, enterprise connectivity, managed IT, fibre infrastructure, telecom projects and 5G-related capabilities provides a credible growth platform.
The DRHP filing is a major positive, but investors should remember that a proposed IPO is not the same as a confirmed listing.
At approximately ₹175/share and ~₹225 Cr indicative market capitalisation, the stock offers meaningful upside optionality if earnings continue to scale, but the valuation leaves less room for execution mistakes.
Investment View: Selective / High-Risk Growth Opportunity
Best suited for investors who understand unlisted-market liquidity risk and are willing to track quarterly/annual financial performance, working capital and IPO developments closely.
Disclaimer
This report is prepared for informational and research purposes only and should not be considered investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Unlisted-share prices are indicative private-market references and may vary significantly between buyers and sellers. Financial information from third-party databases can also differ from statutory filings; where material discrepancies exist, investors should rely on the latest audited financial statements and official company filings.
Investors should independently verify the company’s latest financials, shareholding, ISIN, transferability, valuation, IPO status, taxation and applicable regulatory requirements before making any investment decision.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
