
Company Overview
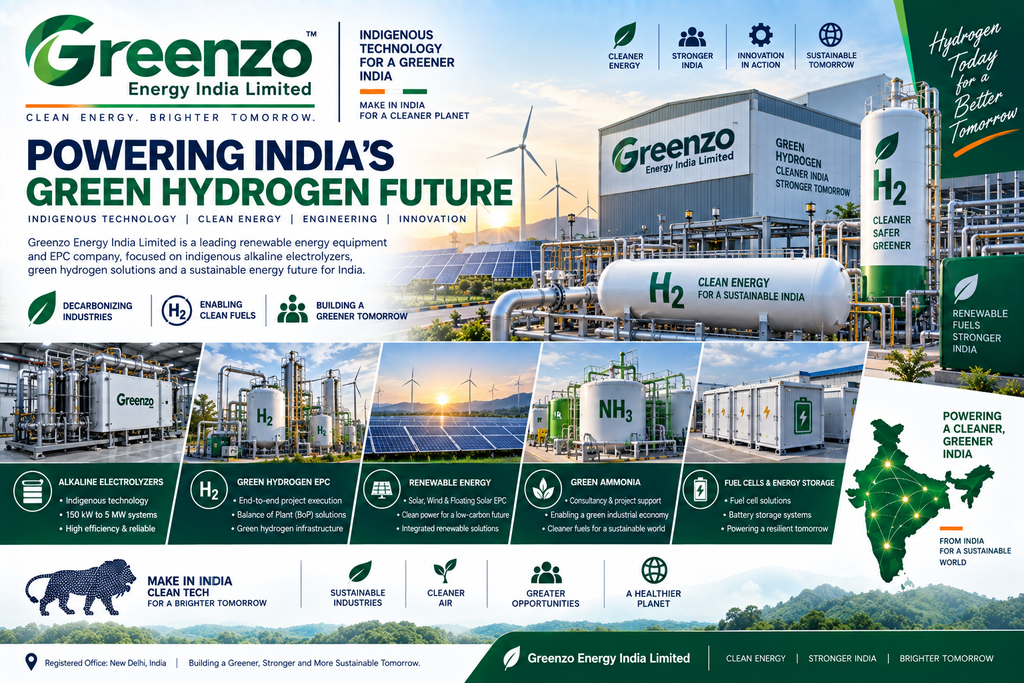
Greenzo Energy India Limited (GEIL) is an unlisted public company operating in the renewable-energy and green-hydrogen sector.
The company was incorporated in November 2022 and is headquartered in New Delhi. Its business focuses on alkaline electrolyser manufacturing, green-hydrogen systems, balance-of-plant equipment, renewable-energy EPC and related clean-energy solutions.
Greenzo has been positioning itself as an integrated green-hydrogen technology company, with products ranging from 150 kW to 5 MW alkaline electrolysers and associated balance-of-plant systems.
The company is also developing a 250 MW-per-year electrolyser manufacturing facility in Ahmedabad, Gujarat, intended to increase its manufacturing capacity and support larger hydrogen projects.
Company Name: Greenzo Energy India Limited
CIN: U29309DL2022PLC407203
ISIN: INE0OA401013
Face Value: ₹10 per share
Listing Status: Unlisted
Industry: Renewable Energy / Green Hydrogen / Electrolyser Manufacturing
Headquarters: New Delhi
Manufacturing Facility: Sanand Industrial Area, Ahmedabad, Gujarat
Business Model
Greenzo Energy operates across several areas of the clean-energy value chain.
1. Alkaline Electrolysers
Electrolysers use electricity to split water into hydrogen and oxygen.
Greenzo manufactures indigenous alkaline electrolyser systems ranging from approximately 150 kW to 5 MW. The company also develops electrolyser stacks and associated balance-of-plant equipment.
The company’s strategy is to build an integrated offering rather than only supplying individual electrolyser components.
2. Green Hydrogen EPC
Greenzo undertakes engineering, procurement and construction activities for green-hydrogen projects.
Its scope can include:
- Electrolyser supply
- Balance-of-plant equipment
- Hydrogen generation systems
- Installation
- Commissioning
- Automation and SCADA
- Training
- Operations support
This provides the company with potential revenue opportunities beyond the sale of individual electrolysers.
3. Balance of Plant
An electrolyser project requires several systems apart from the electrolyser itself.
Greenzo supplies and integrates equipment such as:
- Compressors
- Dryers
- Pumps
- Control systems
- Rectifiers
- Transformers
- Storage systems
- HVAC systems
- Hydrogen handling equipment
This allows the company to participate in a larger portion of the project value chain.
4. Renewable Energy EPC
Greenzo also undertakes renewable-energy EPC projects, including solar projects.
In November 2024, the company announced a 120 MW solar EPC project in Nepal valued at ₹500 crore, taking its reported order book at that time to approximately ₹1,900 crore.
5. Hydrogen R&D
The company is also involved in research and development projects related to hydrogen technologies.
Its project portfolio includes electrolyser deployments and R&D-related hydrogen projects, supporting its transition toward technology-oriented clean-energy manufacturing.
Manufacturing Capacity
Greenzo is developing a 250 MW annual electrolyser manufacturing facility in Ahmedabad.
The facility is intended to manufacture alkaline electrolyser systems and support larger domestic and international green-hydrogen projects.
The company describes the facility as a key part of its strategy to develop indigenous electrolyser manufacturing capabilities.
The success of this expansion will depend on:
- Manufacturing utilization
- Product competitiveness
- Electrolyser efficiency
- Cost per MW
- Technology development
- Project execution
- Customer adoption
Major Projects & Orders
Jindal Stainless – Green Hydrogen Project
One of Greenzo’s most significant disclosed customer relationships is with Jindal Stainless.
In September 2025, Greenzo announced an order to supply, install and commission an electrolyser-based green-hydrogen plant at Jindal Stainless’ Kalinga Nagar facility in Jajpur, Odisha.
The project is designed for approximately:
472,409 kg of hydrogen per year
or approximately:
0.47 KTPA initially
with scalability to approximately 1.5 KTPA.
The hydrogen is intended for use in stainless-steel manufacturing processes, including the Bright Annealing Line and Bell Furnace.
Jindal Stainless subsequently stated that the project was targeted for completion around mid-2026.
This project is strategically important because it demonstrates an industrial application of Greenzo’s electrolyser technology rather than a purely demonstration-scale use case.
Oswal Energies – ₹320 Crore Order
In June 2025, Greenzo announced a ₹320 crore order from Oswal Energies for electrolysers and balance-of-plant equipment for a 20 MW green-hydrogen facility in Gujarat.
The project was expected to be executed over approximately 12–15 months.
Following the order, Greenzo stated that its total order book had reached approximately ₹1,800 crore.
Nepal Solar EPC
Greenzo secured a 120 MW ground-mounted solar EPC project in Nepal worth approximately ₹500 crore in 2024.
The project was divided into 12 clusters of 10 MW each and included associated transmission infrastructure.
Order Book
Greenzo has communicated a significant order-book figure relative to its current reported revenue.
| Period | Reported Order Book |
|---|---|
| September 2024 | ~₹1,200 Cr |
| November 2024 | ~₹1,900 Cr |
| June 2025 | ~₹1,800 Cr |
The ₹1,800 crore figure was the company’s reported order book following the Oswal Energies order in June 2025.
The large difference between the order book and reported FY25 revenue is one of the most important aspects of the investment case.
A large order book can provide substantial future revenue visibility, but it does not automatically translate into revenue, profits or cash flow. Execution speed, project milestones, working capital and customer payments will determine how much of the order book is ultimately converted into financial performance.
Financial Performance
FY24–FY25
| Particulars | FY24 | FY25 |
|---|---|---|
| Revenue from Operations | ₹14.79 Cr | ₹15.97 Cr |
| Other Income | ₹0.09 Cr | ₹1.29 Cr |
| Total Income | ₹14.88 Cr | ₹17.26 Cr |
| PBT | ₹1.31 Cr | ₹1.94 Cr |
| PAT* | ~₹1.0–1.4 Cr | ~₹1.4 Cr |
| EPS | ₹1.81 | ₹1.16 |
Publicly available financial databases report FY25 revenue from operations of approximately ₹15.97 crore and total income of approximately ₹17.26 crore, compared with ₹14.79 crore and ₹14.88 crore respectively in FY24.
The reported PBT increased from approximately ₹1.31 crore to ₹1.94 crore.
There is a discrepancy across secondary financial databases regarding the exact FY25 PAT presentation. The annual-financial data reproduced by several unlisted-share platforms reports approximately ₹1.37–₹1.38 crore PAT and EPS of ₹1.16. Investors should therefore verify the exact figure against the company’s audited annual report before using it for valuation.
Balance Sheet
FY25 Balance Sheet
| Particulars | FY25 |
|---|---|
| Equity Share Capital | ₹11.85 Cr |
| Reserves & Surplus | ₹65.62 Cr |
| Net Worth | ~₹77.48 Cr |
| Long-Term Borrowings | Nil |
| Trade Payables | ₹3.43 Cr |
| Inventory | ₹18.04 Cr |
| Trade Receivables | ₹18.11 Cr |
| Cash & Cash Equivalents | ₹5.06 Cr |
| Short-Term Loans & Advances | ₹19.83 Cr |
| Total Assets | ₹81.89 Cr |
Greenzo’s balance sheet is relatively lightly leveraged. Long-term borrowings were reported at nil at March 2025, while net worth was approximately ₹77.5 crore.
However, the reduction in cash from approximately ₹43.82 crore in FY24 to approximately ₹5.06 crore in FY25 deserves attention.
The company has been deploying capital toward expansion and working capital, which has significantly affected cash balances.
Cash Flow
Cash flow is one of the biggest areas to monitor.
| Particulars | FY24 | FY25 |
|---|---|---|
| Operating Cash Flow | -₹5.90 Cr | -₹44.53 Cr |
| Investing Cash Flow | -₹5.22 Cr | -₹14.41 Cr |
| Financing Cash Flow | ₹54.88 Cr | ₹20.18 Cr |
| Net Change in Cash | ₹43.76 Cr | -₹38.75 Cr |
| Closing Cash | ₹43.82 Cr | ₹5.06 Cr |
FY25 operating cash flow was approximately negative ₹44.53 crore, despite the company reporting a profit.
The main working-capital movements included increases in inventory, trade receivables and short-term advances.
This is particularly important because Greenzo’s reported order book is very large compared with its current revenue base.
The company therefore needs to demonstrate that its growing order book can be converted into cash-generating revenue, rather than simply increasing working-capital requirements.
Capital Expenditure
Greenzo increased investment in fixed assets.
Property, plant and equipment increased from approximately ₹3.76 crore in FY24 to ₹10.19 crore in FY25, while capital work-in-progress increased from approximately ₹1.51 crore to ₹10.38 crore.
This is consistent with the company’s investment in manufacturing capacity and infrastructure.
The key question is whether the additional capacity reaches sufficient utilization to generate attractive returns on the capital invested.
Share Capital
As of FY25, the company had approximately 1.185 crore shares outstanding, with paid-up equity share capital of approximately ₹11.85 crore and a face value of ₹10 per share.
Promoter holding has been reported at approximately 83.36% by one unlisted-market source.
The high promoter holding means that public/unlisted-market liquidity is likely to remain relatively limited.
Current Unlisted Share Price
Greenzo Energy does not have an NSE or BSE trading price because it remains unlisted.
Indicative off-market prices vary by intermediary.
Recent September 2026 references include:
- ₹598.10 on Planify as of September 11, 2026
- ₹625 on UnlistedZone as of September 13, 2026
- ₹668.25 on Neoma Capital’s indicative off-market level on September 18, 2026
- Around ₹630 on Stockify’s September 2026 reference
These are indicative private-market quotations rather than exchange-traded prices, so investors should not treat them as a single authoritative market price.
Indicative Valuation
Using approximately 1.185 crore shares:
At ₹600 per share
Implied Equity Value ≈ ₹711 crore
At ₹625 per share
Implied Equity Value ≈ ₹741 crore
At ₹668.25 per share
Implied Equity Value ≈ ₹792 crore
Using FY25 EPS of approximately ₹1.16:
| Indicative Price | Approx. Equity Value | Approx. P/E |
|---|---|---|
| ₹600 | ₹711 Cr | ~517x |
| ₹625 | ₹741 Cr | ~539x |
| ₹668 | ₹792 Cr | ~576x |
This illustrates an important point:
The current unlisted valuation is primarily pricing in future growth rather than current earnings.
The company’s present revenue and profit base is very small relative to the valuation implied by recent unlisted-market prices.
Consequently, the valuation depends heavily on whether the reported order book can be converted into substantial revenue and profit over the next several years.
Key Growth Drivers
1. Green Hydrogen Adoption
India’s push toward green hydrogen creates a potential long-term market for electrolysers, hydrogen systems and EPC services.
Greenzo is positioning itself directly within this emerging ecosystem.
2. Electrolyser Manufacturing
The planned 250 MW manufacturing facility could increase Greenzo’s ability to execute larger projects and reduce dependence on external equipment suppliers.
3. Large Industrial Customers
Orders from companies such as Jindal Stainless and Oswal Energies provide commercial validation of the company’s technology and project capabilities.
4. Heavy-Industry Decarbonisation
Steel, chemicals, refineries and other industrial sectors could become major users of green hydrogen.
The Jindal Stainless project provides an example of how Greenzo’s technology can be integrated into an industrial production process.
5. Export Potential
Greenzo has also established an international presence through its UK subsidiary and has pursued projects outside India.
Its Nepal solar project demonstrates its ability to participate in international renewable-energy projects.
Key Risks
1. Very High Valuation Relative to Current Earnings
At recent indicative prices of ₹600–₹668, the implied P/E based on FY25 EPS is several hundred times.
This makes the valuation highly dependent on future earnings growth.
2. Large Order Book vs Small Revenue Base
The company has reported an order book of around ₹1,800 crore, while FY25 revenue from operations was only about ₹16 crore.
The gap is extremely large.
Execution and order conversion therefore need to be monitored closely.
3. Negative Operating Cash Flow
FY25 operating cash flow was approximately negative ₹44.5 crore.
If order execution requires significant working capital, further growth could initially consume rather than generate cash.
4. Technology Risk
Green hydrogen is still an evolving industry.
Electrolyser efficiency, stack life, electricity costs, system integration and technological improvements can affect project economics.
5. Competition
Greenzo operates in an increasingly competitive electrolyser market that includes established industrial and engineering companies as well as emerging Indian manufacturers.
6. Manufacturing Execution
The planned 250 MW manufacturing facility requires capital, technical execution and sufficient customer demand.
Under-utilisation of the facility could negatively affect returns.
7. Unlisted Liquidity
Because the shares are not exchange listed, investors may face difficulty finding buyers or sellers.
Off-market prices can also differ substantially between intermediaries.
8. Working Capital
The sharp increase in inventories, receivables and advances in FY25 contributed to the company’s negative operating cash flow.
Successful growth will require stronger cash conversion.
IPO / Listing
Greenzo Energy remains an unlisted public company.
The company’s website contains an investor-relations section, while secondary sources continue to classify its shares as unlisted.
An investor should therefore not assume that a future IPO or listing will occur at a particular valuation.
Any IPO thesis should be reassessed only after a formal regulatory filing, proposed issue size, valuation and timetable become available.
Investment Perspective
Greenzo Energy represents a relatively early-stage play on India’s green-hydrogen ecosystem.
Unlike a mature renewable-energy company, the current financial statements show a relatively small revenue and profit base. The company’s reported order book is several times larger than current annual revenue, creating the possibility of substantial future scale if projects are executed successfully.
The company has also moved beyond simply consulting on renewable projects and is developing indigenous electrolyser manufacturing capabilities, which could provide higher strategic value if the business reaches meaningful manufacturing scale.
However, the valuation already reflects substantial expectations.
At recent unlisted-market levels around ₹600–₹668, the implied equity value is approximately ₹710–₹790 crore, while FY25 revenue was only around ₹16 crore and FY25 EPS was around ₹1.16.
The central investment question is therefore not simply whether the green-hydrogen industry will grow.
It is whether Greenzo can convert its order book into large-scale revenue, maintain acceptable margins, generate operating cash flow and achieve sufficient manufacturing utilisation to justify the current private-market valuation.
What Investors Should Monitor
The following indicators are particularly important:
- Conversion of the ₹1,800 crore reported order book into revenue
- Execution of the Oswal Energies project
- Progress of the Jindal Stainless green-hydrogen project
- Utilisation of the 250 MW electrolyser manufacturing facility
- New electrolyser orders
- Revenue growth
- EBITDA margin
- Operating cash flow
- Inventory and receivable days
- Additional equity issuance or dilution
- Any formal IPO/listing filing
- Development of India’s green-hydrogen market
Corporate Details
Company: Greenzo Energy India Limited
CIN: U29309DL2022PLC407203
ISIN: INE0OA401013
Face Value: ₹10
Paid-up Capital: ~₹11.85 Cr
Shares Outstanding: ~1.185 Cr
Status: Unlisted Public Company
Registered Office: Unit No. 1104, 11th Floor, Surya Kiran Building, K.G. Marg, New Delhi – 110001
Manufacturing Facility: Sanand Industrial Area, Ahmedabad, Gujarat
Managing Director: Sandeep Agarwal
Important Links
Official Website: Greenzo Energy India
Investor Relations: Greenzo Energy Investor Relations
Projects: Greenzo Energy Projects
Jindal Stainless Green Hydrogen Project: Jindal Stainless – Greenzo Energy Project Update
Conclusion
Greenzo Energy India is an emerging clean-energy company focused on green-hydrogen technology, alkaline electrolysers, balance-of-plant systems and renewable-energy EPC.
The company’s biggest potential catalyst is the transition from a relatively small current revenue base toward commercial-scale execution of its reported order book.
The company has already announced projects involving Oswal Energies, Jindal Stainless, TANGEDCO and Nepal-based solar infrastructure, while simultaneously developing its own electrolyser manufacturing capacity.
At the same time, investors need to account for the substantial gap between the company’s current financial performance and its reported order book, negative operating cash flow and the high valuation implied by recent unlisted-market prices.
The key test for Greenzo over the coming years will be execution and cash conversion.
If the company successfully scales electrolyser manufacturing and converts its project pipeline into sustainable revenue and profits, its financial profile could change materially. Until that happens, the current valuation should be assessed primarily against future earnings potential rather than historical earnings.
Disclaimer
This report is prepared for educational and informational purposes only and should not be considered investment advice, a recommendation to buy or sell securities, or a solicitation to invest.
Greenzo Energy India Limited is an unlisted company. Its shares are traded through private/off-market transactions and do not have an NSE or BSE exchange price.
Unlisted-market prices quoted by different intermediaries may vary substantially and should be treated as indicative.
Financial information has been compiled from publicly available company information, annual financial data and published secondary sources. Investors should independently verify the latest audited financial statements, share capital, order book, project execution status, valuation and corporate actions before making any investment decision.
The author is not a SEBI-registered Research Analyst unless specifically stated otherwise.
For more such unlisted stocks visit Unlisted Shares – UnlistedCart
