
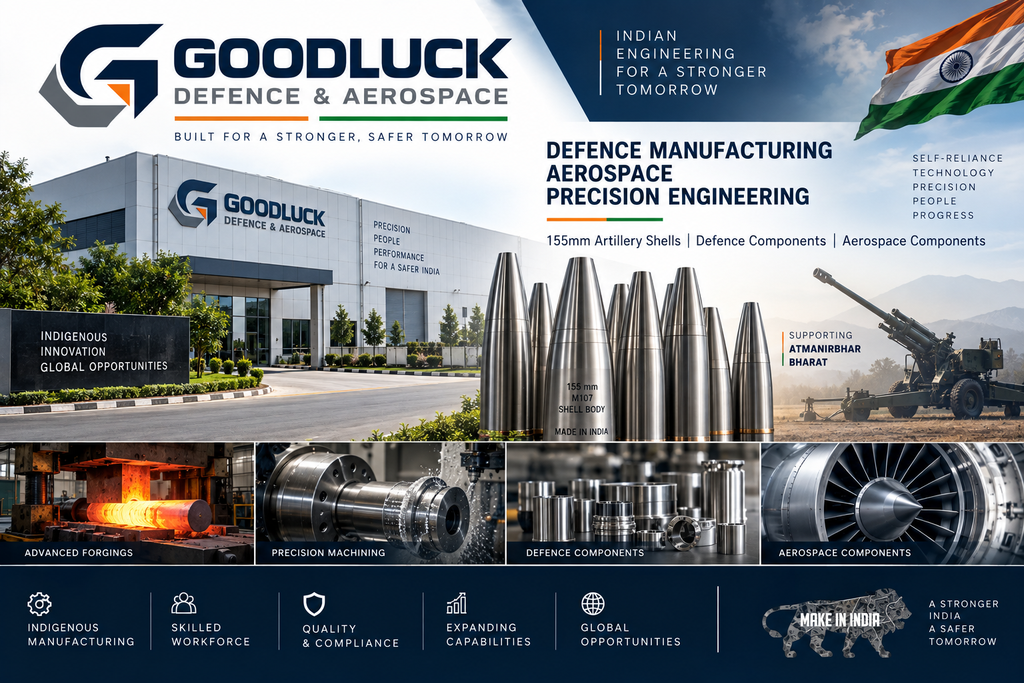
Defence Manufacturing • Artillery Ammunition • Aerospace Components
1. Company Overview
Goodluck Defence & Aerospace Limited (GDAL) is a public, unlisted defence-manufacturing company incorporated on 31 August 2023 and headquartered in Ghaziabad, Uttar Pradesh.
The company is a subsidiary of Goodluck India Limited, an established engineering and steel-products manufacturer. As of 31 March 2026, Goodluck India held 79.43% of Goodluck Defence & Aerospace.
The company is focused primarily on manufacturing empty artillery shell bodies, which are supplied to authorised defence establishments for subsequent filling, assembly and integration. Its manufacturing facility is located at Sikandrabad, Uttar Pradesh.
Legal Name: Goodluck Defence and Aerospace Limited
CIN: U24103UP2023PLC188289
Incorporated: 31 August 2023
Registered Office: Ghaziabad, Uttar Pradesh
Sector: Defence & Aerospace
Industry: Defence Manufacturing / Ammunition Components / Precision Engineering
Status: Public Unlisted Company
ISIN: INE0S7401019
Face Value: ₹10 per share
Promoter / Parent: Goodluck India Limited
Parent Holding: 79.43%
The company describes its strategy as building an integrated metal-to-product manufacturing capability for defence and aerospace applications, with a focus on domestic indigenisation and international defence supply chains.
2. Business Model
Goodluck Defence & Aerospace is developing a specialised manufacturing platform around high-strength metals, forging, machining, heat treatment and quality inspection.
Its current business includes:
- 155mm artillery shell bodies
- Other medium-calibre artillery shell bodies
- Defence forgings
- Armament components
- Precision-machined defence assemblies
- Aerospace structural components
- High-strength alloy components
The company’s FY2026 annual report specifically states that its principal business is the manufacture and sale of empty artillery shell bodies for supply to authorised defence establishments.
3. Artillery Shell Manufacturing
The biggest current opportunity is the company’s artillery ammunition business.
Goodluck Defence received an industrial licence for manufacturing medium-calibre artillery shells covering calibres including:
- 105mm
- 120mm
- 125mm
- 130mm
- 155mm
The company’s portfolio includes variants such as:
- HE M107
- ERFB
- ERFB-BB
- ERFB-BT
The licence and manufacturing capabilities position the company within India’s growing domestic ammunition-manufacturing ecosystem.
4. Manufacturing Facility
Goodluck Defence inaugurated its dedicated defence manufacturing facility in October 2025 and commenced commercial production on 8 October 2025.
The initial installed capacity was:
1,50,000 artillery shells per year
The company has subsequently announced a major expansion:
1,50,000 → 4,00,000 shells per year
The expansion involves approximately ₹500 crore of investment through a combination of equity and debt, with completion currently expected by September 2027.
This means the planned capacity would be approximately 2.67 times the initial capacity.
5. Quality & Defence Certifications
In July 2026, Goodluck Defence received a Quality Assurance Certificate from the Directorate General of Quality Assurance (DGQA), Ministry of Defence, for the supply of 155mm M107 Ready-to-Fill Artillery Shells.
This is an important operational milestone because DGQA certification enables the company to participate in applicable defence procurement opportunities for the certified product.
6. Export Opportunity
The company’s official website states that Goodluck Defence has:
- Executed international export orders for 155mm shells
- Entered the global defence supply chain
- Delivered its first overseas shipment against a US$6 million order
The company also identifies export expansion and partnerships with global defence OEMs as part of its future roadmap.
7. Defence & Aerospace Expansion
The company’s opportunity extends beyond ammunition.
Goodluck’s wider engineering ecosystem already has experience in:
- Forgings
- Aerospace components
- Defence components
- Precision machining
- Heavy engineering
- Structural fabrication
The parent company’s investor presentation identifies defence and aerospace as a growth area and lists customers/programmes across the defence and aerospace value chain, including programmes associated with Pralay, BrahMos, Pinaka and K9 Vajra.
The company is therefore attempting to move from conventional steel engineering into higher-value, mission-critical defence manufacturing.
8. Financial Performance
FY2026 Standalone Financials
| Particular | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Total Income | ₹3.04 Cr | ₹6.99 Cr | ₹45.41 Cr |
| Revenue from Operations | Nil | Nil | ₹41.41 Cr |
| Other Income | ₹3.04 Cr | ₹6.99 Cr | ₹3.91 Cr |
| Profit Before Tax | ₹2.61 Cr | ₹5.25 Cr | ₹12.61 Cr |
| PAT | ₹1.84 Cr | ₹3.88 Cr | ₹9.05 Cr |
| EPS | ~₹0.38 | ~₹0.79 | ₹1.84 |
FY2026 was the first year in which the company generated substantial operating revenue, with ₹41.41 crore of revenue from operations.
Total income reached ₹45.41 crore, while PAT increased to approximately ₹9.05 crore.
This is important because the earlier financial years were largely pre-commercialisation years, when the company was still building its defence manufacturing infrastructure.
9. FY2026 Balance Sheet
As of 31 March 2026:
- Total assets: ₹503.62 Cr
- Total equity: ₹183.07 Cr
- Total liabilities: ₹320.55 Cr
- Non-current liabilities: ₹68.36 Cr
- Current liabilities: ₹252.19 Cr
- Non-current assets: ₹342.95 Cr
- Current assets: ₹160.67 Cr
The substantial increase in assets reflects the heavy capital investment required to establish the defence manufacturing facility.
10. Cash Flow
Cash flow remains an important area to monitor.
FY2026
- Operating cash flow: -₹17.44 Cr
- Investing cash flow: -₹112.05 Cr
- Financing cash flow: +₹128.62 Cr
- Closing cash: approximately ₹0.09 Cr
The negative investing cash flow reflects substantial capital expenditure, while financing inflows supported the expansion programme.
The company spent approximately ₹115.96 crore on property, plant and equipment during FY2026.
This highlights an important characteristic of the business: it is currently in a capital-intensive expansion phase.
11. Shareholding
As of 31 March 2026:
| Shareholder Category | Holding |
|---|---|
| Goodluck India Limited | 79.43% |
| Others / Non-Promoter | 20.57% |
| Total | 100% |
The company had 4.911 crore equity shares outstanding, each having a face value of ₹10.
Goodluck India’s investment in the subsidiary stood at approximately ₹390.10 crore at 31 March 2026.
12. Major Capital Raise in 2026
One of the most important recent developments came in August 2026.
Goodluck Defence approved a proposed preferential/private placement to non-promoter investors to raise up to approximately:
₹285 Crore
The proposed issue price was:
₹375 per share
The transaction remained subject to shareholder and other statutory/regulatory approvals.
If the full ₹285 crore were raised at ₹375 per share, it would represent approximately 76 lakh new shares.
Based purely on this proposed issue price and assuming the full issue is completed, the implied post-issue equity value would be approximately ₹2,127 crore. This is an arithmetic implication of the proposed issue terms, not a separately disclosed company valuation.
The proposed fundraise is particularly relevant because it could provide capital for the company’s planned capacity expansion.
13. Defence Order Opportunity
In May 2026, Goodluck India disclosed that its defence subsidiary had secured a domestic order worth approximately:
₹52.20 Crore
The order covered the manufacture and supply of 20,000 units of 155mm shells, with execution scheduled over approximately three months, subject to the required approvals. The customer was not publicly identified because of confidentiality provisions.
For context, the order value was larger than the company’s FY2026 revenue from operations, although order value should not be directly compared with revenue recognition because the accounting timing and execution period can differ.
14. Growth Drivers
1. Expansion from 1.5 lakh to 4 lakh shells
The planned capacity increase could materially expand the company’s potential production base.
2. Indian defence indigenisation
India’s focus on domestic defence manufacturing provides a structural opportunity for local ammunition and component manufacturers.
3. DGQA certification
The 155mm M107 certification is an important qualification for participation in relevant procurement opportunities.
4. Export potential
The company has already reported an international shipment and identifies exports as a future growth area.
5. Aerospace components
The group’s forging and precision-engineering capabilities could support expansion into higher-value aerospace applications.
6. Parent-company engineering ecosystem
Goodluck India brings decades of experience in steel, forgings, precision tubes and engineered structures. The parent company reports more than 40 years of operating experience and a diversified engineering customer base.
15. Key Strengths
1. Defence-focused subsidiary
The company has been established specifically to build a dedicated defence and aerospace manufacturing platform.
2. Large addressable ammunition opportunity
The company is operating in a strategic segment where domestic manufacturing capacity is being expanded.
3. Commercial production has begun
This is no longer purely a pre-revenue defence project; the company generated ₹41.4 crore of operating revenue in FY2026.
4. Capacity expansion
Planned capacity of 4 lakh shells annually represents a significant increase from the initial 1.5 lakh capacity.
5. Institutional backing
Goodluck India owns 79.43% of the company.
6. Recent defence orders
The ₹52.2 crore 155mm shell order provides evidence of commercial demand, although future order flows cannot be assumed.
16. Key Risks
1. Very young company
Goodluck Defence was incorporated only in August 2023, meaning its historical operating record is limited.
2. High capital intensity
The company is spending heavily on manufacturing capacity.
FY2026 capital expenditure on property, plant and equipment was approximately ₹116 crore.
3. Negative operating cash flow
Operating cash flow remained negative at approximately ₹17.4 crore in FY2026.
4. Debt and financing requirements
The planned ₹500 crore expansion is expected to be funded through a combination of equity and debt, increasing the importance of balance-sheet management.
5. Customer concentration
Defence contracts can be concentrated among government entities, defence establishments and large OEMs.
6. Regulatory dependency
Ammunition manufacturing and sales are subject to stringent licensing, quality, security and regulatory requirements.
7. Execution risk
The company’s future growth depends heavily on successfully scaling production from 1.5 lakh to 4 lakh shells per year.
8. Unlisted-market liquidity
Shares are not traded on NSE/BSE, so investors may face limited liquidity and less transparent price discovery.
17. IPO / Listing Status
As of 23 September 2026, Goodluck Defence & Aerospace remains unlisted.
There is currently no confirmed IPO filing or announced IPO date identified in the company’s official disclosures reviewed for this report.
Some third-party unlisted-share platforms speculate about a potential 2026 listing, but such estimates should not be treated as confirmed company guidance.
Therefore, investors should not build an investment thesis solely around an assumed IPO.
18. Unlisted Investment Perspective
Goodluck Defence & Aerospace is essentially a defence manufacturing capacity-expansion story.
The investment case is closely linked to the transition from:
₹41 Cr FY26 operating revenue → higher artillery-shell production → larger defence orders → 4 lakh annual capacity → potential aerospace/defence component expansion
The most important variables to monitor are:
- Utilisation of the existing 1.5 lakh shell capacity
- Execution of the ₹52.2 crore order
- New domestic defence orders
- Export orders
- DGQA/customer approvals
- Progress toward 4 lakh shell capacity
- ₹500 crore capex execution
- Funding mix between debt and equity
- Operating cash flow
- EBITDA margins as production scales
- Aerospace component diversification
- Future capital raises
- Any IPO filing
Proposed ₹375 issue price
The August 2026 proposed preferential/private placement at ₹375 per share provides an important valuation reference point because it represents a proposed institutional/non-promoter financing price.
However, investors should distinguish between:
₹375 proposed issue price ≠ guaranteed fair value ≠ future IPO price
Secondary-market unlisted prices can trade at premiums or discounts to financing prices depending on demand, liquidity and expectations.
19. Company Snapshot
| Particular | Details |
|---|---|
| Company | Goodluck Defence & Aerospace Limited |
| CIN | U24103UP2023PLC188289 |
| Incorporated | 31 August 2023 |
| Headquarters | Ghaziabad, Uttar Pradesh |
| Sector | Defence & Aerospace |
| Core Business | Artillery Shells & Defence Components |
| Parent | Goodluck India Limited |
| Parent Holding | 79.43% |
| FY26 Operating Revenue | ₹41.41 Cr |
| FY26 Total Income | ₹45.41 Cr |
| FY26 PAT | ₹9.05 Cr |
| FY26 EPS | ₹1.84 |
| FY26 Total Assets | ₹503.62 Cr |
| FY26 Operating Cash Flow | -₹17.44 Cr |
| Initial Shell Capacity | 1.50 Lakh/Year |
| Planned Capacity | 4.00 Lakh/Year |
| Expansion Investment | ~₹500 Cr |
| FY26 Shares Outstanding | 4.911 Cr |
| Proposed 2026 Fundraise | Up to ₹285 Cr |
| Proposed Issue Price | ₹375/share |
| Current Status | Unlisted |
| ISIN | INE0S7401019 |
20. Important Links
Official Goodluck India Website:
Goodluck India Limited
Goodluck Defence & Aerospace Official Website:
Goodluck Defence & Aerospace
Official Company Overview:
Goodluck Defence – Company Overview
Goodluck India – Subsidiary Information:
Goodluck Defence Annual Reports & AGM Documents
FY2025-26 Annual Report:
Goodluck Defence & Aerospace Annual Report 2025-26
FY2024-25 Annual Report:
Goodluck Defence & Aerospace Annual Report 2024-25
Goodluck Defence Investor Presentation:
Goodluck India Investor Presentation – Defence Expansion
FY2026 Financial Information:
Goodluck Defence Financials
Disclaimer
This report is prepared strictly for informational and educational purposes and should not be considered an offer, solicitation or recommendation to buy or sell securities.
Goodluck Defence & Aerospace Limited is an unlisted company, and investment in unlisted shares involves significant liquidity, valuation, transfer, regulatory, execution and market risks. Financial figures have been taken primarily from the company’s FY2025-26 annual report and other publicly available disclosures. Investors should independently verify the latest financial statements, shareholding, transaction terms, valuation, regulatory approvals and corporate announcements before making any investment decision.
The proposed ₹285 crore fundraise at ₹375 per share is subject to applicable approvals and should not be interpreted as a guaranteed valuation or future IPO price. Similarly, any potential IPO/listing timeline should be treated as uncertain until formally announced through the company’s regulatory filings.
Past performance and announced orders do not guarantee future financial performance.
For more such unlisted stocks visit
UnlistedCart – Unlisted Shares
