
Sector: E-Commerce / Internet / Digital Commerce
Status: Unlisted – Potential IPO Candidate
Founded: 2007
Headquarters: Bengaluru, Karnataka
Promoter / Controlling Shareholder: Walmart Inc.
Group CEO: Kalyan Krishnamurthy
Business: E-commerce, marketplace, fashion, grocery, quick commerce, logistics, digital services
Important Entity Note
Flipkart’s corporate structure has undergone a major change.
In March 2026, Flipkart completed its reverse-flip/redomiciliation from Singapore to India, with Flipkart Internet Private Limited becoming the holding entity of the Flipkart Group. This was an important structural step toward a potential Indian public listing.
However, the unlisted market contains securities marketed under names such as Flipkart India Private Limited and Flipkart Internet Private Limited, with different ISINs.
Therefore, investors must verify the exact legal company name, ISIN, share class and transfer documents before purchasing.
About the Company
Flipkart is one of India’s largest e-commerce platforms and a dominant player in online retail.
Founded in 2007 by Sachin Bansal and Binny Bansal, Flipkart initially focused on online books before expanding into electronics, smartphones, fashion, appliances, grocery and other consumer categories.
Walmart acquired a controlling stake in Flipkart in 2018 for approximately $16 billion, making Flipkart one of the world’s largest strategic bets on India’s digital-consumer economy.
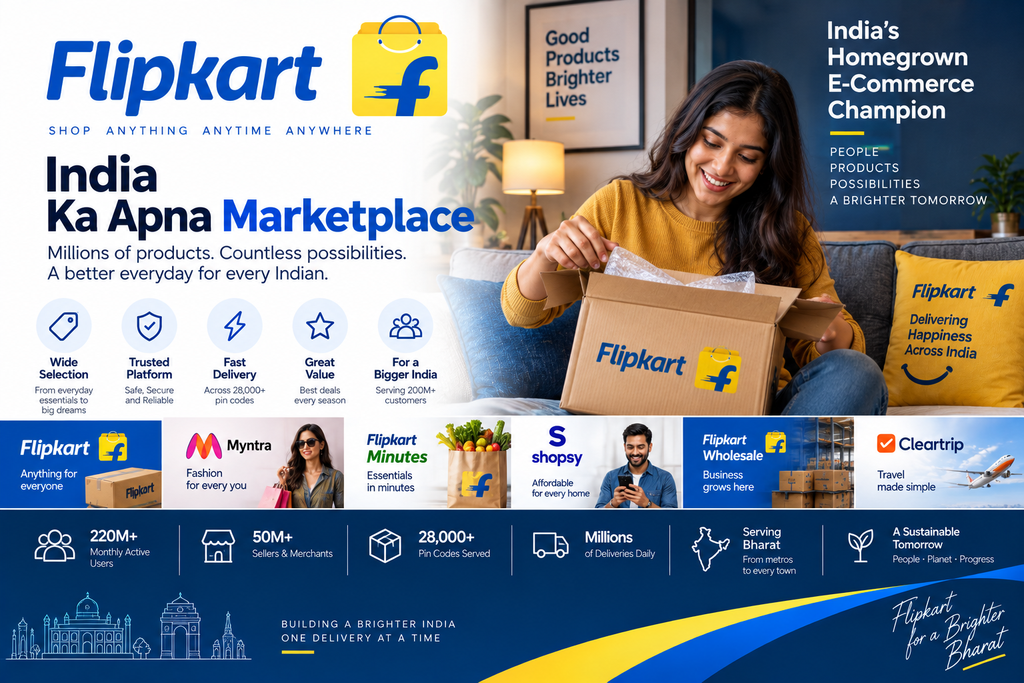
Today, the Flipkart ecosystem includes:
- Flipkart Marketplace
- Myntra
- Flipkart Minutes
- Flipkart Grocery
- Shopsy
- Flipkart Wholesale
- Cleartrip
- SuperCoins / loyalty ecosystem
- Payments and financial-services initiatives
- Logistics and supply-chain infrastructure
Key Highlights
- One of India’s largest e-commerce platforms.
- Estimated 50–60% share of India’s e-commerce GMV according to an ICICI Securities report.
- Approximately 220–240 million monthly active users according to the same report.
- Strong leadership in smartphones, electronics and appliances.
- Particularly strong penetration in Tier-II and smaller Indian cities.
- Flipkart Group generated approximately $30 billion GMV in calendar 2025, roughly double its 2020 level.
- Walmart remains the controlling shareholder.
- Google invested approximately $350 million in Flipkart as part of a nearly $1 billion funding round in 2024.
- The company completed its India redomiciliation in 2026.
- Flipkart Minutes is rapidly expanding its quick-commerce footprint.
- The Group continues to build a broader consumer ecosystem around shopping, grocery, loyalty and financial services.
Business Model
Flipkart operates a marketplace-led model connecting consumers with third-party sellers while also generating revenue through advertising, logistics, fulfilment and associated services.
| Business | Description |
|---|---|
| Marketplace | Electronics, mobiles, appliances, lifestyle and general merchandise |
| Fashion | Myntra and fashion ecosystem |
| Quick Commerce | Flipkart Minutes |
| Grocery | Online grocery and everyday essentials |
| Advertising | Sponsored listings and seller/brand advertising |
| Logistics | Supply-chain and delivery infrastructure |
| Wholesale | B2B commerce |
| Loyalty | SuperCoins and Flipkart Plus |
| Travel | Cleartrip |
| FinTech | Payments, credit and financial-service initiatives |
The strategic advantage is the ability to monetise the same customer across multiple categories.
Market Position
Flipkart remains one of the two dominant players in Indian e-commerce alongside Amazon, while Meesho has become an important challenger.
An ICICI Securities report estimated Flipkart’s GMV share at approximately 50–60% and monthly active users at around 220–240 million. Electronics and smartphones reportedly account for roughly 63–64% of Flipkart’s sales, giving the company strong positioning in high-value categories.
Euromonitor estimates that Flipkart Internet and Amazon together accounted for 56% of India’s retail e-commerce value share in 2025, demonstrating the concentration of the Indian market around the largest platforms.
Financial Snapshot
Flipkart Internet – Marketplace Entity
₹ Crore
| Particulars | FY24 | FY25 |
|---|---|---|
| Operating Revenue | ~17,900 | 20,493 |
| Revenue Growth | — | ~14% |
| Net Loss | ~2,359 | 1,494 |
| Loss Reduction | — | ~37% |
Flipkart Internet’s FY25 revenue increased approximately 14% to ₹20,493 crore, while its net loss narrowed by approximately 37% to ₹1,494 crore.
This is an encouraging development because the company is moving toward better operating leverage, but it remains loss-making.
Group GMV
The broader Flipkart Group reportedly generated approximately $30 billion in GMV in calendar 2025, compared with approximately $15 billion in 2020.
GMV should not be confused with revenue.
GMV = value of goods sold through the platform
while
Revenue = income actually recognised by Flipkart and its subsidiaries.
This distinction is important when valuing e-commerce companies.
Quick Commerce – Flipkart Minutes
One of Flipkart’s biggest strategic initiatives is Flipkart Minutes, its quick-commerce platform competing with Blinkit, Zepto and Swiggy Instamart.
By September 2026, industry reports indicated that Minutes had expanded to more than 1,000 dark stores across approximately 120–130 cities, with further expansion planned.
This provides Flipkart with a significant growth opportunity because quick commerce can increase:
Order frequency → Customer engagement → Grocery penetration → Advertising → Loyalty
However, it also requires substantial investment and can delay profitability.
Valuation
Flipkart was valued at approximately $35–36 billion in its 2024 funding round involving Walmart and Google.
In July 2026, its latest employee-stock buyback exercise implied a valuation of approximately $38.2 billion, around 6% above the 2024 funding valuation. Importantly, this is an implied private-market valuation rather than a formal new funding-round valuation.
Indicative Valuation
2024 funding valuation: ~$35–36 billion
2026 implied ESOP valuation: ~$38.2 billion
At ₹83/USD, a $38.2 billion valuation is approximately:
₹3.17 lakh crore
This should be treated as an indicative private valuation, not an exchange-traded market capitalisation.
Current Unlisted Price
The unlisted market is currently showing very different prices depending on the exact Flipkart entity/share class.
For example, one current reference for Flipkart India Private Limited, ISIN INE075T01014, shows approximately ₹52,288/share as of September 9, 2026, with a minimum lot of four shares.
Another unlisted-market source quotes Flipkart Internet securities at materially different prices.
Important
Do not compare these prices directly without checking the ISIN and share class.
For UnlistedCart, the displayed price should therefore always include:
Legal Entity + ISIN + Face Value + Share Class + Indicative OTC Price
This will prevent investors from confusing different Flipkart securities.
IPO Status
Flipkart’s IPO story has been developing for several years.
The March 2026 reverse-flip was widely viewed as a major structural step toward a potential Indian IPO. Earlier reports suggested a possible FY27 listing.
However, Flipkart CEO Kalyan Krishnamurthy stated in July 2026 that the company did not have a specific IPO timeline.
In May 2026, reports also indicated that Walmart wanted Flipkart to focus on achieving EBITDA breakeven before pursuing an IPO or external fundraising.
Current IPO Position
| Parameter | Status |
|---|---|
| Reverse Flip | Completed |
| India Holding Company | Flipkart Internet Pvt Ltd |
| IPO Preparation | Ongoing strategically |
| SEBI IPO Approval | Not confirmed |
| DRHP | Not publicly filed |
| IPO Date | No confirmed timeline |
| Target | Potential Indian listing |
| Immediate Focus | Profitability + growth |
Therefore, UnlistedCart should not market Flipkart as “IPO confirmed”.
The correct positioning is:
“Unlisted E-Commerce Leader | Potential Future IPO.”
Investment Positives
| Positive | Why It Matters |
|---|---|
| Market Leadership | 50–60% estimated GMV share |
| Massive User Base | 220–240 Mn monthly active users |
| Strong Brand | One of India’s most recognised e-commerce platforms |
| Walmart Backing | Global strategic parent |
| Google Investment | Strong technology/institutional validation |
| Tier-II Reach | Deep penetration beyond major metros |
| Electronics Leadership | High-value categories strengthen economics |
| Myntra | Strong fashion ecosystem |
| Minutes | Potential quick-commerce growth engine |
| Advertising | Higher-margin monetisation opportunity |
| Logistics | Large fulfilment infrastructure |
| India Growth | Long-term e-commerce penetration remains attractive |
| Reverse Flip | Removes an important structural barrier to Indian listing |
Key Risks & Concerns
| Risk | Concern |
|---|---|
| Still Loss-Making | Marketplace arm reported ₹1,494 Cr FY25 loss |
| IPO Uncertainty | No confirmed listing timeline |
| Quick-Commerce Burn | Minutes requires substantial investment |
| Amazon Competition | Amazon remains a powerful competitor |
| Meesho Competition | Value-commerce segment is rapidly growing |
| Blinkit / Zepto | Quick-commerce competition is intense |
| High Valuation | ~$38.2 Bn implied valuation leaves limited margin for error |
| Regulatory Risk | E-commerce, consumer protection and competition rules |
| Execution Risk | Managing marketplace + quick commerce + grocery simultaneously |
| Margin Pressure | Discounting and delivery costs can pressure profitability |
| Unlisted Liquidity | OTC prices can differ substantially between dealers |
| Entity Risk | Different Flipkart entities and ISINs can create confusion |
Recent Regulatory / Consumer Risk
Flipkart is also facing continuing regulatory scrutiny around marketplace compliance and product standards.
In September 2026, the Karnataka High Court asked Flipkart to explain how it prevents non-BIS-compliant products from being sold on its platform following a consumer-regulator penalty relating to toys.
The monetary amount involved is small relative to Flipkart’s scale, but the episode highlights an important structural risk for large marketplaces:
Seller compliance + product authenticity + consumer protection + regulatory oversight.
Investment Rationale
The Flipkart investment thesis is fundamentally an India consumption story.
India is moving from:
Offline Retail → Online Retail → Omnichannel → Quick Commerce → Digital Consumer Ecosystem
Flipkart has an opportunity to participate in almost every stage.
Its biggest competitive advantages are:
1. Scale
Hundreds of millions of consumers create substantial network effects.
2. Brand & Trust
Flipkart has spent nearly two decades building consumer recognition in India.
3. Tier-II/Tier-III Reach
Its strength outside India’s largest metros differentiates it from some competitors.
4. Infrastructure
Large logistics and fulfilment capabilities create barriers to entry.
5. Ecosystem
Myntra, Minutes, Grocery, Cleartrip, SuperCoins and other businesses can increase customer lifetime value.
6. Walmart
Walmart provides access to capital, global retail expertise and strategic relationships.
The Big Question: Profitability
The most important issue for an investor is no longer:
“Can Flipkart grow?”
It has already demonstrated scale.
The more important question is:
“Can Flipkart convert its enormous GMV and customer base into sustainable free cash flow?”
FY25 showed progress because Flipkart Internet reduced its loss by approximately 37%.
But aggressive investment in Minutes and other businesses could delay consolidated profitability.
This is why Walmart’s reported focus on EBITDA breakeven before an IPO is significant.
Investment View
Business Quality: ⭐⭐⭐⭐⭐
One of India’s strongest internet businesses with enormous scale and strategic importance.
Market Position: ⭐⭐⭐⭐⭐
Estimated 50–60% e-commerce GMV share makes Flipkart a dominant player.
Growth Potential: ⭐⭐⭐⭐⭐
India’s e-commerce penetration, quick commerce, digital advertising and financial services offer multiple growth avenues.
Profitability: ⭐⭐⭐
Losses have narrowed, but sustainable consolidated profitability is still the key challenge.
IPO Visibility: ⭐⭐⭐½
The reverse flip materially improves IPO readiness, but management currently has no confirmed listing timeline.
Valuation: ⭐⭐⭐
The ~$38.2 billion implied private valuation is substantial, so the entry price matters enormously.
Overall View
Flipkart is one of the strongest unlisted consumer-internet opportunities in India, but it should not be bought blindly because of the “IPO story.”
The real investment thesis is:
India’s consumption growth + e-commerce leadership + enormous customer base + Walmart backing + quick-commerce optionality + eventual IPO catalyst.
The biggest concern is valuation.
At an implied valuation of approximately $38.2 billion, investors are already paying for significant future growth. The opportunity becomes considerably more attractive if the unlisted entry price provides a meaningful discount to the eventual public-market valuation.
UnlistedCart View
“India’s E-Commerce Leader | Walmart-Backed Consumer Internet Giant | Strong Scale, Strong Optionality — But Profitability & Entry Valuation Matter.”
Investor Profile: Long-term investors comfortable with unlisted liquidity, high-growth businesses and IPO uncertainty.
Share Details
| Particular | Details |
|---|---|
| Group | Flipkart Group |
| Current Indian Holding Entity | Flipkart Internet Private Limited |
| CIN | U51109KA2012PTC066107 |
| Status | Private / Unlisted |
| Sector | E-Commerce |
| Promoter | Walmart Inc. |
| Headquarters | Bengaluru |
| FY25 Marketplace Revenue | ~₹20,493 Cr |
| FY25 Marketplace Loss | ~₹1,494 Cr |
| Estimated Group GMV CY25 | ~$30 Bn |
| 2026 Implied Private Valuation | ~$38.2 Bn |
| IPO | Potential / No confirmed timeline |
Important ISIN Note
For securities marketed as Flipkart India Private Limited, one current unlisted-market reference identifies:
ISIN: INE075T01014
Face Value: ₹1
Indicative price: ~₹52,288/share as of 9 September 2026.
Flipkart Internet has also historically had separate share classes/ISINs; its FY24 statutory filing, for example, listed Class A ISIN INE074T01025 and Class B ISIN INE074T01033.
Therefore, verify the exact security before publishing a buy/sell price on UnlistedCart.
Disclaimer
This report is for educational and informational purposes only and does not constitute investment advice, an offer, solicitation or recommendation to buy or sell securities.
Unlisted-share prices are OTC/private-market indications and may vary materially depending on the legal entity, ISIN, share class, seller, lot size, liquidity, transfer restrictions and transaction terms.
Investors should independently verify the exact company, ISIN, share class, ownership documents, financial statements, taxation, transfer restrictions and latest regulatory/IPO status before investing.
IPO timing, valuation and structure are uncertain and may change materially before any public listing.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
