
1. Company Overview
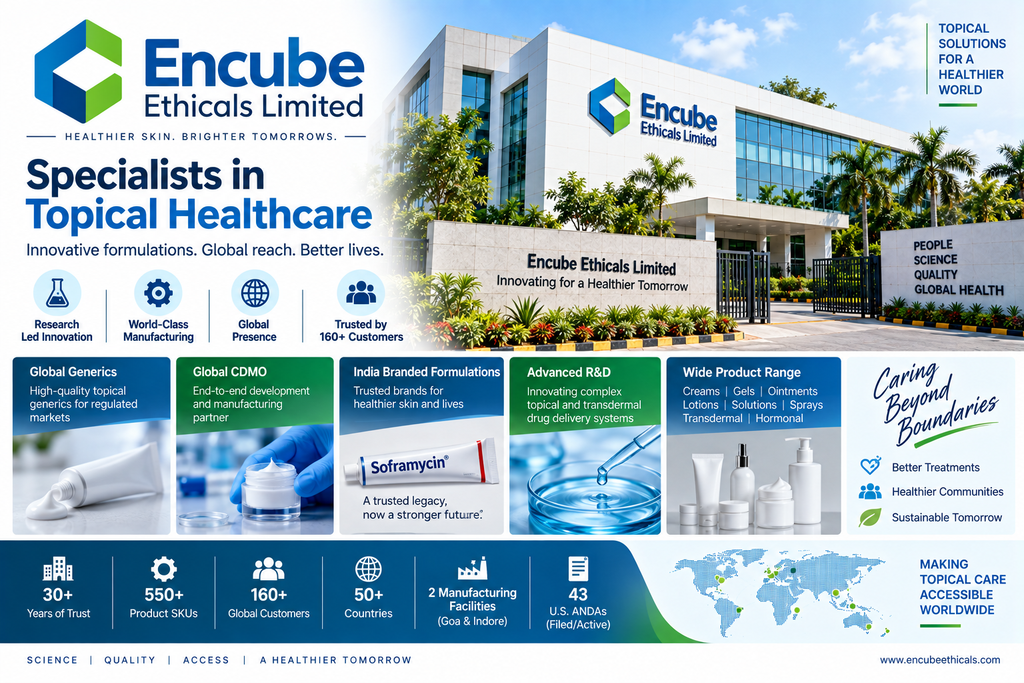
Encube Ethicals Limited is an Indian pharmaceutical company specializing in topical and transdermal formulations, including creams, gels, ointments, lotions, solutions and other complex drug-delivery formats.
Founded in 1995, Encube has developed from a topical-manufacturing company into a global pharmaceutical platform serving customers across regulated and emerging markets. As of March 31, 2026, the company served customers in 50 countries and operated across three principal verticals: Global Generics, Global CDMO and India Branded Formulations.
| Particular | Details |
|---|---|
| Company | Encube Ethicals Limited |
| Incorporated | 7 September 1995 |
| CIN | U24230MH1995PLC092485 |
| Status | Unlisted Public Company / IPO-bound |
| Registered Office | Mumbai, Maharashtra |
| Industry | Pharmaceuticals |
| Core Expertise | Topical & transdermal formulations |
| Paid-up Capital | ~₹30.4 Cr |
| Manufacturing | Goa & Indore |
| Global Reach | 50+ countries |
| Customers | 160+ pharmaceutical companies |
| FY26 Revenue from Operations | ₹1,848.7 Cr |
| FY26 PAT | ₹436.7 Cr |
The company is currently classified as an active unlisted public company. Tofler reports authorized capital of ₹45 crore and paid-up capital of approximately ₹30.39 crore.
Official website: Encube Ethicals
Official U.S. business: Encube Ethicals USA
2. What Does Encube Ethicals Do?
Encube focuses on topical and transdermal pharmaceutical products, an area requiring specialized formulation, manufacturing and regulatory capabilities.
Its product capabilities include:
- Creams
- Gels
- Lotions
- Ointments
- Solutions
- Sprays
- Hormonal formulations
- High-potency products
- Complex topical formulations
- Transdermal drug-delivery systems
The company also works on complex formulations such as biphasic microsphere gels, with R&D focused on moving from conventional topical products toward more sophisticated drug-delivery systems.
3. Three Main Business Verticals
A. Global Generics
Global Generics was the largest business vertical in FY26, contributing approximately 47% of revenue.
The company develops and manufactures topical generic medicines for international markets, particularly the United States.
Encube’s U.S. topical-generics portfolio includes products in creams, gels, ointments, lotions and other semisolid formats.
As of March 31, 2026, Encube had 43 filed or active ANDAs in the U.S. and 25 dossiers in the UK and Germany.
B. Global CDMO
The Contract Development & Manufacturing Organization (CDMO) business contributed approximately 42% of FY26 revenue.
Encube provides pharmaceutical companies with end-to-end services covering:
Product development → formulation → technology transfer → manufacturing → packaging → regulatory support
As of March 31, 2026, the company served 160+ pharmaceutical companies across 50 countries and had more than 550 SKUs, primarily focused on regulated markets.
C. India Branded Formulations
India Branded Formulations contributed approximately 9% of FY26 revenue.
This business gained significant visibility after Encube acquired the India and Sri Lanka rights for Soframycin and associated brands from Sanofi.
Sanofi disclosed that the transaction included the Soframycin and Sofradex brands, associated IP and related assets. The transaction was completed in January 2022.
The acquisition enabled Encube to move beyond manufacturing and establish a stronger direct presence in India’s branded/consumer healthcare market.
4. Soframycin – Strategic Brand
Soframycin is one of Encube’s most recognizable domestic brands.
In November 2021, Encube agreed to acquire Soframycin and related brands from Sanofi for the India and Sri Lanka markets. The transaction also included Sofradex, Sofracort and Soframycin-Tulle.
Sanofi’s filings subsequently confirmed the transfer of the brands, trademarks and associated technical know-how/manufacturing dossiers to Encube.
The transaction was strategically important because it gave Encube an established consumer-facing brand alongside its existing B2B manufacturing and CDMO operations.
5. Manufacturing Infrastructure
Encube operates manufacturing facilities in Goa and Indore.
As of March 31, 2026:
- Aggregate manufacturing capacity: 15,624 metric tonnes
- Filling & packaging capacity: 807 million units
- Goa capacity: approximately 11,160 MT
- Indore capacity: approximately 3,960 MT, with additional capacity commissioned after March 2026
- Dedicated hormone manufacturing capability in Goa
The company’s 807-million-unit filling and packaging capacity was reported as approximately 2.8 times the estimated total U.S. topical market demand for FY26, according to the Frost & Sullivan report cited in the IPO documents.
Encube’s official manufacturing information also highlights its Goa flagship facility, Goa hormone unit and Indore facility.
6. Regulatory Approvals
Pharmaceutical manufacturing for the U.S., Europe and other regulated markets requires significant regulatory compliance.
Encube’s manufacturing facilities have accreditations/approvals from 11 regulatory authorities, including:
- U.S. FDA
- EU GMP
- Japan PMDA
- Health Canada
- Brazil ANVISA
- EAEU
- Australia’s TGA
This regulatory infrastructure provides the company with access to multiple international markets.
7. R&D Capabilities
Encube operates the Encube Advanced Research Centre (EARC) in Palava, Mumbai.
As of March 31, 2026:
- Facility size: 117,252 sq. ft.
- R&D employees: 228
- PhDs: 12
- U.S. FDA-approved facility
The research platform focuses on topical, transdermal and complex drug-delivery technologies.
The company is also developing more complex products such as:
- Biphasic gels
- Microsphere-based formulations
- Thermogels
- Transdermal patches
- Vaginal rings
- Other advanced drug-delivery systems
8. Global Presence
Encube had a presence across 50 countries as of March 31, 2026.
Its customer base includes pharmaceutical companies in:
- United States
- United Kingdom
- Europe
- India
- Other international markets
The company’s U.S. subsidiary, Encube Ethicals Inc., is based in Durham, North Carolina and supports the company’s U.S. commercial operations.
The company says its U.S. operations include topical ANDAs listed under the FDA Orange Book and relationships with wholesalers, distributors and retail pharmacies.
9. Customer Mix
Encube’s business is significantly international.
For FY26:
| Customer Geography | Approx. Share |
|---|---|
| International customers | 64% |
| Indian customers | 36% |
The company also served more than 160 pharmaceutical companies across 50 countries.
This international mix provides access to larger regulated markets but also exposes the company to foreign-exchange, regulatory and geopolitical risks.
10. Financial Performance
The latest restated financial figures filed in connection with the IPO show strong growth.
Consolidated Financials
| ₹ Crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue from Operations | 1,085.9 | 1,344.8 | 1,848.7 |
| EBITDA | 297.6 | 452.1 | 663.3 |
| EBITDA Margin | 27.41% | 33.62% | 35.88% |
| PAT | 156.1 | 249.6 | 436.7 |
| PAT Margin | 14.38% | 18.56% | 23.62% |
| Net Worth | 1,258.4 | 1,512.8 | 1,953.6 |
| Borrowings | 228.1 | 230.5 | 221.7 |
| Assets | 1,871.8 | 2,300.1 | 2,792.1 |
FY26 Highlights
- Revenue from operations: ₹1,848.7 Cr
- EBITDA: ₹663.3 Cr
- PAT: ₹436.7 Cr
- EBITDA margin: 35.88%
- PAT margin: 23.62%
- ROE: 25.65%
- ROCE: 32.30%
- Borrowings: ₹221.7 Cr
- Net worth: ₹1,953.6 Cr
FY26 revenue from operations increased approximately 37.5% YoY, while PAT increased approximately 74.8% YoY.
11. Margin Expansion
One of the notable features of Encube’s recent financial performance is the expansion in profitability.
EBITDA margin:
- FY24: 27.41%
- FY25: 33.62%
- FY26: 35.88%
PAT margin:
- FY24: 14.38%
- FY25: 18.56%
- FY26: 23.62%
The improvement reflects the company’s growing scale, increasing contribution from global generics/CDMO and its specialized positioning in topical formulations.
12. U.S. Topical Generics Opportunity
The United States is an important growth market for Encube.
The company has established a significant position in U.S. topical generics, while its product pipeline includes both simple and complex formulations.
According to the Frost & Sullivan analysis cited in the IPO material, Encube was the third-largest U.S. topical generics player by volume in FY26, with a reported 12.18% market share.
The company is also targeting more complex topical products where formulation expertise and regulatory capabilities can create higher barriers to entry.
13. Competitive Advantages
Specialized topical expertise
Unlike broad-based pharmaceutical manufacturers, Encube is highly focused on topical and transdermal formulations.
Integrated platform
The company combines:
R&D + Manufacturing + Regulatory + CDMO + Generics + Branded Products
This allows it to serve customers across multiple stages of the pharmaceutical lifecycle.
Regulatory capabilities
Approvals across 11 major regulatory authorities provide access to several regulated markets.
Large manufacturing capacity
The 807-million-unit filling and packaging capacity provides significant room for volume expansion.
Established domestic brand
Soframycin provides a consumer-facing platform in addition to Encube’s B2B international businesses.
14. IPO Details – Major Development
Encube Ethicals has now moved from the private/unlisted market toward a public listing.
The company filed its Draft Red Herring Prospectus (DRHP) with SEBI in August 2026. SEBI’s official filing confirms Encube Ethicals’ DRHP as a public-issue document filed in August 2026.
Proposed IPO
| Particular | Details |
|---|---|
| IPO Size | Up to ₹3,000 Cr |
| Fresh Issue | Nil |
| Offer for Sale | ₹3,000 Cr |
| Issue Type | 100% OFS |
| Proposed Exchanges | NSE & BSE |
| Face Value | ₹1 |
| QIB Allocation | Up to 50% |
| NII Allocation | At least 15% |
| Retail Allocation | At least 35% |
| Price Band | Not announced |
| IPO Dates | Not announced |
The entire proposed ₹3,000 crore issue is an Offer for Sale, meaning the proceeds will go to the selling shareholders rather than being raised as fresh capital by Encube.
15. Selling Shareholders
The proposed OFS includes:
- Mehul Madhusudan Shah – promoter
- Frontier Investment Holdings Pte. Ltd.
The pre-IPO shareholding reported in the DRHP was approximately:
| Shareholder | Holding |
|---|---|
| Promoter / Promoter Group | 80.63% |
| Frontier Investment Holdings | 15.02% |
| Others | Balance |
Frontier Investment Holdings is associated with Quadria Capital, which has been an institutional investor in Encube.
16. IPO Valuation Context
Media reports in early 2026 indicated that Encube had attracted interest from large private-equity investors at valuations around ₹16,500 crore / $1.8 billion. However, this was reported transaction-market information and should not be treated as the final IPO valuation.
The final IPO valuation will depend on the price band and offer price disclosed in subsequent IPO documents.
At FY26 reported PAT of ₹436.7 crore, a ₹16,500 crore valuation would imply roughly 37.8x FY26 PAT. This is only an illustrative calculation based on the reported valuation and FY26 PAT, not a confirmed IPO valuation.
17. IPO Proceeds – Important Point
Because the proposed issue is 100% OFS, Encube itself will not receive the ₹3,000 crore IPO proceeds.
This is different from an IPO containing a fresh issue, where the company receives capital for purposes such as:
- Capacity expansion
- Debt repayment
- R&D
- Acquisitions
- Working capital
In Encube’s proposed structure, the IPO primarily provides an exit/liquidity mechanism for existing shareholders.
18. Key Growth Drivers
U.S. topical generics
Expansion of the company’s U.S. topical portfolio could remain a major growth driver.
CDMO growth
More global pharmaceutical companies outsourcing formulation development and manufacturing can potentially expand Encube’s CDMO opportunity.
Complex formulations
The company is investing in more sophisticated topical and transdermal technologies.
Manufacturing capacity
Existing capacity provides room for additional volumes without requiring immediate proportional expansion.
Soframycin
The established domestic brand gives Encube a consumer-facing platform in India.
International expansion
The company already operates across 50 countries, providing a foundation for further geographical expansion.
19. Key Risks
1. 100% OFS IPO
The proposed IPO does not provide fresh capital to Encube.
2. Regulatory risk
Topical pharmaceuticals require approvals and ongoing compliance across multiple jurisdictions.
3. U.S. market dependence
International markets, particularly the U.S., are important to the business. Changes in FDA requirements, pricing or competition could affect performance.
4. Currency risk
With a significant international customer base, foreign-exchange movements can influence reported financial results.
5. Product concentration
The company’s specialization in topical formulations is a competitive advantage but also means it is less diversified across therapeutic categories than large multi-segment pharmaceutical companies.
6. IPO valuation
A strong business does not automatically imply that any IPO valuation will be attractive. The final issue price and resulting P/E/P/S multiples will be important.
7. OFS structure
Since the IPO is entirely OFS, investors should understand that the company itself is not raising fresh growth capital through the issue.
20. Unlisted / Pre-IPO Status
Encube is currently transitioning from the unlisted market toward a proposed public listing.
Latest status:
- Unlisted company: Yes
- DRHP filed with SEBI: Yes
- Proposed IPO: ₹3,000 Cr
- Fresh issue: Nil
- OFS: ₹3,000 Cr
- Price band: Not announced
- IPO dates: Not announced
- Proposed listing: NSE & BSE
- Current NSE/BSE market price: Not applicable
SEBI’s official filing confirms the August 2026 DRHP.
21. UnlistedCart Takeaway
Encube Ethicals is a specialized pharmaceutical platform built around topical and transdermal formulations, with three complementary businesses: Global Generics, Global CDMO and India Branded Formulations.
FY26 was a strong financial year, with revenue from operations reaching approximately ₹1,848.7 crore, EBITDA of ₹663.3 crore and PAT of ₹436.7 crore. EBITDA margin reached 35.88%, while PAT margin increased to 23.62%.
The company has also built substantial manufacturing and regulatory infrastructure, including 15,624 MT manufacturing capacity, 807 million units of filling/packaging capacity, 50-country reach, 160+ pharmaceutical customers and 550+ SKUs.
The biggest development for investors is the proposed ₹3,000 crore IPO, which is structured entirely as an OFS by existing shareholders. Therefore, the key factor for investors will be the final IPO valuation, rather than assuming that the ₹3,000 crore issue itself represents fresh capital entering the company.
Key Sources
- Encube Ethicals – Official Website
- Encube Ethicals – Manufacturing & Capabilities
- Encube Ethicals USA
- SEBI – Encube Ethicals DRHP Filing
- Sanofi India – Annual Report 2022
- Moneycontrol – Encube Ethicals IPO Filing
Disclaimer: This report is for informational and educational purposes only and should not be considered investment advice. Encube Ethicals is currently unlisted and is in the IPO process. The final price band, issue dates, valuation and listing details may change. Unlisted/pre-IPO transactions can involve significant liquidity, transfer and valuation risks. Investors should review the final RHP/prospectus and latest audited disclosures before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
