
Unlisted Share Report | Pharmaceuticals
1. Company Overview
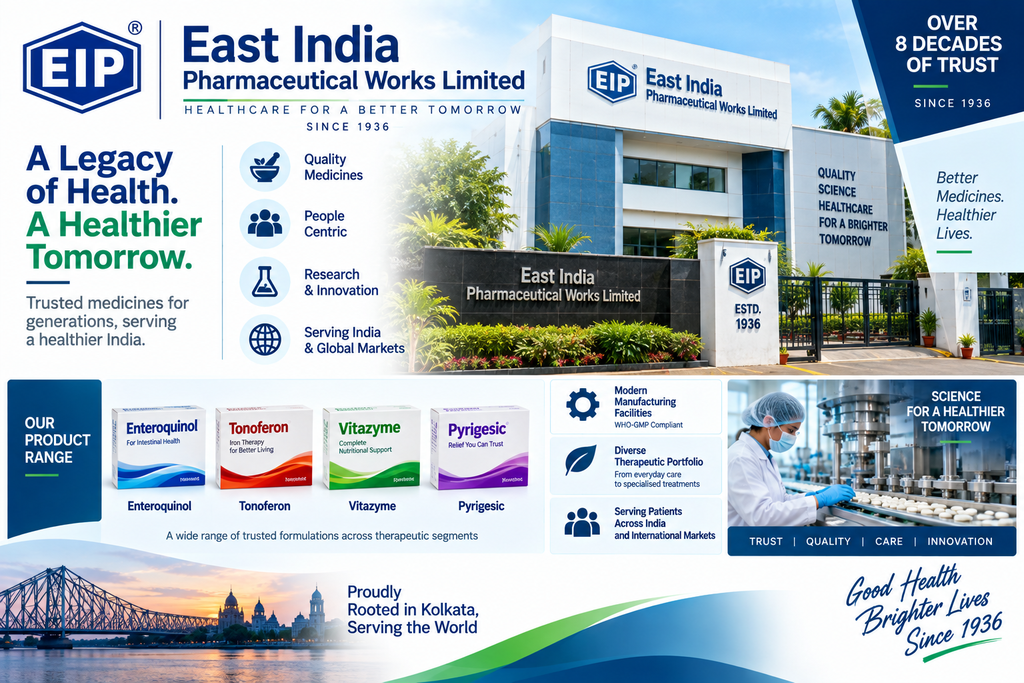
East India Pharmaceutical Works Limited (EIPWL) is one of India’s older pharmaceutical companies, incorporated on 27 April 1936 and headquartered in Kolkata, West Bengal.
The company develops, manufactures and markets pharmaceutical formulations across multiple therapeutic segments. It operates manufacturing facilities in West Bengal and has a long-standing portfolio of branded formulations.
Corporate Details
| Particular | Details |
|---|---|
| Company | East India Pharmaceutical Works Limited |
| Incorporation | 27 April 1936 |
| CIN | U24231WB1936PLC008598 |
| ISIN | INE254X01017 |
| Registered Office | Kolkata, West Bengal |
| Face Value | ₹10 |
| Paid-up Capital | ~₹6.67 Cr |
| Shares Outstanding | 66,74,858 |
| Status | Public Unlisted Company |
| Sector | Pharmaceuticals |
2. Business Model
EIPWL operates primarily in pharmaceutical manufacturing and marketing, with products covering several therapeutic categories.
Its manufacturing capabilities include:
- Tablets
- Dry syrups
- Liquid oral formulations
- Ointments
- Pharmaceutical packaging
- Selected APIs
The company manufactures APIs internally for some important products, including Enteroquinol and Tonoferon, while sourcing APIs for other formulations. Its manufacturing facilities have historically included a formulation plant at Sarsuna and an API plant at Durgapur in West Bengal.
3. Product Portfolio
The company has a portfolio spanning several therapeutic categories:
- Anti-protozoal
- Haematinics
- Analgesics & antipyretics
- Anti-infectives
- Gastrointestinal
- Ophthalmic
- Probiotics
- Vitamins & minerals
- Digestive enzymes
- Nutritional products
- Select herbal/Ayurvedic products
Some of its established brands include:
Enteroquinol, Tonoferon, Vitazyme and Pyrigesic.
Its current product listings also include products such as Locula, Bactiv, Prostalyn, Flemoxin, Trikase and Zoamet.
4. Manufacturing & Market Presence
The company has a long operating history and established manufacturing infrastructure in West Bengal.
Its facilities have been associated with WHO-GMP standards, while its product portfolio has historically been distributed across multiple Indian markets.
The company has also been described as having an international presence, with exports to multiple countries across Asia, Africa, Europe and other markets.
5. Financial Performance
FY25 vs FY24
₹ Crore
| Particular | FY24 | FY25 | Change |
|---|---|---|---|
| Revenue from Operations | 249.81 | 271.69 | +8.7% |
| Total Income | 249.94 | 271.84 | +8.8% |
| PBT | 4.54 | 4.19 | -7.7% |
| PAT | 3.87 | 2.21 | -43.0% |
| EPS | ₹5.80 | ₹3.31 | -42.9% |
| Operating Cash Flow | 2.33 | 6.19 | Improved |
Revenue growth was healthy, but profitability declined significantly in FY25. PAT fell from ₹3.87 Cr to ₹2.21 Cr despite revenue increasing by almost 9%.
Key observation
The major issue is not topline growth but low profitability.
FY25 PAT margin was only around 0.8%, meaning the company is operating on relatively thin net margins.
6. Balance Sheet
| Particular | FY25 |
|---|---|
| Net Worth | ₹57.82 Cr |
| Long-term Borrowings | ₹4.35 Cr |
| Short-term Borrowings | ₹49.10 Cr |
| Total Borrowings | ~₹53.45 Cr |
| Inventory | ₹31.81 Cr |
| Trade Receivables | ₹148.68 Cr |
| Cash & Equivalents | ₹8.50 Cr |
| Fixed Assets | ₹13.08 Cr |
The company has a working-capital-intensive balance sheet, particularly because of the large trade receivables balance.
Trade receivables of ~₹148.7 Cr are substantial relative to annual revenue of ₹271.7 Cr.
7. Cash Flow
FY25 operating cash flow improved materially:
Operating Cash Flow: ₹6.19 Cr
vs.
FY24: ₹2.33 Cr
Cash flow benefited from working-capital movements, including lower inventory and higher payables, although receivables increased significantly.
This is an important metric to monitor because the company’s business requires significant working capital.
8. Shareholding Pattern
As of 31 March 2025:
| Category | Holding |
|---|---|
| Promoters | 25.87% |
| Others | 74.13% |
| Total | 100% |
The relatively low promoter ownership means the company has a broad non-promoter shareholder base compared with many closely held unlisted companies.
9. Management
Key management/directors include:
- Debarshi Duttagupta – Managing Director
- Satarupa Mukherjee – Executive Director
- Probir Roy – Chairman
- Jayeeta Sarkar – Company Secretary
The company’s current Managing Director was appointed for a three-year term beginning September 2024.
10. Unlisted Share Price
There is no NSE/BSE traded market price because EIPWL is unlisted.
Recent private-market references show considerable variation:
- Moneycontrol: approximately ₹79.88/share
- Planify: approximately ₹126.50/share as of 14 September 2026
- ShareSaathi: approximately ₹79/share as of 27 August 2026
This wide range highlights the limited liquidity and fragmented price discovery in unlisted shares.
At ₹79.88, the implied equity value is around ₹53 Cr.
At ₹126.50, the implied equity value is around ₹84.4 Cr.
Based on FY25 EPS of ₹3.31, these prices correspond approximately to 24x–38x FY25 earnings.
Therefore, investors should not rely on a single dealer quote when assessing valuation.
11. IPO / Listing Status
EIPWL is currently an unlisted public company.
Moneycontrol currently shows DRHP Status: No, and there is no confirmed NSE/BSE IPO timetable identified in the sources reviewed.
A future IPO or listing should therefore be treated as uncertain rather than assumed.
12. Growth Drivers
1. Long operating history
Nearly nine decades in pharmaceuticals provides established manufacturing experience and brand recognition.
2. Established brands
Brands such as Enteroquinol, Tonoferon, Vitazyme and Pyrigesic provide an existing product base.
3. Product diversification
The company operates across multiple therapeutic segments rather than depending on a single product category.
4. Manufacturing capabilities
In-house manufacturing and selected API capabilities can provide greater control over production for key products.
5. Revenue growth
FY25 revenue increased approximately 8.7%, indicating continued business expansion.
6. Export opportunity
Expansion into international pharmaceutical markets could provide an additional growth avenue.
13. Key Risks
⚠️ Low profitability
Despite ₹271.7 Cr revenue, FY25 PAT was only ₹2.21 Cr.
⚠️ Working-capital intensity
Trade receivables were approximately ₹148.7 Cr, creating a significant cash-conversion risk.
⚠️ Borrowings
Total borrowings were approximately ₹53.45 Cr against net worth of ₹57.82 Cr.
⚠️ Competitive pressure
ICRA noted intense competition in therapeutic categories such as antiprotozoals, digestive enzymes, haematinics, analgesics and antipyretics, which has pressured operating margins.
⚠️ Credit rating
In September 2025, ICRA downgraded the company’s long-term rating to [ICRA]BB+ (Stable) and short-term rating to [ICRA]A4+, citing a sustained weak operating/financial profile and liquidity deterioration.
⚠️ Unlisted liquidity
There is no continuous exchange market, so buying and selling can take time and private-market prices can vary significantly between intermediaries.
14. Investment Snapshot
| Parameter | View |
|---|---|
| Business age | 90+ years |
| Sector | Pharmaceuticals |
| FY25 Revenue | ₹271.7 Cr |
| FY25 PAT | ₹2.2 Cr |
| FY25 OCF | ₹6.2 Cr |
| Net Worth | ₹57.8 Cr |
| Borrowings | ~₹53.5 Cr |
| Promoter Holding | 25.87% |
| Indicative Unlisted Price | ~₹80–₹126.5 |
| Implied Market Cap | ~₹53–84 Cr |
| IPO | No confirmed IPO |
| NSE/BSE Listed | No |
15. UnlistedCart Takeaway
East India Pharmaceutical Works is a legacy Indian pharmaceutical manufacturer with a diversified product portfolio, established brands and a long operating history.
The interesting part of the story is the combination of established pharmaceutical brands + manufacturing capabilities + potential operating improvement.
However, the key numbers to watch are profit margins, receivables, debt and cash generation. FY25 revenue grew strongly, but PAT declined materially, while working-capital requirements remain high.
At the current indicative private-market prices, the valuation should therefore be assessed carefully against the company’s actual earnings and future margin improvement, rather than only its long operating history.
Official & Research Sources
East India Pharmaceutical Works – Official Website
Moneycontrol – Unlisted Share Information
Planify – East India Pharmaceutical Works Research
Disclaimer: This report is for informational and research purposes only. Unlisted-share prices are indicative and can vary significantly based on liquidity, lot size, seller availability and transaction terms. Unlisted securities carry higher liquidity and valuation risks and are not guaranteed to list in the future. Investors should conduct independent due diligence before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
