
1. Company Overview
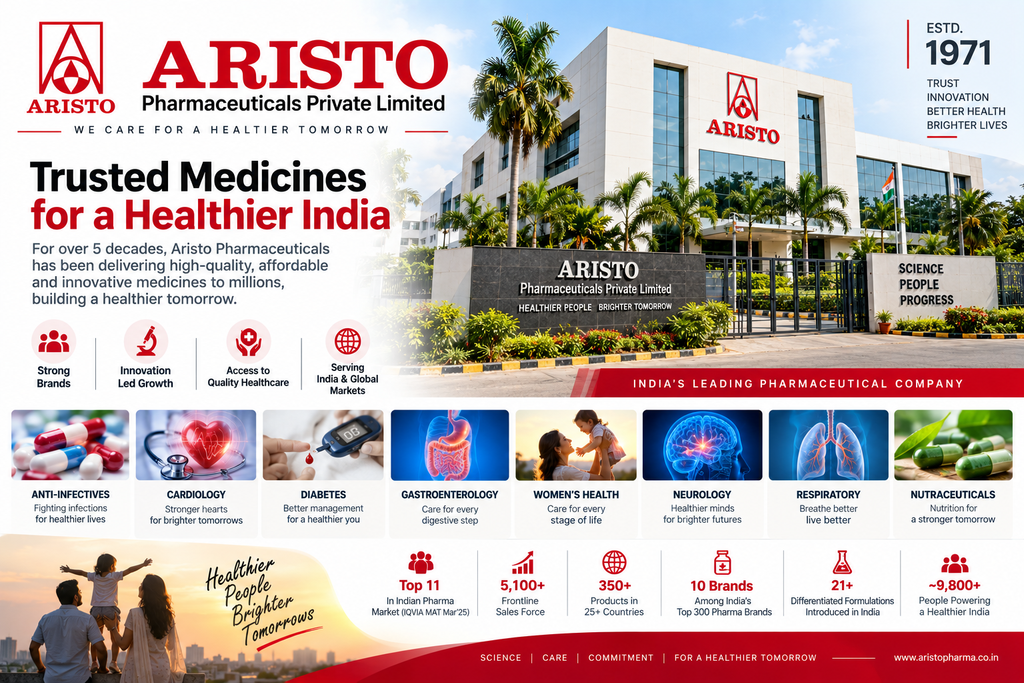
Aristo Pharmaceuticals Private Limited is a Mumbai-based pharmaceutical company established in 1971. The company develops, manufactures and markets branded pharmaceutical formulations across multiple therapeutic areas.
Aristo is a private, unlisted company with CIN U24239MH1971PTC015425. Its registered office is at Shah Industrial Estate, Andheri West, Mumbai.
| Particular | Details |
|---|---|
| Company | Aristo Pharmaceuticals Private Limited |
| Former name | Aristo Pharmaceuticals Limited |
| Incorporated | 8 November 1971 |
| CIN | U24239MH1971PTC015425 |
| Registered Office | Mumbai, Maharashtra |
| Authorised Capital | ₹99 lakh |
| Paid-up Capital | ₹98.97 lakh |
| Status | Private & Unlisted |
| Industry | Pharmaceuticals |
| Business | Branded formulations / healthcare |
| Employees | ~9,800–11,000+ |
| Managing Director | Umesh Sharma |
The latest MCA-linked records show that the company remained active and filed financial statements for the year ended 31 March 2025, with its AGM held in September 2025.
2. Business Model
Aristo follows a branded-generics / prescription pharmaceutical business model.
The company focuses heavily on the Indian domestic pharmaceutical market, supported by a large medical-representative and sales network.
Its major therapeutic areas include:
- Antibiotics
- Anti-infectives
- Gastroenterology
- Cardiology
- Diabetes
- Hypertension
- Pain management
- Nutraceuticals
- Vitamins & minerals
- Neurology
- Respiratory care
- Women’s health
- Other chronic and acute therapies
Aristo’s official website describes the company as focused on building pharmaceutical brands and developing differentiated formulations.
3. Scale of the Business
Aristo is considerably larger than the typical unlisted pharmaceutical company.
According to the company’s own IQVIA-based data for MAT March 2025:
- India Pharma Market revenue: ₹1,96,696 Cr
- Aristo revenue: ₹5,700.38 Cr
- Aristo market share: 2.90%
- India pharma ranking: #11
- Covered-market ranking: #3
- Prescription-audit ranking: #5
- Front-line sales force: ~5,100
- Five-year CAGR: 10.76%
These figures are company-reported IQVIA/IMS data and refer to the Indian pharmaceutical market rather than the company’s statutory financial statements.
Aristo also states that it has 10 brands among India’s top 300 pharmaceutical brands.
4. Brand Portfolio
Aristo has developed a large branded portfolio.
Some of its prominent brands and formulations include:
- Aristozyme
- Aristozyme Gold
- Gabaneuron
- Montina
- Montair
- Darolac
- Zerotuss
- Ambrodil
- Atchol
- Gluflozin
- Meloset
- Pantop
- Vasonext
- Folinext
- Monocef
- Mikacin
- Protone
The company says it has introduced 21+ differentiated formulations for the first time in India over its history.
Examples cited by Aristo include the introduction of:
- Protone — protein liquid
- Aristogyl — metronidazole oral liquid
- Aristozyme — fungal diastase liquid
- Mikacin — amikacin
- Monocef — ceftriaxone
- Meloset — melatonin
- Gabaneuron — gabapentin/methylcobalamine
- Montaz — ceftriaxone/tazobactam
These claims are based on the company’s own product-development disclosures.
5. Domestic Market Position
Aristo’s core strength is its Indian branded-prescription business.
The company says it has grown faster than the overall Indian pharma market over the long term and has reached the top tier of Indian-owned pharmaceutical organisations by domestic turnover.
Its 5,100-member front-line sales force provides a significant distribution and doctor-connect advantage.
The company’s reported five-year CAGR of 10.76% is also higher than the reported growth of the overall Indian pharma market over the same period.
6. International Business
Aristo is not purely India-focused.
The company states that it has established an international presence across:
- Africa
- South America
- Middle East
- Southeast Asia
- CIS markets
It reports registrations for 350+ products across 25+ countries.
Its international portfolio is particularly focused on:
- Antibiotics
- Cardiovascular products
- Anti-diabetics
- Gastroenterology
- Pain management
- Nutraceuticals
- Food supplements
7. Research & Development
R&D and differentiated formulations are important components of Aristo’s strategy.
The company says its R&D programme focuses on developing formulations that offer differentiated delivery mechanisms, combinations or dosage forms.
The company has highlighted more than 21 formulations introduced for the first time in India, reflecting its emphasis on formulation innovation rather than only commodity generics.
Aristo has also entered into technical collaboration with Chr. Hansen, Denmark, for ProGG, based on Lactobacillus rhamnosus GG.
8. FY25 Financial Performance
Standalone financials
₹ Crore
| Particular | FY24 | FY25 | Growth |
|---|---|---|---|
| Revenue from Operations | ₹4,750.0 Cr | ₹4,941.2 Cr | +4.0% |
| Other Income | ₹344.3 Cr | ₹422.1 Cr | +22.6% |
| Total Income | ₹5,094.4 Cr | ₹5,363.3 Cr | +5.3% |
| Operating Profit / EBITDA | ₹1,655.6 Cr | ₹1,939.5 Cr | +17.2% |
| PBT | ₹1,920.1 Cr | ₹2,280.0 Cr | +18.7% |
| PAT | ₹1,466.3 Cr | ₹1,700.6 Cr | +16.0% |
FY25 financial data reported by Tofler shows ₹5,363.3 Cr total revenue, ₹1,939.5 Cr EBITDA and ₹1,700.6 Cr net profit.
Business Standard’s 2026 unlisted-company database independently reports approximately ₹5,267 Cr revenue, ₹1,701 Cr profit and ₹7,194 Cr net worth for Aristo, with the difference in revenue likely reflecting the use of different financial definitions/data treatments.
Key takeaway
The important feature of Aristo’s FY25 numbers is the very high profitability:
EBITDA margin: ~39.2%
Net profit margin: ~31.7%
This is substantially higher than what is normally seen in many conventional pharmaceutical manufacturing businesses.
9. Five-Year Financial Trend
₹ Crore
| FY | Revenue from Operations | EBITDA | PAT |
|---|---|---|---|
| FY21 | 3,016.7 | 1,083.3 | 901.2 |
| FY22 | 4,098.7 | 1,457.8 | 1,244.2 |
| FY23 | 4,365.3 | 1,499.5 | 1,254.0 |
| FY24 | 4,750.0 | 1,655.6 | 1,466.3 |
| FY25 | 4,941.2 | 1,939.5 | 1,700.6 |
Between FY21 and FY25:
Revenue: ₹3,017 Cr → ₹4,941 Cr
EBITDA: ₹1,083 Cr → ₹1,940 Cr
PAT: ₹901 Cr → ₹1,701 Cr
The five-year earnings trajectory therefore shows substantial growth in both operating profit and net profit.
Tofler’s pharma-industry benchmarking also places Aristo’s FY22–FY25 EBITDA CAGR at approximately 10%.
10. Balance Sheet
FY25 reported balance-sheet highlights:
| Particular | FY25 |
|---|---|
| Net Worth | ₹7,194 Cr |
| Total Assets | ₹7,617.5 Cr |
| Borrowings | Nil / negligible |
| Cash & Cash Equivalents | ₹449.3 Cr |
| Inventory | ₹656.0 Cr |
| Trade Receivables | ₹53.1 Cr |
| Fixed Assets | ₹526.3 Cr |
| Other Non-current Assets | ₹3,927.4 Cr |
| Other Current Assets | ₹2,005.0 Cr |
| Debt/Equity | ~0x |
The most notable balance-sheet feature is the absence of meaningful financial debt.
Aristo’s reported net worth increased from approximately ₹6,040 Cr in FY24 to ₹7,194 Cr in FY25.
11. Cash Flow
FY24 operating cash flow was approximately:
₹1,179 Cr
The FY25 detailed cash-flow statement is not fully exposed in the free public databases reviewed, so I would avoid presenting an unverified FY25 operating-cash-flow number as fact.
The broader financial picture, however, is supported by:
- strong PAT
- negligible debt
- increasing net worth
- substantial cash balances
The FY24 cash-flow statement showed operating cash generation of ₹1,179.4 Cr, while investing cash flow was negative ₹652.1 Cr and financing cash flow negative ₹524.3 Cr.
12. Profitability & Financial Ratios
FY25 reported ratios include:
| Metric | FY25 |
|---|---|
| EBITDA Margin | ~39.2% |
| Net Profit Margin | ~31.7% |
| ROE | ~23.6% |
| ROCE | ~54.1% |
| Current Ratio | ~13.3x |
| Debt/Equity | ~0x |
This indicates a business with:
High margins + strong return ratios + very low leverage.
13. Management
Current directors identified in recent corporate records include:
- Umesh Sharma – Managing Director
- Randhir Kumar Bachan – Whole-Time Director
- Virendra Sharma – Director
Umesh Sharma has been associated with the company as Managing Director since 1979, while Randhir Kumar Bachan became a director in 2005 and Virendra Sharma in 2006.
The long tenure of the senior management team is a notable feature of the company.
14. Group Ecosystem
Aristo operates within a broader group ecosystem that includes associated pharmaceutical entities such as:
- Aristo Laboratories Private Limited
- Mapra Laboratories
- Other group/associated companies
Aristo’s own FY25 CSR impact report identifies Mapra Laboratories and Aristo Laboratories among associated companies within the broader group ecosystem.
Aristo Laboratories itself reported FY25 revenue of approximately ₹461.4 Cr according to current company records.
This broader ecosystem should be considered when analysing the group’s overall pharmaceutical footprint, although the entities should not be combined with Aristo Pharmaceuticals’ standalone financials without proper consolidation evidence.
15. Unlisted Share Status
Important
Aristo Pharmaceuticals is not an exchange-listed company.
It is structured as a private limited company, with paid-up capital of only approximately ₹98.97 lakh.
Therefore, unlike companies such as Care Health, PharmEasy or Penam Laboratories that are commonly discussed in private-market share transactions, I did not find a reliable current dealer/OTC quote for Aristo Pharmaceuticals shares.
I would therefore not put an artificial “current share price” in an investor report without a verified transaction or seller quote.
16. Valuation
Because there is no reliable publicly quoted unlisted share price, a conventional P/E valuation cannot be calculated from a market price.
However, the underlying financial numbers provide a useful valuation framework.
FY25
PAT: ₹1,700.6 Cr
Net Worth: ₹7,194 Cr
EBITDA: ₹1,939.5 Cr
Therefore, any private transaction valuation should be compared against:
- FY25 PAT
- EBITDA
- Net worth
- Domestic pharma market position
- Brand portfolio
- Growth rate
- International registrations
- Group structure
- Liquidity/transfer restrictions
Given the scale and profitability, Aristo is among the more financially substantial privately held pharmaceutical businesses in India.
JM Financial–Hurun’s Unlisted Gems 2026 placed Aristo among India’s leading unlisted companies, reporting FY25 EBITDA of approximately ₹2,362 Cr under its methodology and an EBITDA margin of 44%. The difference versus Tofler’s ₹1,939.5 Cr EBITDA reflects different datasets/financial definitions, so these figures should not be mixed in a single valuation model.
17. IPO / Listing Status
Aristo Pharmaceuticals is currently private and unlisted.
I did not find a confirmed DRHP, IPO price band or listing timetable in the sources reviewed.
Therefore:
IPO status: No confirmed IPO
NSE/BSE listing: No
Any future listing should be treated as a potential corporate event rather than part of the base investment thesis.
18. Growth Drivers
1. Strong domestic franchise
Aristo has built a significant Indian branded-pharma business, with the company reporting a #11 position in the Indian Pharma Market based on IQVIA MAT March 2025.
2. Large sales force
Approximately 5,100 front-line sales professionals provide extensive doctor and prescription-market coverage.
3. Strong brands
Ten brands are reported among India’s top 300 pharmaceutical brands.
4. Product innovation
The company reports more than 21 formulations introduced for the first time in India.
5. International expansion
350+ product registrations across 25+ countries provide a platform for international growth.
6. High profitability
FY25 EBITDA of approximately ₹1,940 Cr and PAT of approximately ₹1,701 Cr provide substantial internal cash-generation potential.
7. Low leverage
The company reported virtually zero debt, providing significant financial flexibility.
19. Key Risks
⚠️ Private-company liquidity
There is no exchange market for the shares. Transferability and finding a buyer can be significantly more difficult than for listed securities.
⚠️ Valuation transparency
Without an actively traded market price, valuation depends on negotiated private transactions.
⚠️ Regulatory risk
Pharmaceutical companies operate under strict requirements relating to manufacturing, quality, pricing, pharmacovigilance and product approvals.
⚠️ Product concentration
Although Aristo has a diversified portfolio, its market position remains particularly important in prescription pharmaceutical segments such as antibiotics, cardio-diabetic and gastroenterology.
⚠️ Competition
Aristo competes with large Indian and multinational pharmaceutical companies with significant R&D, manufacturing and distribution capabilities.
⚠️ Data-definition differences
Different databases report somewhat different FY25 revenue/EBITDA numbers. For example, Tofler reports ₹5,363 Cr total revenue and ₹1,940 Cr EBITDA, while Hurun/JM Financial reports ₹5,267 Cr revenue and ₹2,362 Cr EBITDA under its methodology. These should be reconciled before a transaction-level valuation.
20. Investment Snapshot
| Parameter | Aristo Pharmaceuticals |
|---|---|
| Sector | Pharmaceuticals |
| Founded | 1971 |
| Headquarters | Mumbai |
| FY25 Revenue | ~₹4,941 Cr operating revenue |
| FY25 Total Revenue | ~₹5,363 Cr |
| FY25 EBITDA | ~₹1,940 Cr |
| FY25 PAT | ~₹1,701 Cr |
| FY25 Net Worth | ~₹7,194 Cr |
| EBITDA Margin | ~39% |
| PAT Margin | ~32% |
| Debt | Negligible |
| India Pharma Rank | #11 |
| Covered Market Rank | #3 |
| Front-line Sales Force | ~5,100 |
| International Registration | 350+ products / 25+ countries |
| Listed | No |
| IPO | No confirmed IPO |
| Current OTC Price | No reliable public quote |
21. UnlistedCart Takeaway
Aristo Pharmaceuticals stands out as a large, highly profitable, privately held Indian pharmaceutical company with a strong branded-prescription franchise.
The numbers are particularly notable:
₹4,941 Cr FY25 operating revenue
₹1,940 Cr EBITDA
₹1,701 Cr PAT
₹7,194 Cr net worth
Virtually zero debt
The company’s domestic market position, 5,100-member sales force, strong brand portfolio and international registrations provide multiple avenues for continued growth.
The biggest challenge for an unlisted investor is not the operating business but access and valuation.
Because Aristo is a private company and there is no transparent exchange or dependable OTC price, investors should obtain:
latest audited financials → latest shareholding → exact number of shares offered → seller’s transaction price → transfer restrictions → valuation of the entire company
before evaluating any secondary-share opportunity.
In short, Aristo is a fundamentally large and profitable private pharma business, but the investment case in its shares depends heavily on the price and terms at which those private shares can actually be acquired.
Sources & Links
Aristo Pharmaceuticals – Official Website
Aristo Pharmaceuticals – About Us
Aristo Pharmaceuticals – International Presence
Aristo Pharmaceuticals – FY2024-25 CSR Impact Report
Tofler – Aristo Pharmaceuticals Financials
CompanyCheck – Aristo Pharmaceuticals Corporate Information
ZaubaCorp – Aristo Pharmaceuticals Corporate Records
JM Financial–Hurun India Unlisted Gems 2026
Disclaimer: This report is for informational and research purposes only. Aristo Pharmaceuticals is a private, unlisted company and does not have a continuously traded market price. Financial figures from different databases may use different reporting definitions; audited financial statements should be used for transaction-level diligence. Private-company shares may have transfer restrictions and limited liquidity. This is not investment advice.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
