
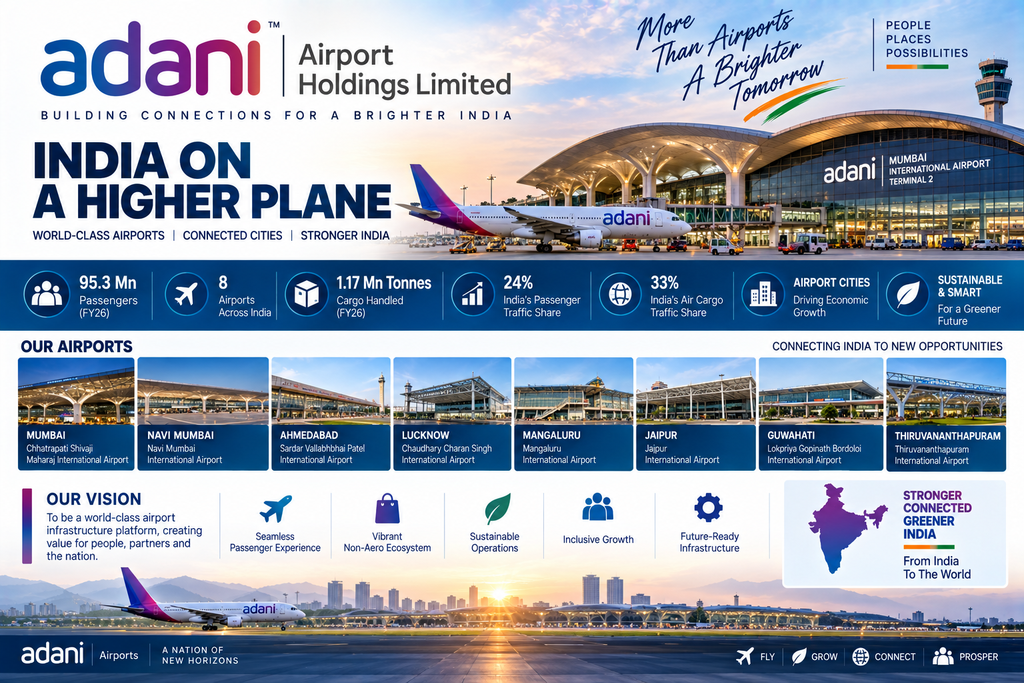
India’s Airport Infrastructure & Airport-City Platform
Company Overview
Adani Airport Holdings Limited (AAHL) is the airport infrastructure platform of Adani Enterprises Limited (AEL). Incorporated in 2019, AAHL operates and develops a portfolio of major Indian airports and airport-related businesses.
AAHL currently manages eight airports, including Mumbai and the newly operational Navi Mumbai International Airport. The company describes itself as India’s largest airport infrastructure company by airport portfolio, accounting for approximately 24% of India’s passenger traffic and 33% of Indian air cargo traffic.
Official website: Adani Airports
Airport Portfolio
AAHL’s current portfolio comprises:
| Airport | Location | Status |
|---|---|---|
| Mumbai International Airport | Mumbai | Operational |
| Navi Mumbai International Airport | Maharashtra | Operational |
| Sardar Vallabhbhai Patel International Airport | Ahmedabad | Operational |
| Chaudhary Charan Singh International Airport | Lucknow | Operational |
| Mangaluru International Airport | Karnataka | Operational |
| Jaipur International Airport | Rajasthan | Operational |
| Lokpriya Gopinath Bordoloi International Airport | Guwahati | Operational |
| Thiruvananthapuram International Airport | Kerala | Operational |
AAHL holds approximately 73% in Mumbai International Airport Limited (MIAL), which in turn holds 74% of Navi Mumbai International Airport Limited (NMIAL).
Scale of Operations
According to the latest company information, Adani Airports handled approximately 96.4 million passengers in FY26, equivalent to about 24% of India’s overall passenger traffic.
The platform also facilitates approximately 33% of India’s air-cargo traffic.
FY26 Operating Snapshot
| Metric | FY26 |
|---|---|
| Passenger traffic | 95.3 million |
| Air Traffic Movements | 619,000 |
| Cargo | 1.17 million tonnes |
| Passenger traffic growth | ~1% YoY |
| Cargo growth | ~7% YoY |
The slight difference between the 95.3 million FY26 figure in AEL’s financial presentation and the 96.4 million figure on the current Adani Airports website reflects differences in reporting definitions/timing; both are company-published figures.
Business Model
AAHL has two major revenue engines:
1. Aeronautical Revenue
Revenue generated from airport operations such as:
- Passenger charges
- Landing and parking charges
- User development fees
- Other regulated airport charges
2. Non-Aeronautical Revenue
This is becoming increasingly important and includes:
- Duty-free
- Food & beverages
- Retail & leasing
- Car parking
- Passenger services
- Advertising
- Ground handling
- Airport commercial development
The FY26 revenue mix was approximately:
| Revenue Segment | FY26 Revenue |
|---|---|
| Aero | ₹4,948 Cr |
| Non-Aero | ₹6,401 Cr |
| Cargo | ₹795 Cr |
| Others | ₹937 Cr |
| Total | ₹13,081 Cr |
Non-aero revenue increased approximately 31% YoY, while aero revenue increased approximately 26% YoY.
This is strategically important because airport operators can increase revenue per passenger through retail, food, duty-free, parking and commercial development even without a proportionate increase in passenger numbers.
FY26 Financial Performance
The Airports business under AEL reported the following:
| ₹ Crore | FY25 | FY26 | Growth |
|---|---|---|---|
| Total Income | 10,224 | 13,081 | +28% |
| EBITDA | 3,480 | 5,394 | +55% |
| PBT | (5) | 1,427 | Turned positive |
The strong EBITDA growth was significantly higher than revenue growth, reflecting operating leverage and higher contribution from the airport portfolio.
Important: These figures represent the Airports business segment reported by AEL, not necessarily the standalone legal-entity accounts of AAHL.
Navi Mumbai International Airport
One of the biggest developments for AAHL is the commencement of operations at Navi Mumbai International Airport (NMIA).
The airport commenced operations on 25 December 2025, with Phase 1 designed for approximately 20 million passengers annually.
The airport has a planned ultimate capacity of approximately 90 million passengers annually.
Navi Mumbai is strategically important because it gives AAHL exposure to a second major airport serving the Mumbai Metropolitan Region alongside Mumbai International Airport.
Airport City Opportunity
AAHL’s strategy extends beyond simply operating airports.
The company plans to develop integrated Airport City ecosystems around its airports.
The September 2026 capital-raise announcement states that approximately 22 million sq. ft. of mixed-use development is planned in the first phase of Airport City development.
Potential components include:
- Retail
- Hotels
- Offices
- Entertainment
- Commercial real estate
- Logistics
- Hospitality
- Transportation infrastructure
The broader plan is to increase AAHL’s passenger-handling capacity toward approximately 200 million passengers annually.
FY25 Asset Base
AEL’s FY25 investor presentation reported approximately ₹51,082 crore of gross assets for AAHL.
The long concession periods are another important feature of the business:
- Six airport concessions have approximately 50-year terms.
- MIAL’s concession extends to 2066.
- NMIAL’s concession extends to 2078, subject to the applicable concession terms.
Long concession periods can provide a substantial operating runway for airport infrastructure and commercial-development investments.
Ownership
As of the latest AEL corporate structure disclosures, Adani Enterprises Limited held 100% of AAHL as of March 31, 2026.
However, this is changing following a major institutional investment announced in September 2026.
New Institutional Investment
AAHL has entered into binding agreements to raise approximately:
₹9,825 crore (~US$1 billion)
from:
- Alpha Wave Global
- Premji Invest
- Temasek
- BlackRock-managed funds
The investors will collectively hold approximately 5.54% of AAHL after completion of all three tranches. The final tranche is expected to be completed by July 2027, subject to applicable conditions and approvals.
Latest Private Valuation
This transaction provides one of the most important valuation benchmarks for AAHL.
The investment values AAHL at approximately:
US$18 billion pre-money equity valuation
This is significant because it represents an external institutional valuation rather than merely an internal group valuation.
The transaction is therefore an important reference point for investors researching AAHL’s potential future listing or unlisted shares.
Important: This is a negotiated institutional transaction valuation, not an NSE/BSE traded market price.
Unlisted Share Status
AAHL is currently unlisted.
Company databases classify Adani Airport Holdings Limited as an unlisted public company.
There is consequently:
- No NSE share price
- No BSE share price
- No continuous public-market price discovery
- Potentially limited liquidity in any private transaction
Any dealer/private-market quote should be checked against the latest institutional valuation and the exact security/ISIN before considering a transaction.
IPO / Listing Potential
There have been previous reports that the Adani Group could eventually list the airport business.
However, an important distinction should be made between:
Reported IPO plans
and
A formally announced IPO with filed offer documents.
As of the latest information reviewed, there is no confirmed DRHP/IPO timetable establishing a fixed AAHL listing date.
The September 2026 institutional transaction itself provides for the final investment tranche to be completed by July 2027; therefore, any specific IPO date circulated in the market should be treated as a potential plan rather than a confirmed listing schedule.
Institutional Investors
The latest transaction brings several major global investors into AAHL:
Temasek
Singapore’s global investment company.
BlackRock-managed funds
Global investment-management platform.
Premji Invest
Indian investment firm associated with the Premji family.
Alpha Wave Global
Global investment firm.
Their participation establishes an external institutional valuation reference of approximately US$18 billion.
Debt & Credit Profile
AAHL is a capital-intensive infrastructure business.
CRISIL has assigned CRISIL AA-/Stable to AAHL’s rated debt instruments.
CRISIL reported that AAHL had approximately ₹600 crore of debt servicing obligations in each of FY26 and FY27, against expected cash flows of approximately ₹2,100 crore and ₹3,200 crore respectively.
The company was also expected to undertake approximately ₹14,000 crore of capex across FY26 and FY27, funded through internal accruals and additional debt.
CRISIL’s rating sensitivity includes maintaining debt/EBITDA around 5.0–5.5x on a sustained basis, while higher debt or weaker airport traffic/non-aero revenue could put pressure on the credit profile.
Growth Drivers
1. Indian Aviation Growth
Increasing domestic and international air travel provides the fundamental demand driver for AAHL.
2. Navi Mumbai Airport
NMIA adds another major airport to the Mumbai region and creates a long-term passenger and commercial opportunity.
3. Non-Aero Monetisation
Duty-free, food & beverage, retail, leasing, parking and passenger services are growing faster than passenger traffic.
FY26 non-aero revenue reached ₹6,401 crore, up approximately 31% YoY.
4. Airport City Development
Commercial development around airports can create additional revenue streams beyond conventional aviation income.
5. Capacity Expansion
The company is targeting capacity capable of serving approximately 200 million passengers annually.
6. Ground Handling & Adjacent Businesses
AAHL plans to expand ground handling and other passenger-facing businesses as part of its broader airport ecosystem.
7. Long-Term Concessions
Long concession periods provide a multi-decade operating horizon for infrastructure and commercial investments.
Key Risks
High Capital Requirement
Airport expansion requires substantial investment in terminals, runways, passenger facilities, technology and surrounding infrastructure.
Debt & Leverage
AAHL’s expansion is partly funded through debt. A major increase in capex without corresponding cash-flow growth could increase leverage.
Passenger Traffic Risk
Economic downturns, airline capacity constraints, geopolitical events or other disruptions can affect passenger traffic.
Regulatory Risk
Airport tariffs and several elements of aeronautical revenue are subject to regulatory oversight.
Non-Aero Litigation / Regulatory Issues
CRISIL has specifically identified adverse developments involving a component of the non-aero business before TDSAT as a potential rating sensitivity.
Execution Risk
The business has a substantial pipeline of airport expansion and Airport City projects. Delays or cost overruns could affect returns.
Unlisted Liquidity
AAHL shares do not currently have continuous NSE/BSE liquidity, making private-market entry and exit more complicated.
Why AAHL Is Interesting as an Unlisted Business
The AAHL story is broader than simply owning airports.
The platform combines:
Airports + Retail + Duty Free + Cargo + Ground Handling + Hospitality + Airport City + Commercial Real Estate
This creates multiple potential revenue streams from the same passenger ecosystem.
The FY26 numbers show this diversification clearly:
Aero Revenue: ₹4,948 Cr
Non-Aero Revenue: ₹6,401 Cr
Cargo Revenue: ₹795 Cr
Others: ₹937 Cr
UnlistedCart Takeaway
Adani Airport Holdings is one of the largest private airport infrastructure platforms in India, with eight airports, approximately 95–96 million annual passengers and a rapidly expanding non-aeronautical business.
The major developments to track are:
Navi Mumbai Airport → Non-Aero Monetisation → Airport City → Capacity Expansion → Institutional Capital
The ₹9,825 crore institutional fundraise at an approximately US$18 billion pre-money valuation is currently the most important external valuation benchmark for the business.
At the same time, AAHL remains a capital-intensive infrastructure business, so capex, debt, regulatory tariffs, passenger traffic and execution of airport-city projects remain important factors for investors to monitor.
Quick Snapshot
| Parameter | Adani Airport Holdings |
|---|---|
| Incorporated | 2019 |
| Promoter / Parent | Adani Enterprises Ltd |
| Status | Unlisted |
| Airports | 8 |
| FY26 Passenger Traffic | ~95.3 Mn |
| Current website traffic figure | ~96.4 Mn |
| India’s Passenger Traffic Share | ~24% |
| India’s Air Cargo Share | ~33% |
| FY26 Total Income | ₹13,081 Cr |
| FY26 EBITDA | ₹5,394 Cr |
| FY26 PBT | ₹1,427 Cr |
| FY26 Non-Aero Revenue | ₹6,401 Cr |
| Navi Mumbai Phase 1 | 20 Mn passengers/year |
| Long-term NMIA Capacity | ~90 Mn passengers/year |
| Target Network Capacity | ~200 Mn passengers/year |
| FY25 Gross Assets | ~₹51,082 Cr |
| Latest Institutional Raise | ₹9,825 Cr |
| External Valuation Benchmark | ~US$18 Bn pre-money |
| New Institutional Investors | Alpha Wave, Premji Invest, Temasek, BlackRock-managed funds |
| New Investor Stake | ~5.54% after all tranches |
| IPO | No confirmed IPO timetable |
| Key Theme | Airports + Non-Aero + Airport City |
Important Sources & Links
Official Adani Airports: Adani Airports official website
AAHL Investor Downloads & Annual Reports: AAHL Investor Downloads
Adani Airports business overview: Adani Group – Airports Business
FY26 AEL Results: Adani Enterprises FY26 Results
FY26 Airports Investor Presentation: AAHL FY26 Investor Presentation
Latest ₹9,825 crore institutional investment: Adani Airports – US$1 Billion Equity Raise
CRISIL AA-/Stable rating: CRISIL – Adani Airport Holdings Rating Rationale
Unlisted company status: Adani Airport Holdings – Corporate Information
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
Disclaimer: This report is for research and informational purposes only and is not investment advice. AAHL is an unlisted company, so private-market valuations and transaction prices may differ materially from each other and from the latest institutional valuation. Investors should verify the exact security, shareholder rights, transfer restrictions, financial statements and transaction terms before investing.
