
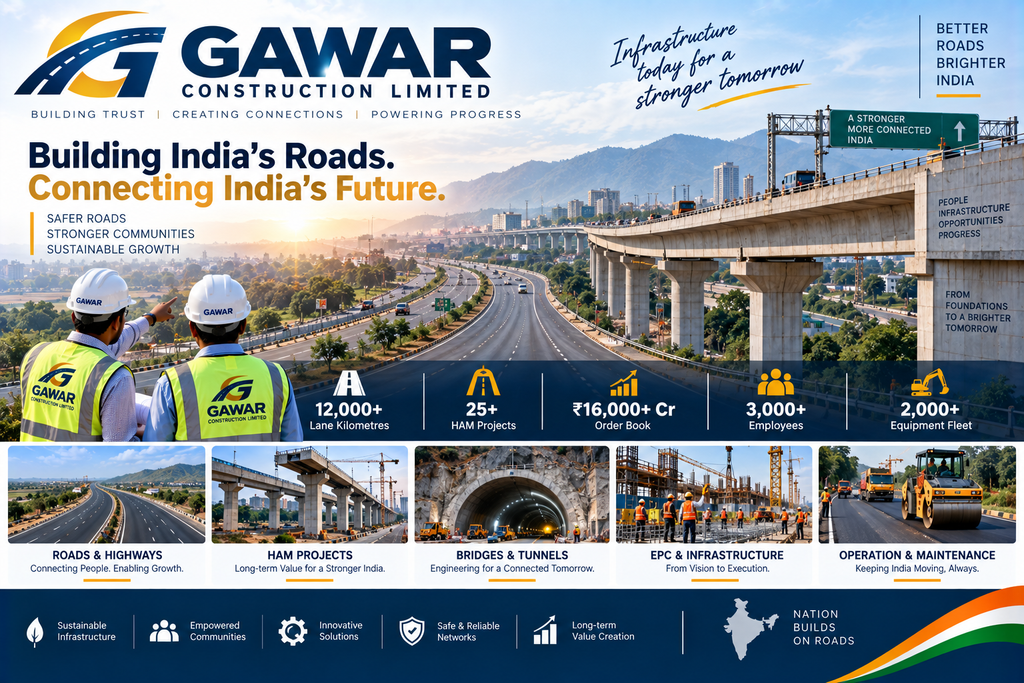
Company: Gawar Construction Limited
CIN: U70109HR2008PLC037773
Incorporated: 31 March 2008
Registered Office: DSS-378, Sector 16–17, Hisar, Haryana – 125005
Status: Unlisted Public Company
Paid-up Capital: ~₹14.69 crore
Sector: Infrastructure / Roads & Highways / Construction
Core Business: EPC, HAM road projects, highways, bridges, tunnels and infrastructure development
Sponsor of: Capital Infra Trust
Official Website: Gawar Construction Limited
1. Company Overview
Gawar Construction Limited (GCL) is an Indian infrastructure and construction company focused primarily on roads, highways, bridges, tunnels and other large civil-infrastructure projects.
The business was established in 1997 as a partnership firm and was subsequently reconstituted as a limited company in 2008. According to the company’s website, Gawar has contributed more than 12,000 lane kilometres to India’s infrastructure network and has executed projects for government and government-linked agencies across India.
The company has developed a particularly strong presence in the Hybrid Annuity Model (HAM) road-construction segment.
Gawar is also the sponsor of Capital Infra Trust, a listed infrastructure investment trust that owns operational highway assets developed by Gawar and other acquired assets.
2. Business Model
Gawar’s business can broadly be divided into:
| Business Area | Description |
|---|---|
| Roads & Highways | Construction and development of national and state highways |
| HAM Projects | Development of highway projects under Hybrid Annuity Model |
| Bridges & Flyovers | Large civil structures and elevated infrastructure |
| Tunnels | Complex road and tunnel construction |
| EPC | Engineering, procurement and construction |
| O&M | Operation and maintenance of completed road assets |
| Infrastructure Development | Development and investment through project SPVs |
The company mainly works with government and semi-government counterparties including NHAI and other central/state infrastructure agencies.
3. Scale of Operations
Gawar’s current website highlights:
- 25+ HAM projects
- ₹16,000+ crore order book
- 12,000+ lane kilometres
- 3,000+ employees
- 2,000+ construction-equipment fleet
- Presence across India
The website also states that the company has received 12 early-completion bonuses over the past five years, reflecting its track record of completing certain projects ahead of schedule.
4. Order Book
Order-book visibility is one of the major characteristics of the company.
CRISIL reported:
₹16,618 crore order book as of 31 March 2025
compared with ₹17,670 crore a year earlier.
The company’s order book was equivalent to approximately 2.3x FY25 revenue, providing substantial revenue visibility.
The latest Capital Infra Trust investor presentation also reported approximately ₹14,197 crore of expected gross cash accruals and ₹37,142 million (~₹3,714 crore) of orders secured during FY25–26, with the order book referenced at approximately ₹14,197 crore as of 31 December 2025 in that presentation.
The difference between the company’s various reported order-book figures reflects different reporting dates and definitions, so the date attached to each figure is important.
5. FY25 Financial Performance
According to financial information compiled from company filings:
| ₹ Crore | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue from Operations | 6,957.57 | 7,286.90 | 7,353.72 |
| Other Income | 131.34 | 162.92 | 297.92 |
| Total Income | 7,088.91 | 7,449.82 | 7,651.64 |
| EBITDA / Operating Profit* | 933.1 | 960.7 | 813.9 |
| PAT | 652.5 | 783.8 | 1,821.4 |
| Net Worth | 3,556.3 | 4,335.9 | 6,157.4 |
*Operating-profit figures from financial databases may differ from rating-agency EBITDA definitions.
The FY25 numbers show relatively stable operating revenue but a significant increase in reported profit and net worth.
Important earnings point
The sharp FY25 PAT increase should not be interpreted simply as a recurring operating-profit jump.
Gawar transferred nine completed HAM projects to Capital Infra Trust in FY25 in exchange for approximately ₹1,649 crore worth of InvIT units. This transaction materially strengthened the company’s financial flexibility and affected its financial statements.
Therefore, FY25 PAT needs to be analysed alongside the company’s operating earnings and asset monetisation activity.
6. Financial Strength
CRISIL reaffirmed Gawar’s CRISIL AA/Stable rating in August 2025.
The rating agency reported:
- FY25 operating income: approximately ₹7,423 crore
- TOL/TNW: 0.19x
- Interest coverage: >24x
- Net cash accrual/debt: 5.9x
- Order book: ₹16,618 crore
- Operating margin: 11.9%
- Net gross current assets: approximately 145 days
CRISIL highlighted the company’s low reliance on debt and strong financial risk profile.
CARE had earlier assigned CARE AA; Stable / CARE A1+ ratings to Gawar’s bank facilities, with rated facilities of several thousand crore.
7. HAM Business Model
The Hybrid Annuity Model is particularly important to understanding Gawar.
Under HAM:
- The developer/concessionaire constructs the road.
- A portion of project cost is supported through government payments.
- The remaining investment is funded by the developer.
- The project generates long-term annuity payments after completion.
- Completed assets can subsequently be monetised or transferred to an InvIT.
This model allows Gawar to recycle capital from completed projects into new infrastructure opportunities.
8. Capital Infra Trust — Strategic Asset
Gawar established Capital Infra Trust, formerly National Infrastructure Trust, as an InvIT.
The Trust is sponsored by Gawar Construction and was registered with SEBI as an InvIT in March 2024.
Capital Infra Trust subsequently listed on NSE/BSE in January 2025.
This creates an important strategic relationship:
Gawar Construction → Develops Roads → Completes HAM Assets → Transfers/Monetises Assets → Recycles Capital → Builds New Projects
This asset-recycling model can potentially reduce the amount of capital Gawar needs to permanently lock into completed road projects.
9. Recent Capital Infra Trust Transaction
In August 2026, Capital Infra Trust approved the acquisition of six highway SPVs from Gawar Construction.
The six assets were:
- Gawar Bhiwani Highway Pvt Ltd
- Gawar Kangra Highways Pvt Ltd
- Gawar Pathankot Mandi Highway Pvt Ltd
- Gawar Udaipur Highway Pvt Ltd
- Gawar Waranga Highways Pvt Ltd
- Gawar Rudrapur Highway Pvt Ltd
The aggregate adjusted enterprise value was approximately ₹2,921.4 crore.
Capital Infra Trust also proposed raising up to approximately ₹2,675 crore and issuing up to 1.66 crore units to Gawar Construction at ₹75.25 per unit, subject to the relevant approvals.
This is strategically important because it provides another mechanism for Gawar to monetise completed/operational infrastructure assets.
10. Gawar’s Competitive Position
Gawar’s competitive advantages are primarily operational rather than technological.
Execution capability
The company has executed more than 12,000 lane kilometres and has a long history of completing large road projects.
Equipment base
The company’s website highlights a fleet of approximately 2,000 construction machines/equipment, supporting its ability to execute projects in-house.
Government relationships
A significant portion of its projects come from central and state government authorities.
CRISIL noted that more than 40% of the order book was from central government authorities as of March 2025.
Early completion
The company has received multiple early-completion bonuses, supporting its reputation for project execution.
11. Geographic Presence
Gawar has a pan-India operating footprint.
CRISIL reported that its order book at March 2025 was geographically diversified, although Maharashtra, Himachal Pradesh and Uttar Pradesh together represented approximately 76% of the order book.
The company has undertaken projects across numerous states and union territories.
12. Management
Key leadership includes:
- Rakesh Kumar — Founder & Executive Director
- Dr. Bant Singh Singla — Executive Director – Technical
- Ram Kishan — Whole-time Director
- Other board members/directors include Ravinder Kumar, Bhupinder Singh, Sumedha Kataria and others.
The company describes Rakesh Kumar as its founder and executive director, while Dr. Bant Singh Singla brings extensive technical and road-infrastructure experience, including previous experience associated with NHAI and Haryana road authorities.
13. Credit Rating
Gawar has a strong external credit profile.
CRISIL
CRISIL AA / Stable
CRISIL reaffirmed this rating in August 2025 on total rated bank facilities of approximately ₹4,125 crore.
CARE
CARE Ratings had assigned:
CARE AA; Stable
and
CARE A1+
to various long-term and short-term bank facilities.
The ratings reflect the company’s scale, execution track record, low leverage and financial flexibility from its HAM portfolio.
14. Unlisted Share Price
Unlike Capital Infra Trust, Gawar Construction Limited does not have a continuously traded exchange price.
The company’s equity is unlisted, so transaction prices in the private/unlisted market can vary materially depending on:
- Buyer/seller
- Transaction size
- Liquidity
- Shareholder restrictions
- Negotiated terms
- Corporate actions
- Valuation expectations
I would therefore not use Capital Infra Trust’s ₹75–₹77 listed unit price as Gawar Construction’s share price. They are separate securities.
For reference, Capital Infra Trust was trading around ₹77.20 on 21 September 2026.
15. Valuation Considerations
Because Gawar Construction is unlisted and has undergone substantial asset transfers to Capital Infra Trust, a simple P/E comparison can be misleading.
A better framework is:
1. Operating EPC business
Value the ongoing road/EPC construction business based on:
- Revenue
- EBITDA
- Order book
- Margins
- Working capital
- Execution capacity
2. HAM portfolio
Assess:
- Value of operational HAM assets
- Equity invested in SPVs
- Expected annuity cash flows
- Potential transfers to Capital Infra Trust
3. Capital Infra Trust stake
Gawar’s ownership in the listed InvIT represents an important financial asset.
Capital Infra Trust’s listed units were around ₹77.20 on 21 September 2026.
Gawar’s stake in Capital Infra Trust therefore needs to be considered separately when assessing the consolidated economic value of the Gawar group.
16. Major Growth Drivers
Infrastructure spending
India continues to invest heavily in highways, expressways, bridges and transportation infrastructure.
Large order book
The ₹16,000+ crore order-book scale provides substantial revenue visibility.
HAM asset recycling
Completed HAM assets can potentially be transferred to Capital Infra Trust, releasing capital for new projects.
Strong execution track record
The company has completed numerous large infrastructure projects and has received early-completion bonuses.
Diversification
Gawar has increasingly expanded beyond conventional road EPC into other infrastructure segments.
CRISIL specifically noted approximately ₹2,180 crore of non-road orders added during FY25.
17. Key Risks
Road-sector concentration
Despite some diversification, roads remain the dominant business.
CRISIL reported that more than 86% of orders were from the roads segment at March 2025.
Project concentration
The top 10 projects accounted for approximately 74% of the order book at March 2025.
This means delays in large projects can have a meaningful impact on execution.
Geographic concentration
Three states represented approximately 76% of the order book at March 2025.
Construction cyclicality
Infrastructure awards can fluctuate depending on government tendering, policy, elections, financing conditions and overall capex.
Working Capital
Net gross current assets increased to approximately 145 days in FY25 from around 90 days in FY24, according to CRISIL. The rating agency attributed the increase partly to receivables from Gawar’s own HAM projects.
HAM exposure
HAM projects require significant upfront capital and can tie up funds until completion/monetisation.
Asset-transfer dependence
The company’s financial flexibility is partly supported by monetisation/transfers of completed HAM assets. Any slowdown in asset monetisation could affect capital recycling.
18. Gawar vs Capital Infra Trust
| Parameter | Gawar Construction | Capital Infra Trust |
|---|---|---|
| Structure | Unlisted company | Listed InvIT |
| Core role | EPC / infrastructure developer | Owns infrastructure assets |
| Main assets | Construction projects + HAM SPVs | Operational highway assets |
| Revenue model | EPC + project development | Annuity/toll & distributions |
| Sponsor | — | Gawar Construction |
| Listed | No | Yes |
| NSE Symbol | — | CAPINVIT |
| Relationship | Sponsor / developer | Asset owner / monetisation platform |
The two entities should therefore be viewed as complementary parts of the infrastructure ecosystem, not as identical businesses.
19. Key Numbers at a Glance
| Parameter | Gawar Construction |
|---|---|
| Incorporated | 2008 |
| FY25 Revenue from Operations | ₹7,353.7 Cr |
| FY25 Total Income | ₹7,651.6 Cr |
| FY25 PAT | ₹1,821.4 Cr |
| FY25 Net Worth | ₹6,157 Cr |
| FY25 Order Book | ₹16,618 Cr |
| Order Book / Revenue | ~2.3x |
| Lane Km Executed | 12,000+ |
| HAM Projects | 25+ |
| Employees | 3,000+ |
| Equipment Fleet | 2,000+ |
| FY25 TOL/TNW | 0.19x |
| Credit Rating | CRISIL AA/Stable |
| Listed | No |
| InvIT Sponsor | Yes – Capital Infra Trust |
Financial data is sourced from company information and independent rating/financial databases; the FY25 PAT figure includes the effects of asset monetisation/InvIT-related transactions and should not be treated as a pure recurring EPC earnings figure.
20. UnlistedCart Takeaway
Gawar Construction is one of the more established unlisted infrastructure businesses in India’s road-construction ecosystem.
The key part of the story is not simply its ₹7,000+ crore revenue base.
The more important combination is:
Large EPC business + ₹16,000+ crore order book + HAM portfolio + Capital Infra Trust + asset-recycling model
The company has a demonstrated ability to execute large road projects and has maintained a strong credit profile, with CRISIL AA/Stable and low leverage.
Its relationship with Capital Infra Trust is particularly important. Gawar can develop infrastructure assets and subsequently transfer completed assets into the InvIT, potentially releasing capital that can be deployed into new projects.
The August 2026 transaction involving six additional highway SPVs worth approximately ₹2,921 crore of adjusted enterprise value demonstrates that this asset-recycling strategy remains active.
For an investor evaluating Gawar’s unlisted shares, the most important areas to examine are the latest share price, number of shares outstanding, value of Gawar’s Capital Infra Trust holding, HAM SPV investments, recurring EPC profitability, cash flows and the terms of any private transaction.
Important Disclaimer
Gawar Construction Limited is unlisted, and there is no continuous NSE/BSE price discovery for its equity shares.
Any unlisted share price should therefore be treated as an indicative negotiated market reference rather than a firm market price.
FY25 reported profitability was significantly influenced by the company’s asset-monetisation/InvIT transactions, so valuation should not rely solely on the headline FY25 P/E.
Investors should verify the latest audited financial statements, shareholding, HAM SPV valuations, Capital Infra Trust holdings, debt, contingent liabilities and transaction terms before investing.
This report is for information and research purposes only and should not be treated as a guaranteed return or a recommendation to buy or sell securities.
Useful Links
- Official company website: Gawar Construction Limited
- Company – About Us: Gawar About Us
- Investor Relations: Gawar Investor Relations
- CRISIL Rating Report: CRISIL – Gawar Construction Rating
- CARE Rating Report: CARE Ratings – Gawar Construction
- Capital Infra Trust: Capital Infra Trust
- Capital Infra Trust investor presentation: Capital Infra Trust – Investor Presentation
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
