
Environmental Engineering | Waste Management | Pollution-Control Equipment
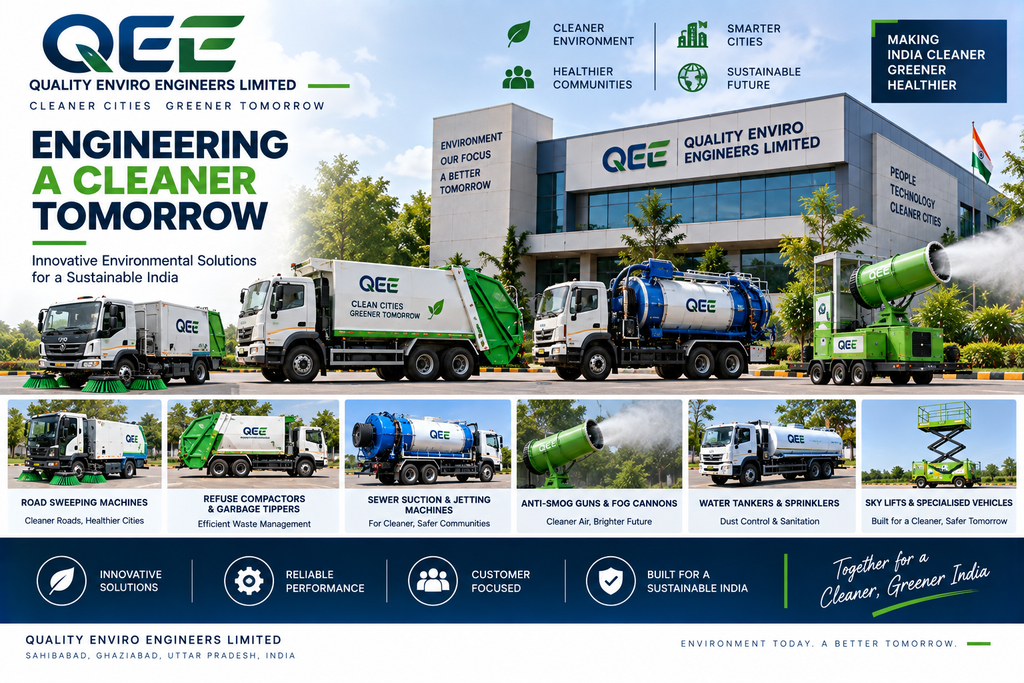
Quality Enviro Engineers Limited (QEEL) is an Indian manufacturer of environmental and municipal equipment used for solid-waste management, liquid-waste management, road cleaning, air-pollution control and sanitation infrastructure.
The company is headquartered in Sahibabad, Ghaziabad, Uttar Pradesh, and was incorporated on 6 May 2016. It was formerly known as Quality Enviro Engineers Private Limited and is currently an unlisted public company.
The company’s business is positioned around the growing requirement for municipal sanitation, mechanised waste collection, air-pollution-control equipment and environmental infrastructure across Indian cities.
Company Snapshot
| Particular | Details |
|---|---|
| Company | Quality Enviro Engineers Limited |
| Former Name | Quality Enviro Engineers Private Limited |
| CIN | U29190UP2016PLC082974 |
| Incorporated | 6 May 2016 |
| Registered Office | Sahibabad, Ghaziabad, Uttar Pradesh |
| Status | Unlisted Public Company |
| Authorised Capital | ₹18 Cr |
| Paid-up Capital | ~₹1.18 Cr |
| Face Value | ₹10 |
| Industry | Environmental / Industrial Machinery |
| Business | Environmental & municipal equipment manufacturing |
| Managing Director | Ashwani Srivastava |
| Website | Quality Enviro Engineers – Official Website |
The company’s corporate records show authorised capital of ₹18 crore and paid-up capital of approximately ₹1.18 crore.
What Does Quality Enviro Engineers Do?
QEEL manufactures specialised equipment designed to address environmental and municipal-infrastructure requirements.
Its product portfolio includes:
- Anti-smog guns
- Road-sweeping machines
- Sewer suction machines
- Sewer jetting machines
- Refuse compactors
- Dumper placers
- Garbage tippers
- Hopper tippers
- Water tankers
- Fog cannons
- Sprinklers
- Mobile sanitation equipment
- Sky lifts / hydraulic access platforms
- Other waste-handling equipment
The company’s own website lists dust bins, sewer suction machines, sky lifts, water tankers, anti-smog guns, road sweepers, dumper placers and garbage tippers among its major product categories.
Core Business Segments
1. Solid Waste Management
QEEL manufactures equipment used for collection, transportation and handling of municipal solid waste.
Products include:
- Garbage tippers
- Refuse compactors
- Dumper placers
- Hopper tippers
- Mobile bins
- Garbage collection vehicles
This business benefits from increasing mechanisation of municipal waste-management systems.
2. Liquid Waste & Sewer Management
The company manufactures:
- Sewer suction machines
- Sewer suction-cum-jetting machines
- Sewer jetting machines
- Desilting equipment
These machines are used by municipal corporations, infrastructure companies and sanitation contractors.
3. Air Pollution Control
One of QEEL’s more visible product categories is anti-smog and fog-control equipment.
The company manufactures:
- Anti-smog guns
- Fog cannons
- Water sprinklers
These products can be deployed around construction sites, roads, industrial areas and other locations where dust suppression is required.
4. Road Cleaning
QEEL manufactures mechanised road-sweeping machines for municipal and infrastructure applications.
The shift from manual to mechanised road cleaning creates a structural opportunity for specialised equipment manufacturers.
5. Specialised Vehicles & Equipment
The company has expanded into products such as:
- Fire-rescue vehicles
- Hopper tippers
- Hydraulic platforms
- Sky lifts
- Water tankers
This broadens the addressable market beyond traditional sanitation equipment.
FY25 Financial Performance
The latest audited FY25 data available through company-information and unlisted-market sources shows strong growth.
| ₹ Cr | FY22 | FY23 | FY24 | FY25 |
|---|---|---|---|---|
| Revenue | 44.53 | 49.88 | 40.22 | 51.52 |
| EBITDA | 2.19 | 4.67 | 4.96 | 5.97 |
| EBITDA Margin | 4.92% | 9.36% | 12.33% | 11.59% |
| PBT | 1.99 | 3.54 | 4.12 | 5.52 |
| PAT | 1.54 | 2.55 | 2.86 | 3.93 |
| EPS* | ₹61.60 | ₹30.00 | ₹33.65 | ₹33.33 |
*Historical EPS is affected by subsequent capital changes/bonus issue and should not be compared directly with post-bonus EPS.
The FY25 figures show revenue growth of approximately 28% YoY, while PAT increased approximately 37%.
FY26 Provisional Performance
The more interesting development is the company’s FY26 growth.
According to the September 2026 FY26 provisional update:
| ₹ Cr | FY25 | FY26P | Growth |
|---|---|---|---|
| Revenue | 51.52 | 62.99 | 22.3% |
| EBITDA | 6.41 | 7.84 | 22.3% |
| EBITDA Margin | ~12.4% | 12.45% | Stable |
| PAT | 3.93 | 5.05 | 28.5% |
FY26 revenue increased approximately 22.3%, while PAT increased approximately 28.5% according to the company’s reported/provisional operating update.
This is important because growth has continued despite the relatively small scale of the company.
Manufacturing Capacity
During FY26:
Production units increased to 204
from the previous year’s level.
The company’s stated manufacturing capacity is approximately:
320 units
This implies approximately:
116 units of spare capacity
or roughly 36% of stated capacity still available.
The FY26 update says manufacturing capacity increased approximately 8.5% YoY.
This creates potential operating leverage if the company can continue increasing order execution without proportionately increasing fixed costs.
Employee Expansion
Employee strength reportedly increased from:
84 → 156
during FY26.
That represents an increase of approximately:
86%
The sharp increase indicates that the company is investing ahead of expected business expansion.
Order Book & Pipeline
One of the most important FY26 developments is the company’s order pipeline.
Order Book
Approximately:
₹14+ Cr
Bidding Pipeline
Approximately:
₹40 Cr
This is significant compared with FY26 revenue of approximately ₹63 Cr.
The FY26 update indicates that the company executed several large projects, including:
- 7 road sweepers worth approximately ₹11 Cr for Dhanbad Municipal Corporation
- Solar-panel batteries/equipment worth approximately ₹7 Cr
- Fog cannon and desilting machinery worth approximately ₹5.7 Cr
- Installation/commissioning worth approximately ₹5.3 Cr
- Anti-smog guns, jetting machines and sprinklers worth approximately ₹4.9 Cr
Current Order Pipeline
The reported ongoing projects include:
| Customer / Location | Project | Approx. Value |
|---|---|---|
| Delhi MCD | 12 Anti-Smog Guns | ₹7.20 Cr |
| Chandigarh | 5 Anti-Smog Guns | ₹2.10 Cr |
| Belagavi | 10 Hopper Tippers | ₹1.30 Cr |
These projects provide visibility for future revenue execution, although an order book should not be treated as guaranteed profit because margins and execution timelines can vary.
Geographic Expansion
The company’s operations have expanded beyond Uttar Pradesh.
The FY26 update identifies presence across:
- Delhi
- Chandigarh
- Haryana
- Uttar Pradesh
- Manipur
- Visakhapatnam
This geographical expansion is relevant because municipal and environmental-equipment demand is distributed across multiple states.
New Product Expansion
QEEL is also expanding beyond its traditional sanitation equipment.
Newer areas include:
Fire Rescue Vehicles
This could potentially increase average order values and diversify revenue.
Hopper Tippers
These are used for municipal solid-waste handling and transportation.
Renewable-Energy Equipment
The company executed approximately ₹7 Cr of solar-panel batteries and equipment for RCRS Innovations during FY26, marking an entry into the renewable-energy equipment space.
FY27 Management Outlook
Management has reportedly indicated a revenue-growth target of:
40–50% YoY for FY27
The guidance is attributed to:
- Stronger order pipeline
- Better fixed-cost absorption
- New manufacturing capacity
- New product categories
- Geographic expansion
A new plant is also being commissioned, according to the FY26 update.
This is management guidance, not a guaranteed outcome, and should be evaluated against actual quarterly execution.
Promoter & Shareholding
The FY25 shareholding data available from UnlistedZone shows:
| Shareholder | Holding |
|---|---|
| Ashwani Srivastava | 36.04% |
| Neha Srivastava | 36.04% |
| Others | 27.92% |
| Total | 100% |
The founders/promoters therefore collectively hold approximately:
72.08%
The remaining shares are held by other shareholders.
Capital Raises
QEEL has raised capital through preferential allotments.
Notable transactions include:
| Date | Amount | Price / Share |
|---|---|---|
| Dec 2020 | ₹0.20 Cr | ₹10 |
| Dec 2022 | ₹0.60 Cr | ₹10 |
| Apr 2024 | ₹0.77 Cr | ₹82.50 |
| May 2024 | ₹13 Cr | ₹551.20 |
The May 2024 preferential issue was at ₹551.20 per share, consisting of ₹10 face value plus ₹541.20 securities premium.
Important 2026 Bonus Issue
A major corporate-action development is the proposed:
10:1 Bonus Issue
An EGM was scheduled for 22 August 2026 in relation to a 10:1 bonus issue.
This is extremely important when comparing historical share prices.
For example, a pre-bonus price of ₹1,200 cannot simply be compared with a post-bonus price without adjusting for the additional shares.
Illustrative adjustment
If the ratio is 10 bonus shares for every 1 existing share, then:
1 existing share → 11 shares
and, theoretically, the per-share price adjusts downward by approximately the same factor, all else equal.
Therefore, investors should always verify whether an unlisted-market quote is pre- or post-bonus adjusted.
Current Indicative Unlisted Price
There is a significant discrepancy among unlisted-share websites.
One September 2026 source displays:
₹1,200/share
as of 12 September 2026.
Another source shows approximately:
₹316.80/share
as of 10 September 2026.
This large difference appears to be associated with differences in data methodology and potentially the treatment of the company’s 2026 bonus issue.
Therefore:
Do not use ₹1,200 and ₹316.80 as directly comparable prices.
The actual transaction price should be confirmed with the intermediary and, critically, whether the quote is adjusted for the 10:1 bonus.
Valuation
Using FY26 provisional PAT of approximately:
₹5.05 Cr
and FY25/pre-bonus share data creates a valuation problem because of the 2026 bonus issue.
Therefore, the correct valuation approach is:
Post-bonus shares outstanding
↓
Post-bonus EPS
↓
Post-bonus market price
↓
Adjusted P/E
rather than applying the old FY25 EPS of ₹33.33 to a post-bonus share price.
This is particularly important in Quality Enviro because the company’s capital structure has changed materially through preferential allotments and the proposed bonus issue.
Business Opportunity
QEEL operates in several structural-growth areas.
Urbanisation
Growing cities require increasingly mechanised municipal services.
Swachh Bharat / Municipal Spending
Government and municipal expenditure on sanitation, waste management and urban cleanliness creates demand for specialised equipment.
Air Pollution
Anti-smog guns, fog cannons and dust-suppression equipment have become relevant in major Indian cities.
Mechanisation
Municipal bodies are increasingly moving from labour-intensive processes toward mechanised waste collection and road cleaning.
Environmental Compliance
Industrial and municipal entities increasingly require equipment for pollution and waste-management compliance.
These trends can expand the company’s addressable market.
Key Positives
1. Strong recent growth
FY26 provisional revenue increased approximately 22% and PAT approximately 29%.
2. Growing product portfolio
The company is expanding beyond conventional sanitation machinery into fire rescue vehicles, hopper tippers and renewable-energy equipment.
3. Order pipeline
₹14+ Cr order book plus approximately ₹40 Cr bidding pipeline provides potential revenue visibility.
4. Spare capacity
Reported capacity of 320 units versus production of 204 units leaves room for additional growth before full utilisation.
5. Government/municipal opportunity
The company’s products directly address sanitation, waste-management and air-pollution requirements.
6. Promoter ownership
Promoters collectively hold approximately 72% based on FY25 shareholding data.
Key Risks
1. Small company scale
Revenue of approximately ₹63 Cr means the company remains relatively small compared with established industrial-equipment manufacturers.
2. Government/municipal dependence
A meaningful portion of the business depends on government bodies, municipal corporations and project-based orders.
Order timing can therefore be unpredictable.
3. Working-capital requirements
Equipment businesses can require substantial working capital because of:
- Inventory
- Receivables
- Project execution
- Government payment cycles
4. Execution risk
Management’s FY27 40–50% growth target requires substantially higher execution than the current scale.
5. Valuation uncertainty
The large difference between unlisted-market price references makes valuation particularly difficult.
6. Bonus-adjustment risk
Investors can easily misinterpret historical EPS and price data if the 10:1 bonus is not incorporated into calculations.
7. IPO uncertainty
The company is currently unlisted. An IPO should not be assumed unless a formal filing and timetable are announced.
What Investors Should Track
For Quality Enviro Engineers, the most important metrics going forward are:
- FY27 revenue growth
- EBITDA margin
- Order-book conversion
- Government/municipal receivable days
- Working-capital requirement
- New plant commissioning
- Capacity utilisation
- Performance of new products
- Debt growth
- Any formal IPO filing
Investment Framework
Quality Enviro is best understood as a:
Small-cap environmental-equipment growth story
rather than simply a traditional waste-management company.
The potential growth equation is:
Municipal spending
Environmental regulation
Air-pollution-control demand
Product diversification
Manufacturing capacity
Geographic expansion
=
Potential operating growth
But the valuation must be adjusted for the company’s small current revenue base, working-capital requirements and the significant 2026 capital-structure change.
UnlistedCart Takeaway
Quality Enviro Engineers is an emerging environmental-equipment manufacturer with exposure to India’s growing sanitation, waste-management and pollution-control requirements.
The company has shown strong recent growth. FY25 revenue was approximately ₹51.5 Cr, while FY26 provisional revenue increased to approximately ₹63 Cr. FY26 provisional EBITDA was approximately ₹7.84 Cr and PAT approximately ₹5.05 Cr.
The more interesting part of the story is the combination of spare manufacturing capacity, a ₹14+ Cr order book, approximately ₹40 Cr bidding pipeline, new product categories and expansion into multiple Indian states.
However, investors should be particularly careful with the valuation because different unlisted-market platforms currently show very different prices. The company’s 10:1 bonus issue also makes historical EPS and share-price comparisons potentially misleading unless everything is adjusted to the post-bonus capital structure.
The key variables to monitor are therefore FY27 execution, order-book conversion, margins, working capital and the eventual post-bonus share structure.
Disclaimer: Quality Enviro Engineers Limited is unlisted. Indicative OTC prices can differ materially between intermediaries and are not NSE/BSE quotes. The FY26 figures referenced above are provisional rather than audited. The proposed/announced bonus issue must be incorporated when comparing historical prices and EPS. Any future IPO should be considered only after a formal regulatory filing. Unlisted shares can have limited liquidity and significant valuation uncertainty. This report is for informational purposes only and is not investment advice.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
