
Unlisted Share Report | Pharmaceuticals & APIs
1. Company Overview
Penam Laboratories Limited is an Indian pharmaceutical manufacturing company incorporated on 7 August 1989 and registered with the RoC Delhi.
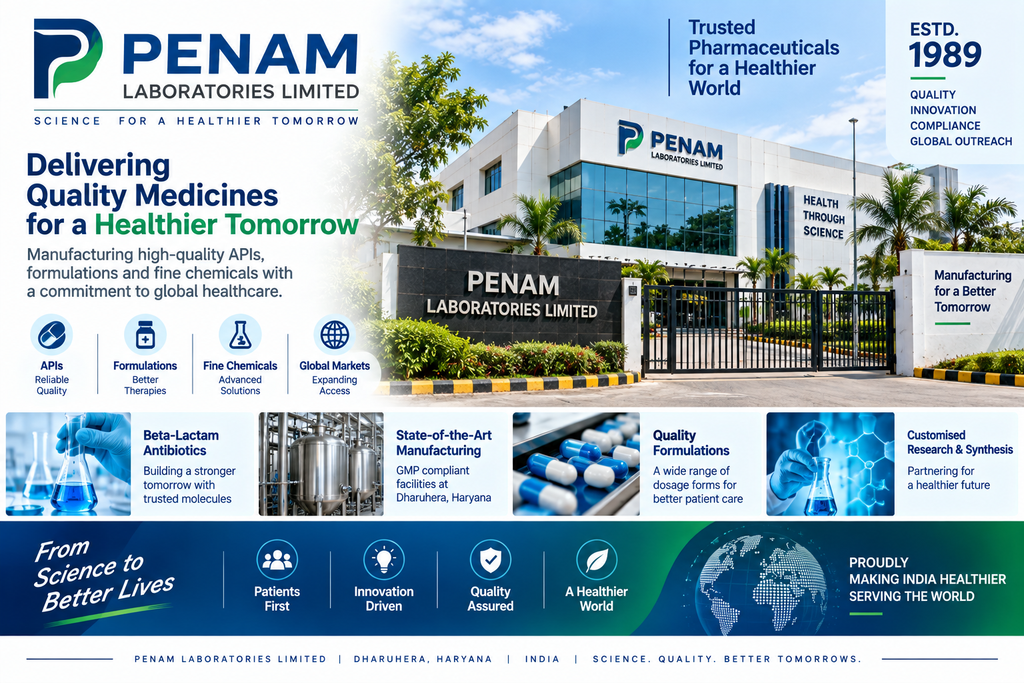
The company operates in pharmaceutical APIs, fine chemicals, pharmaceutical formulations and customised research/synthesis, with a particular focus on Beta-Lactam antibiotics.
Penam’s manufacturing facility is located at Dharuhera, Haryana, around 60 km from Delhi. The company describes itself as a producer of Beta-Lactam antibiotic bulk drugs and formulations.
| Particular | Details |
|---|---|
| Company | Penam Laboratories Limited |
| Incorporation | 7 August 1989 |
| CIN | U24231DL1989PLC037287 |
| ISIN | INE06AW01010 |
| Registered Office | New Delhi |
| Manufacturing | Dharuhera, Haryana |
| Face Value | ₹10 |
| Paid-up Capital | ₹5.17 Cr |
| Shares Outstanding | 51,67,157 |
| Status | Public Unlisted Company |
| Industry | Pharmaceuticals / APIs |
The company remains active and unlisted. FY25 financial statements were filed and the latest reported AGM was held in September 2025 according to current company-record databases.
2. Business Model
Penam operates across several parts of the pharmaceutical value chain.
Core businesses
1. Active Pharmaceutical Ingredients (APIs)
The company manufactures pharmaceutical bulk drugs, particularly Beta-Lactam antibiotics.
2. Pharmaceutical Formulations
Penam manufactures finished dosage forms including capsules and other formulations.
3. Fine Chemicals
The company has chemical manufacturing capabilities beyond traditional pharmaceutical formulations.
4. Customised Research & Synthesis
Penam also works on customised research and chemical synthesis for customers.
The company’s own website identifies its core competencies as APIs, fine chemicals, pharmaceutical formulations and CRM/customised synthesis.
3. Product Portfolio
Penam’s product portfolio includes Beta-Lactam antibiotics and other pharmaceutical/chemical products.
Some products listed by the company include:
- Oxacillin
- Ampicillin
- Cloxacillin Sodium
- Dicloxacillin
- Flucloxacillin Sodium
- Diosmin
- FCMIC
- DCMIC
- Beta-Lactam formulations
- Capsules
- Dry-syrup formulations
Its manufacturing capabilities also cover pharmaceutical intermediates and customised chemical synthesis.
The Central Drugs Standard Control Organisation’s historical list also identifies Penam’s Dharuhera facility for Bulk Drugs (API – Beta Lactam) and Beta Lactam capsule formulations.
4. Manufacturing Infrastructure
Penam’s principal manufacturing facility is at:
Dharuhera, Haryana
The company states that its manufacturing infrastructure includes:
- Glass-lined reactors
- SS-316 reactors
- More than 150,000 litres of reactor capacity
- Approximately 1,250 tonnes/year API & intermediate capacity
- Dedicated formulation facility
- Around 360 million capsules/year formulation capacity
- Low-temperature synthesis capability down to approximately -85°C
- High-temperature synthesis capability up to approximately +300°C
- Large-scale chlorination capability
The company also identifies its facility as WHO-GMP, and states that it has a government-recognised R&D centre and Star Export House recognition.
5. FY25 Financial Performance
FY25 vs FY24
₹ Crore
| Particular | FY24 | FY25 | Change |
|---|---|---|---|
| Revenue from Operations | ₹531.83 Cr | ₹386.78 Cr | -27.3% |
| Other Income | ₹20.97 Cr | ₹20.85 Cr | -0.6% |
| Total Income | ₹552.80 Cr | ₹407.63 Cr | -26.3% |
| PBT | ₹73.11 Cr | ₹52.61 Cr | -28.1% |
| PAT | ₹53.70 Cr | ₹39.62 Cr | -26.2% |
| EPS | ₹103.75 | ₹76.71 | -26.0% |
FY25 revenue declined significantly from FY24, with revenue from operations falling from ₹531.83 Cr to ₹386.78 Cr. PAT also declined from ₹53.70 Cr to ₹39.62 Cr.
However, the company remained profitable with a 10.25% net profit ratio in FY25.
6. Balance Sheet
FY25
| Particular | FY25 |
|---|---|
| Total Assets | ₹558.36 Cr |
| Equity Share Capital | ₹5.17 Cr |
| Other Equity | ₹491.05 Cr |
| Net Worth | ~₹496.22 Cr |
| Cash & Cash Equivalents | ₹71.38 Cr |
| Bank Balances | ₹194.10 Cr |
| Investments | ₹19.08 Cr |
| Trade Receivables | ₹94.39 Cr |
| Inventory | ₹52.87 Cr |
| Trade Payables | ~₹45.44 Cr |
| Debt/Equity | 0.003x |
One of the notable features of Penam’s balance sheet is its very low financial leverage.
The reported debt-equity ratio was only 0.003x in FY25.
The company also had substantial cash and bank balances.
7. Cash Flow Analysis
Cash flow requires a closer look.
FY25:
Operating Cash Flow: -₹10.53 Cr
compared with:
FY24: -₹51.66 Cr
So operating cash flow improved substantially year-on-year, but remained negative after tax payments.
The company generated ₹11.41 Cr of investing cash flow, helped primarily by interest income.
Interest income alone was approximately ₹16.91 Cr during FY25.
Key observation
Penam’s FY25 profitability was strong, but core operating cash generation was weaker than reported accounting profit.
This is an important factor to monitor.
8. Key Financial Ratios
| Ratio | FY24 | FY25 |
|---|---|---|
| Current Ratio | 3.78x | 7.72x |
| Debt/Equity | 0.006x | 0.003x |
| ROE | 11.76% | 7.99% |
| Inventory Turnover | 5.50x | 5.16x |
| Receivables Turnover | 3.34x | 2.99x |
| Net Profit Margin | 10.08% | 10.25% |
| ROCE | 15.92% | 10.58% |
| Return on Investments | 22.13% | 60.27% |
The company has a very strong liquidity position and negligible debt, but returns on equity and capital employed declined in FY25 because of lower profitability.
9. Shareholding Pattern
As of 31 March 2025:
| Category | Shares | Holding |
|---|---|---|
| Promoters | 49,26,356 | 95.34% |
| Public | 2,40,801 | 4.66% |
| Total | 51,67,157 | 100% |
The promoter holding of approximately 95.34% makes Penam a highly closely held company.
This is relevant for unlisted investors because the limited public float can contribute to lower liquidity and wider differences between buyer and seller quotes.
10. Management
Current/director records include:
- Surender Kumar Ajmani – Managing Director
- Paras Nath Pandey – Managing Director
- Ashish Ajmani – Whole-Time Director
- Vikas Pandey – Whole-Time Director
- Raj Rani Ajmani – Director
- Abha Pandey – Director
- Shweta Jain – Director
- Pankaj Jain – Director
The current board information is based on recent unlisted-market/company records; older MCA databases may show different historical director compositions.
11. Unlisted Share Price
Penam Laboratories does not trade on NSE or BSE.
Current private-market references show significant variation:
- ₹890 — WWIPL reference dated 17 September 2026
- ₹790–₹800 — another unlisted-market reference in September 2026
- ₹952.10 — Planify reference dated 28 May 2026
- Moneycontrol recently showed approximately ₹934.75
These should be treated as indicative OTC/private-market quotes, not exchange prices.
Indicative valuation
At ₹890/share:
51,67,157 shares × ₹890 ≈ ₹460 Cr
At ₹800/share:
Implied equity value ≈ ₹413 Cr
At ₹950/share:
Implied equity value ≈ ₹491 Cr
Therefore, a reasonable current reference range from available market sources is approximately:
₹790–₹950 per share
with substantial variation depending on the intermediary and transaction availability.
12. Valuation
Using FY25 EPS of ₹76.71:
| Share Price | Approx. FY25 P/E |
|---|---|
| ₹790 | ~10.3x |
| ₹890 | ~11.6x |
| ₹950 | ~12.4x |
At ₹890, the implied market capitalisation is approximately ₹460 Cr, while FY25 book value is around ₹960/share based on the reported equity base.
This means the stock is trading at approximately 0.93x book value at ₹890.
The available unlisted-market data also shows a P/B ratio close to 1x.
13. IPO / Listing Status
Penam Laboratories is currently an unlisted public company.
Moneycontrol currently shows:
DRHP Status: No
and there is no confirmed NSE/BSE IPO timetable identified in the sources reviewed.
Therefore, any future IPO should be treated as uncertain rather than assumed in the investment thesis.
14. Growth Drivers
1. Established API business
Penam has decades of experience in pharmaceutical APIs and Beta-Lactam antibiotics.
2. Integrated capabilities
The combination of API + intermediates + formulations + customised synthesis gives the company multiple points of participation in the pharmaceutical value chain.
3. Manufacturing capacity
The Dharuhera facility has significant reactor and capsule manufacturing capacity, providing scope to service domestic and export customers.
4. Export potential
Penam identifies itself as a recognised Star Export House, giving international pharmaceutical markets strategic importance.
5. Strong balance sheet
The company had negligible debt and substantial cash/bank balances at FY25 year-end.
6. Potential earnings normalisation
FY25 revenue and profit were materially below FY24.
If the business returns closer to its earlier revenue/profit levels, earnings growth could become an important valuation driver.
15. Key Risks
⚠️ Revenue decline
FY25 revenue from operations fell approximately 27% year-on-year.
⚠️ Negative operating cash flow
Despite ₹39.62 Cr PAT, operating cash flow was negative ₹10.53 Cr in FY25.
⚠️ High promoter concentration
Promoters control approximately 95.34% of the company, leaving only around 4.66% with public shareholders.
⚠️ Unlisted liquidity
There is no continuous exchange market. Exit depends on finding a private buyer, and different intermediaries can quote materially different prices.
⚠️ Product concentration
The company’s historical strength in Beta-Lactam APIs and formulations creates exposure to competition, regulatory requirements, pricing pressure and changes in demand.
⚠️ Regulatory risk
Pharmaceutical API and formulation manufacturers remain subject to stringent quality, manufacturing and regulatory requirements.
⚠️ Earnings dependence on non-operating income
FY25 other income was approximately ₹20.85 Cr, including substantial interest income. Therefore, investors should distinguish between operating pharmaceutical profitability and returns generated from financial assets.
16. Investment Snapshot
| Parameter | Penam Laboratories |
|---|---|
| Sector | Pharmaceuticals / APIs |
| Incorporated | 1989 |
| Manufacturing | Dharuhera, Haryana |
| FY25 Revenue | ₹386.8 Cr |
| FY25 PAT | ₹39.6 Cr |
| FY25 EPS | ₹76.71 |
| Net Worth | ~₹496 Cr |
| Debt/Equity | 0.003x |
| Promoter Holding | 95.34% |
| FY25 OCF | -₹10.5 Cr |
| Indicative OTC Price | ~₹790–₹950 |
| Implied Market Cap | ~₹408–491 Cr |
| FY25 P/E at ₹890 | ~11.6x |
| Book Value | ~₹960/share |
| NSE/BSE Listed | No |
| DRHP | No confirmed filing |
17. UnlistedCart Takeaway
Penam Laboratories is a closely held pharmaceutical/API manufacturer with a long operating history, established Beta-Lactam capabilities, manufacturing infrastructure and a strong balance sheet.
The key attraction in the numbers is the combination of:
₹39.6 Cr FY25 PAT + ~₹496 Cr net worth + negligible debt + substantial cash/bank balances.
However, FY25 also showed a sharp decline in revenue and profit, while operating cash flow remained negative. A meaningful part of total income also came from interest and investment-related income.
At approximately ₹790–₹950 per share, the implied valuation is roughly ₹408–491 Cr, equivalent to around 10–12.5x FY25 earnings.
The key variables to monitor going forward are:
Revenue recovery → operating margins → cash-flow conversion → API/formulation capacity utilisation → export growth.
For an unlisted investor, the limited float and liquidity should also be considered alongside the financial valuation.
Sources & Further Reading
Penam Laboratories – Official Website
Penam Laboratories FY2024-25 Financials & Annual Report Repository
WWIPL – Penam Laboratories Financials
Planify – Penam Laboratories Research
Moneycontrol – Penam Laboratories Unlisted Shares
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
Disclaimer: This report is for informational and research purposes only. Unlisted-share prices are indicative private-market references and are not exchange prices. Actual transaction prices may differ depending on liquidity, lot size, seller availability and transaction terms. Past financial performance does not guarantee future results. Investors should conduct independent due diligence before making any investment decision.
