
Solar Cell Manufacturing | Unlisted / Pre-IPO Opportunity
CIN: U51109WB1978PLC031668
ISIN: INE467C01027
Face Value: ₹2
Registered Office: Kolkata, West Bengal
Industry: Renewable Energy / Solar Manufacturing
Status: Unlisted Public Company
1. Company Overview
Jupiter International Limited (JIL) is an Indian renewable-energy manufacturing company focused primarily on solar photovoltaic cell manufacturing.
The company was incorporated in 1978 and initially operated in other businesses, including IT peripherals under the Frontech brand. Jupiter entered solar-cell manufacturing in 2009, starting with a 30 MW facility in Baddi, Himachal Pradesh.
Today, its core business is solar-cell manufacturing, with expansion into TOPCon technology, solar modules, EPC, solar pumps, battery energy storage and integrated solar manufacturing.
Jupiter International – Official Website
2. Business Model
Jupiter operates primarily in the B2B solar manufacturing market, supplying photovoltaic cells to solar-module manufacturers.
Key business areas
| Segment | Description |
|---|---|
| Solar Cells | M10/M10R Mono-PERC and TOPCon cells |
| Solar Modules | Upcoming integrated manufacturing |
| Solar EPC | Rooftop and ground-mounted projects |
| Solar Pumps | Solar-powered agricultural pumping solutions |
| BESS | Battery Energy Storage Systems |
| O&M | Operations & maintenance |
| Engineering | Solar plant design and consulting |
The company’s official product portfolio includes solar cells, solar modules, rooftop solar, solar water pumps, on-grid/off-grid solutions, BESS, engineering and O&M services.
Jupiter International – Products & Solutions
3. Manufacturing Capacity
Jupiter’s Baddi operations historically had approximately 0.96 GW of Mono-PERC capacity as of June 2025, according to the company’s website.
However, the company has substantially expanded during 2026.
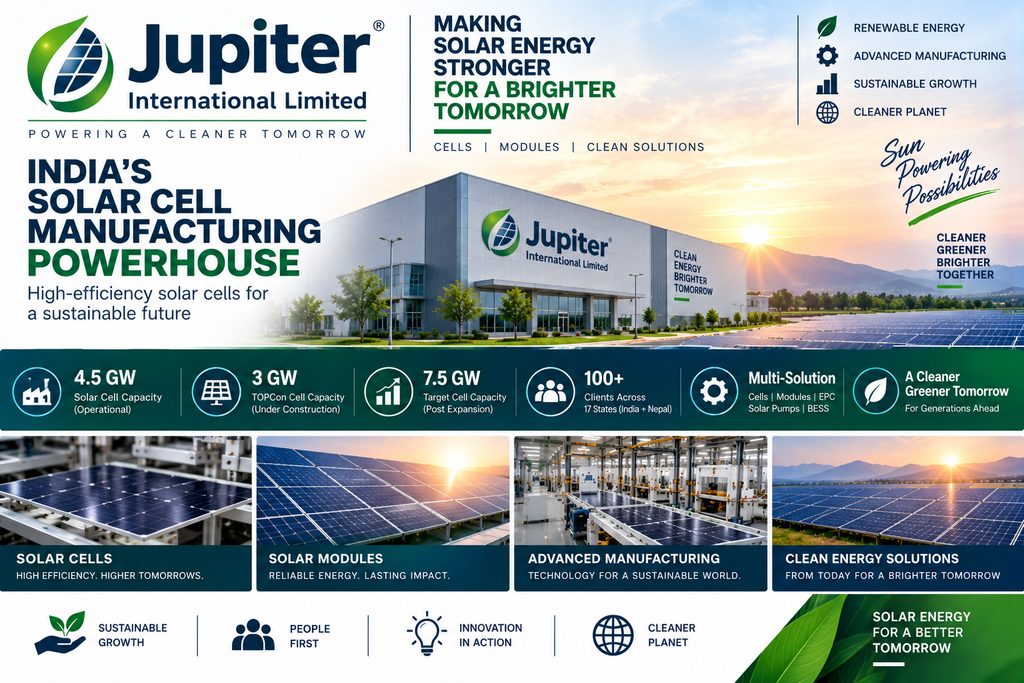
Management has indicated that total cell manufacturing capacity had reached approximately 4.5 GW by July 2026, with another 3 GW TOPCon facility in Nagpur under construction. The new facility is expected to take total capacity to around 7.5 GW once commissioned.
Jupiter also announced commencement of 1.25 GW TOPCon solar-cell production in June 2026.
Expansion roadmap
Existing / commissioned
- Mono-PERC manufacturing in Baddi
- New solar-cell manufacturing units
- 1.25 GW TOPCon capacity
Under development
- 3 GW TOPCon facility in Nagpur
- Integrated solar manufacturing
- Solar module manufacturing
- Planned 5 GW ingot & wafer facility
Management has discussed an overall expansion programme of approximately ₹3,000 Cr for the next phase, including the Nagpur expansion and related manufacturing infrastructure.
Jupiter International – Manufacturing Facilities
4. Financial Performance
Consolidated financials
₹ Crore
| Particulars | FY23 | FY24 | FY25 |
|---|---|---|---|
| Revenue from Operations | 430.4 | 577.6 | 555.9 |
| EBITDA / Operating Profit | 21.5 | 116.0 | 226.1 |
| EBITDA Margin | 5.0% | 20.1% | 40.7% |
| PBT | -43.8 | 55.7 | 166.9 |
| PAT | -35.8 | 41.4 | 123.3 |
| PAT Margin | -8.3% | 7.2% | 22.1% |
FY25 was a significant improvement in profitability despite revenue declining modestly from FY24. Operating profit increased sharply, while PAT rose almost 198% YoY.
The major point to watch is whether the exceptionally high FY25 operating margin can be maintained as Jupiter rapidly increases capacity.
5. Balance Sheet & Cash Flow
FY25 consolidated data indicates a substantial improvement in the balance sheet.
| Metric | FY25 |
|---|---|
| Current Ratio | 2.77x |
| Debt/Equity | 0.10x |
| ROE | 41.02% |
| ROCE | 33.66% |
| DSCR | 1.35x |
| Operating Cash Flow | ₹216.2 Cr |
The debt-equity ratio declined sharply from 2.19x in FY24 to 0.10x in FY25, helped by capital raising and deleveraging.
6. Institutional Funding
Jupiter has attracted institutional capital to fund its solar manufacturing expansion.
In April 2025, the company announced a ₹500 Cr investment from ValueQuest SCALE Fund and affiliates to support expansion toward 6.4 GW of solar-cell capacity and 2.4 GW of module capacity.
The company had also previously raised institutional capital from Edelweiss Alternatives.
The presence of institutional investors provides external capital for the expansion programme, but investors should still assess the eventual dilution and valuation at IPO.
7. Shareholding
Available FY25 shareholding data indicates the following major holders:
| Shareholder | Approx. Holding |
|---|---|
| Dayanidhi Management Pvt. Ltd. | 47.04% |
| Stuti Tie-Up Pvt. Ltd. | 24.82% |
| Alok Garodia | 6.29% |
| Sushila Garodia | 5.33% |
| Others | 16.52% |
The Garodia family remains closely associated with the company and its management.
8. Management
Raj Kumar Garodia
Chairman
Alok Garodia
Managing Director
Akash Garodia
Whole-time Director / President – New Initiatives
Devki Nandan Pandey
Executive Director
The company also has independent and nominee directors on its board.
Jupiter International – Company & Management
9. Major Growth Drivers
🇮🇳 1. India’s domestic solar manufacturing push
India is increasingly encouraging domestic manufacturing of solar cells and modules, reducing dependence on imported components.
Jupiter is positioned within this domestic manufacturing ecosystem.
☀️ 2. ALCM / domestic-cell requirement
The Approved List of Cell Manufacturers framework became particularly important from 1 June 2026, increasing the relevance of domestically manufactured cells for eligible ALMM-listed modules.
This creates a structural demand opportunity for approved domestic cell manufacturers.
⚙️ 3. TOPCon technology
Jupiter is moving beyond conventional Mono-PERC into TOPCon, a higher-efficiency solar-cell technology.
The company commenced TOPCon production with a reported 1.25 GW capacity in June 2026.
🏭 4. Large capacity expansion
The company’s manufacturing footprint is moving from sub-1 GW historical capacity toward several GW.
Management has indicated a potential ~7.5 GW cell capacity after the planned Nagpur expansion.
🔗 5. Vertical integration
The company is looking beyond cells toward:
- Modules
- Ingot/wafer manufacturing
- EPC
- Solar pumps
- Storage
Vertical integration could allow Jupiter to capture more value across the solar manufacturing chain.
10. Recent Business Developments
Jupiter announced a ₹108 Cr MSEDCL order for solar pumps in July 2026.
Separately, Vikram Solar disclosed a strategic procurement agreement with Jupiter for approximately 2 GW of ALMM-compliant TOPCon and Mono-PERC solar cells, with the agreement value stated at approximately ₹2,000 Cr.
This provides evidence of demand from established downstream module manufacturers.
11. IPO Status
Jupiter International is currently unlisted.
In March 2026, reports said the company had appointed IIFL, Axis Capital, Nomura and ICICI Securities as IPO advisers for a proposed approximately US$300 million IPO.
In July 2026, the company’s CEO indicated that Jupiter was targeting the first quarter of calendar 2027, subject to statutory approvals.
Important: As of September 2026, investors should not treat the proposed 2027 IPO as a confirmed listing date. The final size, price band, issue structure and timetable will depend on regulatory filings and approvals.
Jupiter International – Investor Relations
12. Indicative Unlisted Share Price
As of 18 September 2026, one unlisted-market source quoted Jupiter International at approximately ₹235/share. Another platform reported approximately ₹234.20/share on 15 September 2026.
A separate June 2026 research source had quoted approximately ₹232/share, showing that private-market prices can move meaningfully even over short periods.
Indicative valuation
At approximately ₹235/share and around 74.53 Cr shares, the implied equity value is roughly:
₹17,500 Cr
The FY25 PAT of ₹123.3 Cr implies a trailing valuation of roughly 142x earnings at this indicative price.
This is an OTC/private-market valuation, not an NSE/BSE market price. Unlisted shares have lower liquidity, wider spreads and less transparent price discovery than listed securities.
Jupiter International – Indicative Unlisted Share Information
13. Key Risks
1. Valuation risk
At around ₹230–₹240/share, the implied valuation is substantially higher than what FY25 earnings alone would justify. The valuation therefore depends heavily on future capacity expansion and earnings growth.
2. Execution risk
The business is attempting a very rapid increase in manufacturing capacity. Delays in commissioning can affect revenue and return on invested capital.
3. Solar-cycle risk
Solar-cell prices can be volatile because of changes in:
- Module prices
- Chinese supply
- Raw-material prices
- Technology
- Global oversupply
4. Technology risk
PERC technology is being increasingly replaced by higher-efficiency technologies such as TOPCon and eventually other next-generation technologies. Continuous capex and R&D will be required.
5. Capital requirement
The planned multi-GW expansion requires substantial capital. Future fundraising could lead to dilution.
6. IPO uncertainty
The company has publicly discussed a potential 2027 IPO, but the eventual timeline and valuation are not guaranteed.
7. Unlisted-share liquidity
Until listing, investors may face difficulty exiting at the desired price. OTC quotes should not be treated as equivalent to exchange-traded prices.
14. Investment Snapshot
| Parameter | Jupiter International |
|---|---|
| Sector | Solar Manufacturing |
| Core Business | Solar Cells |
| Current Status | Unlisted / Pre-IPO |
| Historical Capacity | 0.96 GW as of Jun-2025 |
| 2026 Reported Capacity | ~4.5 GW |
| Planned Capacity | ~7.5 GW cells |
| FY25 Revenue | ₹555.9 Cr |
| FY25 EBITDA | ₹226.1 Cr |
| FY25 PAT | ₹123.3 Cr |
| FY25 EBITDA Margin | 40.7% |
| FY25 Debt/Equity | 0.10x |
| Indicative Price | ~₹235 |
| Indicative Market Cap | ~₹17,500 Cr |
| Proposed IPO | Targeted Q1 CY2027, subject to approvals |
| Key Theme | India’s domestic solar manufacturing |
15. UnlistedCart Takeaway
Jupiter International is essentially a bet on India’s domestic solar-cell manufacturing build-out.
The company’s key attraction is the combination of existing manufacturing experience, rapid capacity expansion, TOPCon adoption, domestic-content policy support and a potential IPO.
However, the current unlisted valuation already reflects substantial future growth. The important questions for investors are therefore not just “Can Jupiter grow?”, but also:
Can the company execute the multi-GW expansion on time?
Can FY25’s unusually high margins be sustained?
What valuation will the IPO eventually command?
The company’s future earnings trajectory will largely depend on successful commissioning of new capacity, cell pricing, utilisation levels, technology transition and the pace of India’s solar manufacturing expansion.
Important sources
Official Jupiter International Website
Jupiter Investor Relations & Annual Reports
Jupiter Products & Solar Solutions
Jupiter Manufacturing Facilities
Jupiter Company & Management Information
Jupiter Unlisted Share Research – UnlistedZone
Disclaimer: This report is for informational and educational purposes only. Unlisted share prices are indicative OTC references and may differ between buyers and sellers. Unlisted investments carry liquidity, valuation, regulatory, execution and listing risks. Investors should independently verify company filings and conduct their own due diligence before making any investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
