
Renewable EPC | Solar IPP | Wind-Solar Hybrid | BESS | Green Energy
Company: Prozeal Green Energy Limited (PGEL)
CIN: U45206GJ2013PLC075904
Incorporated: 4 July 2013
Registered & Corporate Office: Ahmedabad, Gujarat
Business: Renewable Energy EPC & IPP
Status: Unlisted public company / IPO-bound
Promoters: Shobit Baijnath Rai, Manan Hitendrakumar Thakkar & Amaara Family Trust
Promoter-Managing Directors: Shobit Rai & Manan Thakkar
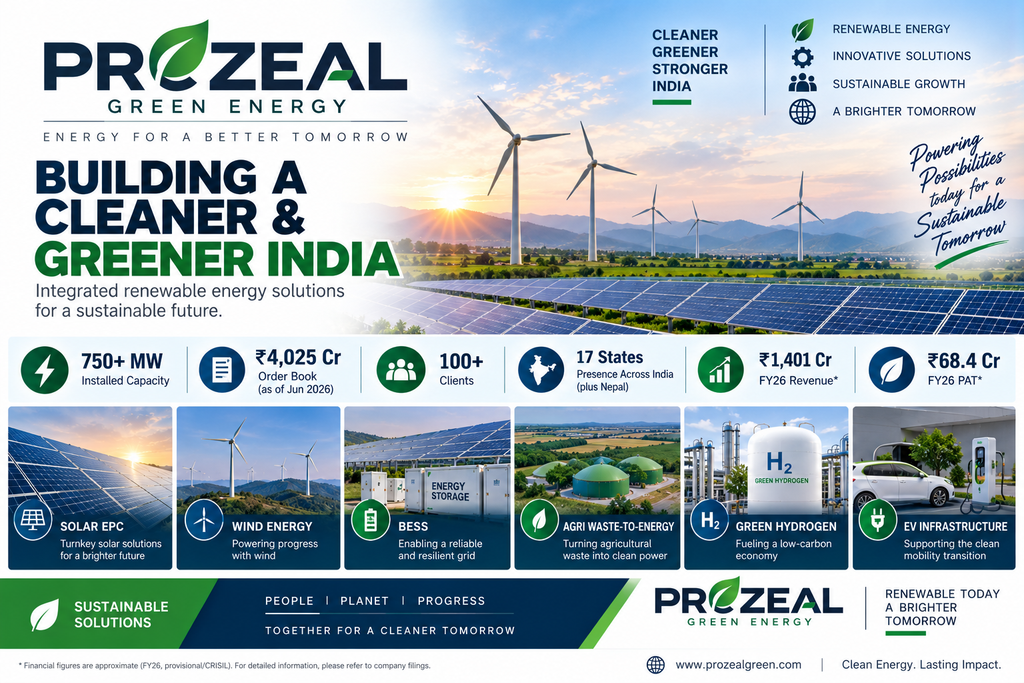
FY26 Operating Income: ₹1,401 Cr*
FY26 PAT: ₹68.4 Cr*
Order Book: ₹4,025 Cr as of June 2026
Installed Capacity: 750+ MW
Projects: 100+ clients / projects across 17 Indian states
IPO Proposed: ₹700 Cr
*CRISIL-adjusted/provisional figures; see financial section below.
1. Company Overview
Prozeal Green Energy is an Indian renewable-energy company founded in 2013 and headquartered in Ahmedabad.
The company initially built its business around solar EPC, particularly turnkey solar projects for commercial, industrial and government customers. It has subsequently expanded into:
- Solar EPC
- Renewable-energy IPP
- Wind power
- Wind-solar hybrid projects
- Battery Energy Storage Systems (BESS)
- Green hydrogen & ammonia
- EV infrastructure
- Renewable-energy O&M
The company says it has installed 750+ MW of renewable capacity and serves more than 100 commercial, industrial and government clients. It has executed projects across 17 Indian states and expanded into Nepal.
Prozeal Green Energy – Official Website
2. Business Model
Prozeal operates through two increasingly important businesses:
A. Renewable EPC
Under the EPC model, Prozeal handles the project lifecycle:
Land identification → permits → engineering → procurement → construction → commissioning → O&M
The company primarily focuses on solar projects for C&I customers and government entities.
B. Renewable IPP
Prozeal began building its own Independent Power Producer (IPP) portfolio in 2024.
Under this model, it develops renewable assets through special-purpose vehicles (SPVs), owns/operates the projects and generates recurring electricity revenue.
As of June 2026, projects totalling approximately 345 MW had been undertaken under various IPP SPVs.
This transition is strategically important because EPC generates project-based revenue, whereas IPP can create longer-duration recurring cash flows.
3. Services
Prozeal’s current service portfolio includes:
| Segment | Business |
|---|---|
| Solar EPC | Ground-mounted & rooftop solar |
| IPP | Renewable power generation |
| Wind | Captive & utility-scale projects |
| Hybrid | Wind + Solar |
| BESS | Battery energy storage |
| Green Hydrogen | Hydrogen & ammonia solutions |
| EV | EV charging infrastructure |
| O&M | Renewable asset operations |
The company describes itself as an end-to-end clean-energy solutions provider.
4. Track Record
According to the company’s investor information, Prozeal has:
- 750+ MW installed capacity
- 100+ clients
- Presence across 17 Indian states
- Nepal operations
- 250+ professionals
- Solar EPC, IPP, BESS, hybrid and green-hydrogen capabilities
The company states that its projects span commercial, industrial and government customers.
Its earlier DRHP disclosed 182 solar projects representing 783.98 MWp executed through September 30, 2024 across India and Nepal.
5. Order Book – Major Strength
One of the most important current developments is the company’s growing order book.
June 2026 Order Book
₹4,025 crore
The order book is expected to be executed over approximately 18–24 months.
According to CRISIL:
- ~50% relates to IPP projects
- Government entities account for approximately ₹870 crore
- The remainder includes projects for reputed corporates and C&I customers
- Internal work orders are included for development of IPP projects
This provides medium-term revenue visibility.
6. ONGC – ₹2,000 Crore Wind Project
A major recent catalyst came in June 2026.
ONGC awarded Prozeal a contract worth more than ₹2,000 crore for development of 250 MW captive wind power projects connected to the interstate transmission system.
The mandate includes:
- End-to-end project execution
- Wind project development
- Construction
- Operations & maintenance
The O&M contract has a 10-year tenure.
This is significant because it expands Prozeal beyond its historical solar-EPC concentration into a large-scale wind project.
7. Expansion into Uttar Pradesh
In June 2026, Prozeal announced a 60 MWp captive solar project in Uttar Pradesh.
The project further expands the company’s C&I renewable-energy footprint.
8. BESS & Hybrid Opportunity
Prozeal is also developing capabilities in:
Solar + Wind + Battery Storage
This is becoming increasingly important because standalone solar and wind generation can be intermittent.
Battery storage can potentially:
- Shift electricity generation
- Improve grid stability
- Reduce intermittency
- Support peak demand
- Increase renewable utilisation
- Improve C&I power reliability
The company’s current strategy explicitly includes BESS and wind-solar hybrid systems.
9. Green Hydrogen & Ammonia
Prozeal has also entered the broader emerging-energy ecosystem through green hydrogen and ammonia solutions.
This is still an emerging part of the business compared with its established solar EPC operations.
The opportunity is linked to India’s broader push towards:
- Green hydrogen
- Green ammonia
- Industrial decarbonisation
- Renewable-powered manufacturing
Investors should currently view this as a future growth vertical rather than the company’s primary earnings engine.
10. Nepal Expansion
Prozeal expanded into Nepal through a joint venture with Golyan Power.
The company has stated that it intends to develop renewable-energy projects in Nepal and is also exploring expansion into Europe.
The international opportunity is still relatively small compared with the Indian business.
11. FY26 Financial Performance
The latest CRISIL rating rationale provides FY26 provisional financial information.
₹ Crore
| Particular | FY25 | FY26 |
|---|---|---|
| Operating income | ₹1,041.86 Cr | ₹1,412.14 Cr |
| PAT | ₹112.63 Cr | ₹91.39 Cr |
| PAT margin | 10.81% | 6.47% |
| Adjusted debt / net worth | 0.21x | 0.75x |
| Interest coverage | 19.97x | 8.91x |
Revenue increased substantially, but profitability moderated because of higher material costs and increased working-capital requirements.
Important financial point
Another CRISIL rating rationale published in June 2026 reported operating income of ₹1,401.22 crore and PAT of ₹68.44 crore for FY26.
The difference reflects the use of CRISIL-adjusted figures and the provisional nature of FY26 reporting.
For consistency, investors should rely on the company’s final audited financial statements when available.
12. Historical Financial Performance
The DRHP restated financials provide a longer history.
| ₹ Crore | FY22 | FY23 | FY24 | FY25 |
|---|---|---|---|---|
| Revenue | 287.10 | 340.90 | 948.88 | ~937.0 |
| EBITDA | 11.50 | 32.40 | 124.70 | 137.40 |
| PAT | 1.00 | 21.50 | 92.20 | 103.00 |
| Debt | 3.30 | 62.60 | 77.30 | 82.50 |
The FY25 figures shown above are from restated/IPO financial disclosures and should not be mixed directly with CRISIL’s adjusted FY25/FY26 numbers.
The broader trend nevertheless shows a significant increase in revenue and profitability compared with FY22.
13. Profitability Challenge
While revenue has grown strongly, margins have recently come under pressure.
CRISIL reported that the operating margin declined by approximately 556 basis points to 7.48% in FY26, primarily because of:
- Higher material costs
- Intense competition
- Working-capital pressure
CRISIL expects margins could recover to approximately 9–10% over the near-to-medium term, although this remains an estimate rather than a guarantee.
14. Working Capital – Important Risk
This is one of the key areas investors should monitor.
Receivables increased to approximately 168 days as of March 2026, compared with 103 days a year earlier.
CRISIL expects gross current assets to remain around 200–220 days over the medium term.
This matters because EPC businesses can show strong accounting revenue while cash collection takes considerably longer.
Therefore:
Revenue growth ≠ immediate cash generation
For Prozeal, operating cash flow and receivables should be monitored closely.
15. Debt & Financial Risk
Prozeal’s external debt remains moderate compared with many infrastructure companies.
CRISIL reported:
Adjusted debt / adjusted net worth: 0.75x
as of March 2026.
However, total outside liabilities to adjusted net worth increased to 3.12x, partly because of higher customer advances and working-capital requirements.
Interest coverage remained comfortable at approximately 8.91x in CRISIL’s July 2026 assessment.
16. Promoters & Management
The company is promoted by:
Shobit Baijnath Rai
Co-Founder & Managing Director
Manan Hitendrakumar Thakkar
Co-Founder & Managing Director
The company’s board also includes independent/non-executive directors.
Current senior management includes:
- Jaimin Trivedi – CFO
- Krutarth Thakkar – Company Secretary
- Abhay Kumar Vishwakarma – COO
17. Shareholding
The DRHP identifies the principal promoters as:
- Shobit Baijnath Rai
- Manan Hitendrakumar Thakkar
- Amaara Family Trust
The DRHP also disclosed other selling shareholders in the proposed IPO, including AAR EM Ventures LLP and other existing investors.
The company’s current investor webpage has not yet published a fresh September 2026 shareholding pattern, so exact current percentages should be checked against the latest corporate filing rather than inferred from the old DRHP.
18. IPO – Major Development
Prozeal filed its DRHP with SEBI on 31 March 2025.
The original proposed IPO structure was:
| Component | Amount |
|---|---|
| Fresh Issue | ₹350 Cr |
| Offer for Sale | ₹350 Cr |
| Total Issue | ₹700 Cr |
| Potential Pre-IPO Placement | Up to ₹70 Cr |
The issue is proposed to be listed on NSE and BSE.
SEBI – Prozeal Green Energy DRHP Filing
19. IPO Use of Funds
The proposed fresh issue proceeds are intended for:
- Long-term working capital
- Investment in subsidiaries
- Debt repayment
- General corporate purposes
The original DRHP proposed approximately ₹250 crore for long-term working-capital requirements, with additional funds for subsidiary investment/debt repayment.
This is relevant because Prozeal’s growing order book is increasing its working-capital requirement.
20. IPO Status – September 2026
Prozeal has received SEBI approval/observations for its proposed IPO, according to September 2025 reporting, allowing the company to proceed toward a public issue.
However, as of 21 September 2026, I could not identify a confirmed:
- Price band
- IPO opening date
- IPO closing date
- Lot size
- Listing date
Therefore:
Current Status
IPO approved / IPO-bound — launch date awaited.
The company’s official website continues to maintain an IPO offer-document section.
Prozeal Green Energy – IPO Offer Documents
21. Unlisted Share Price
Prozeal’s equity is currently not traded on NSE/BSE.
I did not find a sufficiently reliable current September 2026 private-market quote that should be presented as an official market price.
Therefore, for an UnlistedCart report, the current OTC price should be separately verified before publishing.
This is particularly important because the IPO is already in the process and private-market prices can change sharply depending on expected IPO valuation and launch timing.
22. Competitive Position
Prozeal competes in India’s renewable EPC market with companies involved in:
- Solar EPC
- Renewable IPP
- Wind EPC
- Hybrid renewable projects
- BESS
The company’s historical positioning is particularly strong in C&I solar EPC.
The company was described in its DRHP as the fourth-largest solar EPC company in India by revenue from operations for FY24, based on the cited industry report.
Its newer IPP and wind activities are intended to diversify the business beyond conventional solar EPC.
23. Major Growth Drivers
1. ₹4,025 Cr Order Book
The order book provides visibility for the next 18–24 months.
2. IPP Expansion
The company is moving from pure EPC towards owning renewable assets.
3. ONGC Wind Project
The ₹2,000+ crore, 250 MW wind mandate provides a major new execution opportunity.
4. Wind-Solar Hybrid
Hybrid renewable projects can offer more consistent generation than standalone solar/wind.
5. BESS
Battery storage can become a major growth vertical as renewable penetration increases.
6. C&I Renewable Demand
Industrial and commercial companies are increasingly procuring renewable power to reduce energy costs and emissions.
7. Government Renewable Spending
Government-backed renewable programmes and PSUs provide potential EPC opportunities.
8. International Expansion
Nepal and potential European operations provide additional markets.
24. Key Risks
Working-Capital Risk
Receivables at 168 days are a major monitorable.
Margin Pressure
Operating margin declined materially in FY26 due to higher material costs and competition.
Project Execution
The company had commissioned only 4 of its 22 planned projects as of the June/July 2026 rating assessment. Delays could affect cash flows and returns.
IPP Counterparty Concentration
Approximately half of the order book consists of IPP projects, and CRISIL notes that the sponsor acts as the primary counterparty for these contracts.
This creates some concentration around the group’s ability to fund and execute those projects.
Renewable Resource Risk
Solar and wind generation depend on:
- Weather
- Irradiance
- Wind availability
- Grid evacuation
- Equipment performance
Regulatory Risk
Changes in:
- Open-access rules
- Electricity tariffs
- Renewable policies
- Grid regulations
- Land approvals
can affect project economics.
IPO Timing
The IPO provides a potential source of capital, but until the issue is launched and completed, funding assumptions should not be treated as certain.
25. What Investors Should Track
| Metric | Why it matters |
|---|---|
| Order book | Future revenue visibility |
| Order execution | Determines revenue conversion |
| EBITDA margin | EPC profitability |
| Receivable days | Cash-flow quality |
| Operating cash flow | Real cash generation |
| Debt / net worth | Financial leverage |
| Interest coverage | Debt-servicing capacity |
| IPP capacity | Recurring revenue potential |
| Project commissioning | Asset monetisation |
| BESS pipeline | Future growth |
| Wind project execution | Diversification |
| Customer mix | Concentration risk |
| IPO progress | Capital availability |
| Working capital | Funding requirement |
26. Business Model in One Framework
Solar EPC
↓
Large Order Book
↓
Project Execution
↓
Cash Generation
IPP Development
↓
Own Renewable Assets
↓
Long-Term Power Revenue
Wind + Solar Hybrid + BESS
↓
Integrated Renewable Platform
This transition from EPC-only → EPC + IPP + storage is central to the company’s long-term strategy.
27. Quick Snapshot
| Parameter | Prozeal Green Energy |
|---|---|
| Incorporated | 2013 |
| Headquarters | Ahmedabad |
| Promoters | Shobit Rai, Manan Thakkar, Amaara Family Trust |
| Business | Renewable EPC + IPP |
| Installed capacity | 750+ MW |
| Clients | 100+ |
| States | 17 |
| June-26 Order Book | ₹4,025 Cr |
| FY26 Operating Income* | ₹1,401 Cr |
| FY26 PAT* | ₹68–91 Cr |
| FY26 Operating Margin | 7.48% |
| IPP projects | 345 MW |
| ONGC project | 250 MW / ₹2,000+ Cr |
| IPO size | ₹700 Cr |
| Fresh Issue | ₹350 Cr |
| OFS | ₹350 Cr |
| IPO Status | SEBI-approved / launch awaited |
| NSE/BSE | Proposed |
| Current Equity Status | Unlisted |
*FY26 figures vary slightly by reporting basis in CRISIL’s June/July 2026 rating rationales; final audited figures should be used for valuation.
28. UnlistedCart Takeaway
Prozeal Green Energy is evolving from a solar EPC company into a broader renewable-energy platform.
The most interesting part of the story is the transition:
Solar EPC → IPP → Wind → Hybrid → BESS → Green Hydrogen
The ₹4,025 crore order book provides meaningful medium-term revenue visibility, while the ₹2,000+ crore ONGC wind project adds a major new reference project and expands the company’s exposure beyond solar.
The financial profile, however, needs careful monitoring. FY26 revenue continued to grow, but operating margins declined and receivable days increased substantially. This means cash conversion and working-capital management are just as important as headline revenue growth.
The proposed ₹700 crore IPO is another important potential catalyst, comprising ₹350 crore fresh issue and ₹350 crore OFS. The fresh capital is particularly relevant because the company’s expanding order book and IPP portfolio require working capital and investment.
Key Theme
₹4,025 Cr Order Book + Solar EPC + 345 MW IPP Pipeline + ₹2,000 Cr ONGC Wind Project + BESS + Upcoming ₹700 Cr IPO
Official & Research Links
Prozeal Green Energy – Official Website
Prozeal Green Energy – Investor Information
Prozeal Green Energy – IPO Offer Documents
SEBI – Prozeal Green Energy DRHP Filing
Prozeal Green Energy – Company Overview
CRISIL – July 2026 Rating Rationale
Prozeal Green Energy – ONGC ₹2,000 Cr Wind Project
BSE – Prozeal Green Energy DRHP
Disclaimer
This report is prepared for informational and research purposes only and should not be considered investment advice, a recommendation, or an offer to buy or sell securities. Prozeal Green Energy’s equity remains unlisted. Private-market transactions can have limited liquidity and uncertain price discovery. IPO terms, price band, dates and final issue structure may change. FY26 figures should be verified against the company’s final audited financial statements. Investors should independently review the latest DRHP/RHP, financial statements, credit-rating reports and regulatory filings before making an investment decision.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
