
Company: Madbow Ventures Limited
Former Name: Madbow Ventures Private Limited / Madbow Fashion Private Limited
CIN: U51909HR2017PLC069490
ISIN: INE0JKD01022
Incorporated: 13 June 2017
Business Origin: 2016
Registered Office: DLF Phase-II, Gurugram, Haryana
Status: Active Unlisted Public Company
Industry: Fashion, E-commerce & D2C Retail
Face Value: Current unlisted-market sources report ₹1 per share
Current Indicative Price: ~₹29.90–₹35/share
Latest publicly accessible audited financial data verified: FY2020-21
Official Website: Madbow Ventures
Executive Summary
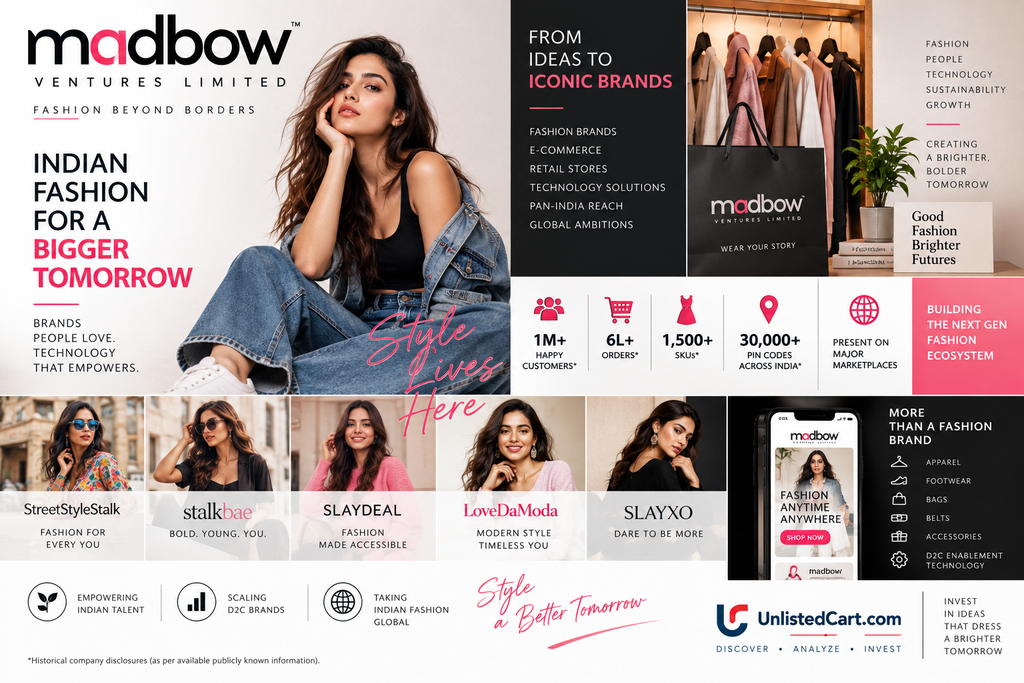
Madbow Ventures Limited is an Indian fashion and lifestyle e-commerce company that started with a digital-first model focused on women’s fashion and subsequently expanded toward a broader D2C fashion and retail-tech ecosystem.
The business has historically operated multiple fashion brands including StreetStyleStalk, StalkBae, SlayDeal, LoveDaModa and SlayXO, targeting different customer segments across western wear, footwear, lingerie and lifestyle products. Industry reports from 2021-22 also described plans to expand into ethnic wear, kids’ fashion, cosmetics and general merchandise.
More recently, Madbow’s public company profile describes the business as extending beyond fashion retail into D2C technology and e-commerce enablement, including online-store creation, landing pages, payments, logistics, CRM, marketplace payments, vendor payments, warehouse management and other operational tools for brands.
The investment case is therefore potentially more interesting than a simple fashion e-commerce company:
Fashion brands + D2C commerce + technology + operational infrastructure
However, investors need to be very careful because the latest independently verifiable audited financial statements available through public sources are old. Public records show FY2021 revenue of approximately ₹17.4 Cr, while the latest publicly accessible annual-report material shows FY2020 revenue of ₹14.6 Cr and PAT of approximately ₹15 lakh.
At an indicative unlisted price around ₹29.90–₹35, the implied valuation is substantial relative to those old earnings.
Therefore, the biggest question for Madbow today is not whether the brand has potential, but what the company’s current revenue, profitability, debt and share capital actually look like.
Company Background
Madbow’s business originated around 2016, while the present legal entity was incorporated in 2017. The company was initially known as Madbow Fashion Private Limited and later became Madbow Ventures Limited.
The company’s historical positioning was built around creating fashion brands for young Indian consumers.
Its 2019-20 annual report described Madbow as a fashion and lifestyle business with a pan-India customer and distribution footprint. The company reported more than 1 million customers and access to more than 30,000 serviceable PIN codes at that time.
Business Model
Madbow has historically followed a multi-brand D2C fashion model.
Instead of relying on one brand, the company created multiple brands aimed at different consumer segments.
The historical portfolio included:
- StreetStyleStalk
- StalkBae
- SlayDeal
- LoveDaModa
- SlayXO
Industry coverage in 2022 described five in-house brands covering western wear, footwear and lingerie, with more than 1,500 SKUs.
The company’s more recent positioning additionally focuses on providing technology and operational infrastructure to D2C businesses. LinkedIn describes services including:
- E-commerce website creation
- Landing pages
- Payments
- Logistics
- CRM
- Marketplace payments
- Vendor payments
- Warehouse management
- Customer support
- Marketing
- Finance automation
This could potentially transform Madbow from a traditional fashion retailer into a D2C commerce-enablement platform.
Brand Portfolio
StreetStyleStalk
StreetStyleStalk has historically been one of Madbow’s key fashion brands.
The company expanded from online commerce into physical retail and opened its first flagship store in Gurugram in April 2022, followed by a second store in June 2022.
The stores carried women’s apparel, footwear and related fashion products.
StalkBae
StalkBae was positioned toward a somewhat more premium fashion consumer.
The brand formed part of Madbow’s original digital fashion portfolio.
SlayDeal
SlayDeal was designed toward the mass/value fashion segment.
LoveDaModa
LoveDaModa was another brand in the company’s multi-brand fashion portfolio.
SlayXO
SlayXO focused on fashion/lifestyle products and formed part of the company’s original five-brand strategy.
Historical Financial Performance
The most important caveat is that current audited financial information is not readily available through the public sources reviewed.
Public records show the following historical numbers.
Revenue
| Financial Year | Revenue / Total Income |
|---|---|
| FY2019 | ₹7.52 Cr |
| FY2020 | ₹14.61 Cr |
| FY2021 | ₹17.38 Cr |
FY2021 revenue increased approximately 19% over FY2020.
Profitability
| Financial Year | Profit |
|---|---|
| FY2019 | ₹0.03 Cr |
| FY2020 | ₹0.11 Cr / ~₹0.15 Cr depending on reporting basis |
| FY2021 | ₹0.37 Cr |
Public databases report FY2021 profit of approximately ₹37 lakh.
The company’s annual-report material for FY2020 also states that it had turned PAT positive, with revenue of ₹14.6 Cr and approximately ₹15 lakh consolidated PAT.
Historical Growth
From FY2019 to FY2021:
Revenue: ₹7.52 Cr → ₹17.38 Cr
This represents a two-year revenue CAGR of approximately 52%.
However, this was from a very small base.
Profitability remained relatively thin.
FY2021 PAT of approximately ₹37 lakh represents a net margin of only around 2.1%.
This is typical of an early-stage fashion/e-commerce model where:
- Customer acquisition costs are high
- Marketing expenses are significant
- Logistics costs are meaningful
- Discounts affect gross margins
- Inventory and returns create working-capital pressure
2019-20 Operating Highlights
Madbow’s annual report provides interesting operating information for FY2020.
The company reported:
₹24.9 Cr GMV
303,000 orders
and approximately 3,000 SKUs from 40 brands across its business verticals.
The report also showed:
Footwear
GMV: ₹19.6 Cr
Net revenue: ₹11.4 Cr
Orders: 248,000
Garments
GMV: ₹5.4 Cr
Net revenue: ₹3.1 Cr
Orders: 55,000
This indicates that footwear was an important contributor to the historical business.
Customer Base
Madbow reported more than 1 million customers in its 2019-20 company presentation/annual report.
Industry reports in 2021-22 later reported approximately 12 lakh satisfied customers, more than 600,000 orders during the preceding 12 months and more than 1 million social-media followers across the company’s private-label brands.
These figures are historical management/industry-reported metrics and should not be treated as current FY2026 customer numbers without updated company disclosure.
Marketplace Strategy
Madbow historically used a combination of:
Own websites
Direct-to-consumer websites allowed Madbow to control:
- Customer relationship
- Product presentation
- Pricing
- Data
- Marketing
- Customer experience
Third-party marketplaces
The company also partnered with major marketplaces such as:
- Myntra
- AJIO
- Amazon Fashion
Industry reports described Madbow working with marketplace fashion teams to provide curated designs.
This hybrid model provides broader reach but also creates dependency on marketplace economics and commissions.
Offline Expansion
Madbow began building an offline presence through StreetStyleStalk.
The first flagship store was launched in DLF Cybercity, Gurugram, in April 2022.
A second store followed at Arcadia South City-2 in June 2022.
Management had indicated plans for further Delhi-NCR expansion.
The strategic rationale was to combine:
Online + Offline
to increase customer reach and improve brand experience.
D2C Technology Opportunity
This could potentially become one of the more interesting aspects of the company.
The company’s current LinkedIn profile describes Madbow as an e-commerce and D2C technology platform supporting independent brands and startups.
The platform is described as providing:
Store creation → Payments → Logistics → Finance → CRM → Marketing → Operations
This model could generate revenue through:
- SaaS/service fees
- Transaction-related revenue
- Payment services
- Marketplace integrations
- Logistics
- Technology services
- Brand partnerships
If successfully scaled, this could provide higher operating leverage than a traditional fashion-retail model.
However, current revenue contribution from this segment cannot be independently verified from the publicly available audited financial information reviewed.
Funding History
Madbow reportedly raised approximately $2 million in Series A funding in January 2022.
Dealroom records the January 2022 funding round at approximately $2 million, while industry reports also reported the $2 million Series A round.
This is significant because institutional/strategic investor participation can provide:
- Capital
- Brand-building support
- Network
- Technology
- Governance
- Potential future fundraising access
However, the current cap table and ownership percentage of individual investors should be independently verified before investment.
Share Capital
Public corporate records currently show:
Authorised share capital: ₹2.00 Cr
Paid-up share capital: ₹1.5765 Cr.
There is a discrepancy between public-market data providers regarding the current number of shares.
Some unlisted-market sources report approximately:
1.5415 Cr shares
and a face value of ₹1, while MCA-derived records show paid-up capital of ₹1.5765 Cr.
This should be reconciled against the latest issuer/depository statement before calculating an exact market capitalisation.
Debt Position
Historical FY2021 data showed a debt/equity ratio of approximately 2.63x in one public database.
MCA-related records also show an outstanding HDFC Bank charge of approximately ₹1.50 Cr, created in September 2020, while an earlier ₹30 lakh SBI charge was satisfied in 2020.
Because newer audited financial statements are not publicly accessible through the sources reviewed, current debt cannot be reliably stated.
This is an important due-diligence item.
Competitive Advantages
1. Multi-brand strategy
Madbow has historically built several brands instead of depending entirely on one label.
2. D2C capability
Direct digital relationships can potentially provide better customer data and brand control.
3. Marketplace distribution
Presence across major online platforms provides access to a large consumer base.
4. Technology integration
The company’s current positioning combines fashion with e-commerce technology and operational automation.
5. Customer base
Historical company disclosures indicated more than one million customers.
6. Young-consumer focus
The company targets fashion-conscious consumers, particularly women, a segment benefiting from increasing online fashion adoption.
Growth Drivers
India’s Online Fashion Market
Increasing smartphone penetration, digital payments and online shopping continue to support D2C fashion businesses.
Brand Building
If Madbow can successfully build one or more nationally recognised brands, the economics could improve significantly.
D2C Enablement
Technology services for third-party brands could provide a second growth engine beyond Madbow’s own fashion labels.
Offline + Online
A successful omnichannel model can increase customer trust and potentially improve conversion.
New Categories
Historically, management discussed expansion into:
- Kids
- Ethnic wear
- High fashion
- Cosmetics
- General merchandise
This could increase the addressable market.
International Expansion
The company had obtained an export licence and reported servicing markets including Europe and Africa as of 2021.
Key Risks
1. Financial-information gap
This is the biggest issue.
The latest independently accessible financial statements I could verify are from approximately FY2021.
An investor should not assume that historical growth continued at the same rate.
2. Thin historical margins
FY2021 PAT was only around ₹37 lakh on ₹17.38 Cr revenue.
Fashion e-commerce can generate high revenue growth without generating proportionate profits.
3. High customer-acquisition costs
Online fashion requires continuous spending on:
- Advertising
- Influencer marketing
- Discounts
- Promotions
- Performance marketing
4. Inventory risk
Fashion inventory can become obsolete quickly when consumer preferences change.
5. Returns and logistics
Online apparel has higher return rates than many other e-commerce categories, which can reduce contribution margins.
6. Competition
Madbow competes indirectly with:
- Myntra
- AJIO
- Amazon Fashion
- Flipkart
- Nykaa Fashion
- Large D2C brands
- Instagram/social-commerce brands
7. Unlisted liquidity
There is no NSE/BSE market for the shares.
Exit depends on finding an OTC buyer.
8. Valuation risk
The current unlisted valuation looks expensive if measured against the old verified earnings.
9. Corporate transparency
The absence of easily accessible recent audited financial statements makes valuation considerably more difficult.
Current Unlisted Share Price
Current unlisted-market references are approximately:
₹29.90–₹35 per share
Planify reported ₹29.90 as of 12 September 2026, with a 52-week high of ₹34 and low of ₹29.
Other unlisted platforms currently show approximately ₹35.
Moneycontrol currently displays approximately ₹37.22, but its own page notes that unlisted prices are derived from partners and are indicative rather than exchange-traded prices.
Indicative Market Range
₹30–₹37 per share
Investors should verify the actual executable price and available quantity before transacting.
Valuation Analysis
Using the historical FY2021 PAT of approximately ₹37 lakh, valuation becomes a major concern.
Assuming approximately 1.54–1.58 Cr shares:
At ₹30/share:
Implied equity value ≈ ₹46–47 Cr
At ₹35/share:
Implied equity value ≈ ₹54–55 Cr
At ₹37/share:
Implied equity value ≈ ₹57–58 Cr
Against FY2021 PAT of only ₹0.37 Cr:
| Price | Approx. Market Cap | Approx. P/E on FY21 PAT |
|---|---|---|
| ₹30 | ₹46 Cr | ~125x |
| ₹35 | ₹54 Cr | ~146x |
| ₹37 | ₹57 Cr | ~155x |
These are illustrative calculations based on old FY2021 earnings, not current earnings.
Therefore, the stock cannot be called inexpensive based on the last publicly verified audited profit.
Historical Book Value
FY2021 public data showed shareholder funds of approximately ₹1 Cr.
That implies a historically very low book value relative to today’s indicative market price.
This means traditional P/B valuation also does not provide strong support for the current valuation.
The market is therefore effectively pricing in future growth rather than historical book value or historical earnings.
What Must Be Verified Before Investing?
For Madbow, I would consider the following mandatory due-diligence checklist:
Financial
- FY2022 audited financials
- FY2023 audited financials
- FY2024 audited financials
- FY2025 audited financials
- FY2026 latest financials
- Current EBITDA
- Current PAT
- Current debt
- Current cash
- Operating cash flow
Business
- Current GMV
- Current revenue
- Number of active customers
- Repeat customer rate
- Average order value
- Contribution margin
- Return rate
- Customer acquisition cost
- Marketing spend
Corporate
- Current share capital
- Current shareholder list
- Latest cap table
- Latest valuation round
- Investor holdings
- Related-party transactions
- Current directors
- Any preferential allotments
- Any ESOP dilution
IPO
- DRHP filing
- IPO appointment of merchant bankers
- Formal listing plan
- Any SEBI filing
Moneycontrol currently shows DRHP status: No, so an IPO should not be treated as a confirmed catalyst at present.
Investment Positives
- Established fashion e-commerce platform
- Multi-brand strategy
- D2C orientation
- Historical customer base of 1M+
- Presence across online marketplaces
- Offline expansion capability
- Technology/D2C enablement opportunity
- Previous institutional funding
- Potential for brand-led operating leverage
- Large Indian fashion market
Investment Concerns
- Latest independently verifiable audited financials are old
- Historical PAT was very small
- Potentially high valuation relative to verified earnings
- Historically high debt/equity
- Fashion inventory risk
- High marketing/customer-acquisition expenses
- Strong competition
- Unlisted liquidity
- Current cap-table/share-count discrepancies across data providers
- No confirmed IPO filing found
Overall Assessment
Business Model: ★★★★☆
Market Opportunity: ★★★★☆
Brand Potential: ★★★½☆
Technology Opportunity: ★★★★☆
Historical Profitability: ★★☆☆☆
Balance Sheet Visibility: ★★☆☆☆
Current Valuation: ★★☆☆☆
Unlisted Liquidity: ★★☆☆☆
Final Investment View
Madbow Ventures is an interesting but high-risk unlisted consumer/D2C opportunity.
The company has an attractive strategic proposition:
Fashion Brands + D2C + E-commerce + Technology
Its historical journey from online fashion brands toward an omnichannel and D2C-enablement platform gives it significant potential if management has successfully scaled the business after FY2021.
The previous funding round, multi-brand strategy, customer base and marketplace relationships are positives.
However, the biggest problem from an investment-research perspective is financial visibility.
The latest audited financial information I could independently verify shows FY2021 revenue of approximately ₹17.4 Cr and PAT of approximately ₹37 lakh.
Against a current indicative valuation of roughly ₹46–58 Cr, based on ₹30–37 per share and approximately 1.54–1.58 Cr shares, the historical earnings multiple is extremely high.
Therefore, Madbow should not be purchased merely on the expectation of an IPO or because it is a fashion/D2C company.
The investment case becomes much stronger only if the company can demonstrate that current revenue and profitability have increased substantially since FY2021.
The key question for investors is:
“What is Madbow earning today?”
If current PAT has scaled from ₹0.37 Cr to ₹3–5 Cr or more, the current valuation could look very different.
If earnings have not scaled meaningfully, the current unlisted price provides limited margin of safety.
My research view:
Potentially attractive business story — but currently insufficient financial visibility for a high-conviction investment call.
Before recommending it to a client, I would insist on obtaining the latest audited FY2025/FY2026 financial statements and current cap table.
Important Links
Official Company Website:
Madbow Ventures
Company / Management Profile:
Madbow Ventures on LinkedIn
Historical Annual Report:
Madbow Ventures Annual Report 2019-20 / FY2020 financial material
Current Unlisted Price Reference:
Planify – Madbow Ventures
Unlisted Market Reference:
Moneycontrol – Madbow Ventures
Corporate Information:
Madbow Ventures – Corporate Details
Disclaimer
This report is prepared for informational and research purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Unlisted securities involve higher liquidity, valuation, information and exit risks compared with listed securities. Unlisted-market prices are indicative and may vary significantly between intermediaries.
Historical financial information should not be assumed to represent current performance. Investors should obtain and verify the latest audited financial statements, cap table, shareholding, debt position, related-party transactions, share availability, transfer documentation, taxation and executable transaction price before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
