
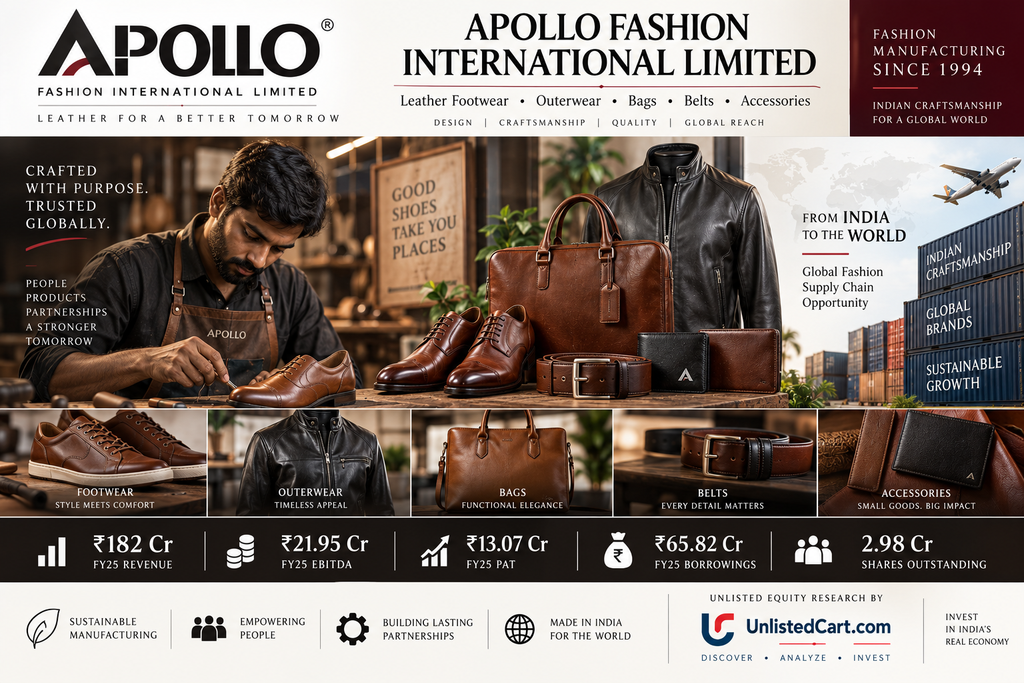
Company: Apollo Fashion International Limited
CIN: U46411DL2023PLC419636
ISIN: INE0RYY01014
Incorporated: 6 September 2023
Registered Office: DLF Courtyard, Saket, New Delhi
Manufacturing Locations: Noida, Uttar Pradesh
Face Value: ₹10 per share
Paid-up Equity Capital: ₹29.77 Cr
Shares Outstanding: 2.98 Cr
Listing Status: Unlisted Public Company
Industry: Leather Products / Fashion Manufacturing / Consumer Discretionary
Latest Financial Year Analysed: FY2024-25
Official Website: Apollo Fashion International
Official Investor Relations: Investor Relations
Official Annual Reports: Annual Reports
Official Manufacturing Page: Manufacturing Capacity
Official Contact Page: Contact Apollo Fashion International
Executive Summary
Apollo Fashion International Limited is an unlisted Indian fashion-manufacturing company focused primarily on premium leather footwear, outerwear and accessories for leading fashion brands.
The company has its operating roots in the Apollo Group’s fashion business, with the company website tracing the fashion manufacturing business back to 1994. The current legal entity was incorporated in September 2023 and subsequently acquired the fashion division of Apollo Green Energy Limited through a ₹95 Cr Business Transfer Agreement (BTA) effective 1 June 2024.
AFIL’s product portfolio includes:
- Leather footwear
- Leather jackets and outerwear
- Bags
- Belts
- Small leather goods
- Other leather accessories
The company describes itself as a manufacturing partner for global fashion brands, combining traditional craftsmanship with modern manufacturing, quality systems and responsible sourcing.
FY2024-25 was the company’s first full financial year following the transfer of the fashion business. Revenue from operations was ₹182.44 Cr, EBITDA approximately ₹21.95 Cr and PAT approximately ₹13.07 Cr.
The company is interesting from an unlisted-equity perspective because it combines:
Export-oriented manufacturing + leather products + global fashion supply chains + Apollo Group backing + potential operating scalability.
However, there are also meaningful risks. FY2025 debt was approximately ₹65.82 Cr, around 97% of which was short-term borrowings, while cash and cash equivalents were only around ₹0.04 Cr. In addition, approximately 45.7% of FY2025 revenue came from sales to Apollo Green Energy, according to research based on the annual report, creating an important customer-concentration/related-party risk that investors should monitor.
Company Overview
Apollo Fashion International Limited was incorporated on 6 September 2023 as a public limited company.
The company’s legal structure was created to house the fashion business that previously operated within Apollo Green Energy Limited.
The company subsequently entered into a Business Transfer Agreement with Apollo Green Energy Limited under which the fashion undertaking was transferred with effect from 1 June 2024. The total consideration was ₹95 Cr.
The official company website states that its fashion-manufacturing roots date back to 1994, while other unlisted-market sources describe the leather venture as having started in 1995. The distinction relates to the historical operating business versus the present legal entity.
Business Model
Apollo Fashion is primarily a B2B fashion manufacturing company.
Rather than building its own large consumer retail brand, the company focuses on manufacturing products for fashion brands.
Its business model involves:
- Product development
- Material sourcing
- Leather processing and preparation
- Cutting and manufacturing
- Quality control
- Finishing
- Compliance and sustainability processes
- Delivery to global fashion customers
The company’s official website describes its capabilities as taking products from “sketch to store”, combining design execution, manufacturing capability and quality systems.
Product Portfolio
1. Leather Footwear
Footwear is one of the company’s core product categories.
The company manufactures a broad range of leather footwear, ranging from everyday products to more premium/high-fashion designs.
2. Leather Outerwear
The company manufactures:
- Leather jackets
- Coats
- Premium outerwear
The outerwear division benefits from India’s growing role in global fashion sourcing.
3. Leather Bags
Apollo Fashion also manufactures leather bags and related accessories.
4. Belts & Small Leather Goods
The company’s portfolio also includes belts and small leather goods.
This broader product mix is strategically useful because it allows customers to source multiple categories from the same manufacturing partner.
Global Market Opportunity
India is increasingly positioned as a manufacturing and sourcing destination for global fashion companies.
The opportunity for companies such as Apollo Fashion comes from the shift toward:
- Diversification of global supply chains
- China+1 sourcing
- Higher-quality manufacturing
- Responsible sourcing
- Compliance
- Shorter supply chains
- Premium leather products
- Export-oriented Indian manufacturing
Apollo Fashion’s own strategy is built around making India a trusted partner for international fashion brands.
The company’s website highlights its international orientation and focus on responsible manufacturing.
Manufacturing Infrastructure
Apollo Fashion operates manufacturing facilities in Noida, Uttar Pradesh.
The company’s official contact information identifies:
Footwear Division:
C-30, Sector-58, Noida
Leather Garments & Accessories:
B-21, Sector-65, Noida
The company’s manufacturing philosophy combines:
- Skilled craftsmanship
- Modern manufacturing
- Quality-control systems
- Responsible sourcing
- Sustainability
- Product development
The company currently publishes its manufacturing capabilities and processes on its official website.
Business Transfer Agreement – Important Transaction
The ₹95 Cr BTA is one of the most important aspects of the investment story.
Apollo Fashion acquired the fashion undertaking from Apollo Green Energy Limited.
The transaction consisted of approximately:
Cash consideration: ₹61.50 Cr
Equity consideration: ₹33.50 Cr
Total consideration: ₹95 Cr
The acquired undertaking had net assets of approximately ₹62.66 Cr according to an analysis of the annual report.
The equity component consisted of 1,11,67,200 Apollo Fashion shares issued at ₹30 per share.
This transaction is important because it explains the substantial increase in Apollo Fashion’s equity capital during FY2025.
Share Capital
As of 31 March 2025:
Authorised share capital: ₹53 Cr
Paid-up share capital: ₹29.77 Cr
Shares outstanding: 2,97,65,210
The number of shares increased from approximately 1.45 Cr to 2.98 Cr during FY2025.
Shareholding Pattern
As of 31 March 2025, significant shareholders included:
| Shareholder | Holding |
|---|---|
| Apollo Green Energy Limited | 37.52% |
| RK Eternova Pvt Ltd | 21.22% |
| Kanwar Family Administrative Services Pvt Ltd | 8.67% |
| Raaja Kanwar | 5.16% |
| Kamayani Singh Kanwar | 4.03% |
| Others | Balance |
Apollo Green Energy’s 37.52% holding is particularly important because the company was the seller of the fashion business under the BTA.
Management
The company is associated with the Apollo Group and Kanwar family.
Key leadership includes:
Raaja Kanwar – Chairman / Director
Shiraz Askari – Whole-Time Director
Zeefan O S Kanwar – Director
The company also has independent directors and professional management including a CFO and Company Secretary.
The company’s website highlights Raaja Kanwar’s broader Apollo Group leadership and Shiraz Askari’s role in developing the fashion business.
FY2024-25 Financial Performance
Profit & Loss
| Particular | FY2023-24* | FY2024-25 |
|---|---|---|
| Revenue from Operations | ₹89.98 Cr | ₹182.44 Cr |
| Other Income | ₹3.12 Cr | ₹3.51 Cr |
| EBITDA | ₹17.86 Cr | ₹21.95 Cr |
| EBITDA Margin | 19.85% | 12.03% |
| Finance Cost | ₹3.70 Cr | ₹5.08 Cr |
| Depreciation | ₹2.81 Cr | ₹2.90 Cr |
| PBT | ₹16.25 Cr | ₹17.47 Cr |
| PAT | ₹12.15 Cr | ₹13.07 Cr |
| PAT Margin | 13.50% | 7.16% |
*FY2023-24 covers only approximately seven months.
Source: FY2024-25 financial statements and annual-report analysis.
Important Financial Observation
Revenue more than doubled from ₹89.98 Cr to ₹182.44 Cr, but this should not be interpreted as 100% organic growth because FY2023-24 represents only seven months.
The better benchmark is the historical fashion division performance when it was part of Apollo Green Energy.
The division generated approximately ₹208 Cr revenue in FY2022-23, compared with ₹182.44 Cr reported by AFIL in FY2024-25.
Therefore, the current financials should be viewed as a transition and restructuring story, rather than a conventional high-growth company with clean year-on-year comparables.
EBITDA Analysis
FY2025 EBITDA was approximately:
₹21.95 Cr
with an EBITDA margin of:
12.03%
The margin was lower than the reported 19.85% in FY2024, but FY2024 represented only seven months and therefore is not directly comparable.
For an export-oriented manufacturing company, sustainable EBITDA margins and operating leverage will be important valuation drivers.
Balance Sheet
FY2025 Assets
| Particular | FY2025 |
|---|---|
| Property, Plant & Equipment | ₹23.50 Cr |
| Right-of-use assets | ₹2.68 Cr |
| Intangible assets | ₹0.42 Cr |
| Total Non-current Assets | ₹27.24 Cr |
| Inventories | ₹48.58 Cr |
| Trade Receivables | ₹46.75 Cr |
| Cash & Cash Equivalents | ₹0.04 Cr |
| Other Bank Balances | ₹12.00 Cr |
| Other Current Financial Assets | ₹7.48 Cr |
| Total Current Assets | ₹121.96 Cr |
| Total Assets | ₹149.20 Cr |
Debt Position
FY2025 borrowings were approximately:
₹65.82 Cr
Break-up:
- Non-current borrowings: ₹2.16 Cr
- Current borrowings: ₹63.66 Cr
Therefore, approximately 96.7% of total borrowings were short-term.
Against equity of approximately ₹49.57 Cr, the reported debt/equity is approximately:
1.33x
This is one of the most important risks in the current investment case.
Apollo Fashion is an asset-light-to-moderate manufacturing business, but its short-term borrowing level is relatively high compared with shareholder equity.
Liquidity
The company reported a current ratio of approximately:
1.30x
and quick ratio of approximately:
0.78x
at March 2025.
Cash and cash equivalents were only approximately ₹0.04 Cr, although the company had around ₹12 Cr in other bank balances, primarily fixed deposits.
This means investors should look beyond the headline cash balance and examine the quality and availability of short-term liquidity.
Cash Flow
FY2025 operating cash flow was approximately:
₹13.27 Cr
However, the company spent approximately ₹67.80 Cr on investing activities, largely reflecting the acquisition/business-transfer payment and movement in fixed deposits. Financing activities provided approximately ₹49.49 Cr.
This indicates that the business was still in a capital-restructuring phase during FY2025.
Future free cash flow generation will therefore be an important metric to monitor.
Related-Party / Customer Concentration Risk
This is one of the biggest points investors should investigate before investing.
According to an analysis of the FY2025 annual report, approximately ₹83.37 Cr, or around 45.7% of FY2025 revenue, came from sales to Apollo Green Energy.
The analysis also notes approximately ₹17.76 Cr of receivables from Apollo Green Energy outstanding at 31 March 2025.
This creates two questions:
- How quickly can AFIL diversify its customer base?
- How much of the revenue is truly independent of the Apollo Group?
A reduction in related-party concentration would be a major positive development for the investment thesis.
Export Orientation
The company has a meaningful export orientation.
FY2025 foreign exchange earnings were reported at approximately:
₹67.17 Cr
against foreign exchange outgo of approximately:
₹11.33 Cr.
Export growth can provide access to larger international markets but also exposes the company to:
- Currency fluctuations
- Global fashion cycles
- International demand
- Geopolitical developments
- Customer concentration
- International compliance requirements
Competitive Advantages
1. Established operating experience
The fashion business has been operating since the 1990s, despite the present corporate entity being incorporated only in 2023.
2. Apollo Group association
The company benefits from the Apollo Group’s business relationships and management experience.
3. Leather manufacturing expertise
The company specialises in technically demanding leather products rather than basic garment manufacturing.
4. Multi-product capability
Customers can source:
- Shoes
- Jackets
- Bags
- Belts
- Small leather goods
from the same manufacturing ecosystem.
5. Export capability
The company’s significant foreign-exchange earnings demonstrate its international orientation.
6. India manufacturing opportunity
The global diversification of fashion supply chains creates an opportunity for Indian manufacturers with strong compliance, quality and delivery capabilities.
Growth Drivers
Global Fashion Supply-Chain Diversification
Global brands continue to diversify sourcing bases, creating opportunities for Indian manufacturers.
Higher-Value Leather Products
Premium footwear, jackets, handbags and accessories can command better realisations than basic manufacturing.
Customer Diversification
Reducing dependence on Apollo Green and increasing direct relationships with external international brands could significantly improve the quality of earnings.
Operating Leverage
If revenue scales faster than fixed manufacturing and administrative costs, EBITDA margins could improve.
Export Expansion
The company’s international customer base provides a large addressable market beyond India.
Sustainability
Responsible sourcing and sustainable manufacturing are increasingly important criteria for global fashion brands. AFIL explicitly positions sustainability and ethical practices as part of its operating proposition.
Key Risks
1. High Short-Term Debt
Approximately 96.7% of FY2025 borrowings were short-term.
This creates refinancing and working-capital risk.
2. Customer Concentration
Around 45.7% of FY2025 revenue was reportedly from Apollo Green Energy.
This is a major issue to monitor.
3. Related-Party Exposure
The company has significant relationships with Apollo Group entities.
Investors should carefully examine related-party transactions, receivables and commercial terms.
4. Working-Capital Intensity
Receivables increased materially while inventory remained high.
5. Fashion-Cycle Risk
Fashion manufacturing is exposed to:
- Changing consumer preferences
- Customer order cancellations
- Seasonal demand
- Inventory management
- Global economic cycles
6. Currency Risk
A significant portion of business is export-oriented.
7. Unlisted Liquidity
There is no NSE/BSE trading market.
Investors may therefore face:
- Limited buyers
- Wide bid/ask spreads
- Difficulty exiting
- Dealer-to-dealer price differences
- Longer holding periods
8. Young Legal Entity
Although the underlying business has decades of history, AFIL as a legal entity was incorporated only in 2023.
This makes historical standalone financial comparisons more difficult.
Current Unlisted Share Price
As of September 2026, available unlisted-market references show a price around:
₹44–₹47 per share
One source reports ₹44 as of 13 September 2026, while another market tracker published on 14 September 2026 shows approximately ₹45–47.
These are indicative OTC/unlisted-market references and not NSE/BSE prices.
Another market reference, Moneycontrol, showed ₹50.19 in its latest displayed quote, illustrating the price variation that can exist in the unlisted market.
Current Valuation
At ₹44 per share and approximately 2.9765 Cr shares:
Implied Market Capitalisation ≈ ₹131 Cr
One current unlisted-market source reports approximately:
- Market Cap: ₹131 Cr
- P/E: ~10.0x
- P/B: ~2.64x
- Book Value: ~₹16.69/share
- Debt/Equity: ~1.33x
- ROE: ~26.36%
Earnings Valuation
Using FY2025 PAT of approximately ₹13.07 Cr:
| P/E | Implied Equity Value | Approx. Value/Share |
|---|---|---|
| 8x | ₹104.6 Cr | ₹35 |
| 10x | ₹130.7 Cr | ₹44 |
| 12x | ₹156.8 Cr | ₹53 |
| 15x | ₹196.1 Cr | ₹66 |
| 18x | ₹235.3 Cr | ₹79 |
At around ₹44, the market is valuing AFIL at approximately:
10x FY2025 PAT
This is relatively moderate compared with many high-growth consumer/FMCG companies, but AFIL is a manufacturing company with higher financial and customer-concentration risks.
Book Value Valuation
FY2025 equity was approximately:
₹49.57 Cr
With 2.9765 Cr shares, book value works out to approximately:
₹16.65 per share
At ₹44:
P/B ≈ 2.64x
At ₹50:
P/B ≈ 3.0x
Therefore, the market is already assigning a meaningful premium to the company’s book value.
What Could Change the Valuation?
The biggest valuation triggers would be:
1. Revenue growth above ₹250–300 Cr
2. EBITDA margin returning toward 14–15%+
3. PAT moving toward ₹20 Cr+
4. Reduction in short-term debt
5. Strong free cash-flow generation
6. Diversification away from Apollo Green
7. Addition of large international customers
8. Any formal IPO/listing plan
IPO / Listing Status
Apollo Fashion International is currently unlisted.
There is no confirmed IPO date in the information reviewed for this report.
Importantly, being described by intermediaries as a “pre-IPO” or “likely IPO” opportunity does not mean an IPO has been approved or scheduled.
Investors should wait for an official DRHP/RHP or formal company/exchange filing before treating an IPO as a confirmed catalyst.
Moneycontrol currently shows DRHP Status: No.
Investment Positives
- Strong Apollo Group backing
- Established fashion-manufacturing experience
- Leather-specialist manufacturing capability
- Footwear, outerwear and accessories diversification
- Export-oriented business
- ₹182 Cr FY2025 revenue
- ₹21.95 Cr EBITDA
- ₹13.07 Cr PAT
- Potential operating leverage
- India opportunity in global fashion sourcing
- Current valuation around 10x FY2025 earnings at ₹44
- Potential upside if customer diversification and margins improve
Investment Concerns
- Debt/equity around 1.33x
- Majority of debt is short-term
- Very low reported cash balance
- High working-capital requirement
- Significant related-party/customer concentration
- FY2024 is only a seven-month period
- Limited standalone historical track record
- Unlisted liquidity
- No confirmed IPO
- Fashion-industry cyclicality
- Currency and global demand risk
Overall Assessment
Business Quality: ★★★★☆
Industry Opportunity: ★★★★☆
Management/Group Support: ★★★★☆
Growth Potential: ★★★★☆
Balance Sheet: ★★½☆☆
Cash Flow: ★★★☆☆
Valuation around ₹44: ★★★★☆
Unlisted Liquidity: ★★☆☆☆
Final Investment View
Apollo Fashion International is an interesting emerging Indian export-manufacturing opportunity, but the investment thesis should be based on the underlying business rather than simply the possibility of an IPO.
The company’s biggest strengths are its established leather-manufacturing capability, Apollo Group association, export orientation, multi-product platform and exposure to the global fashion supply chain.
At approximately ₹44–47 per share, the valuation of around 10–11x FY2025 earnings appears more reasonable than many highly valued unlisted consumer businesses.
However, the balance sheet requires closer attention. ₹65.82 Cr of debt against ₹49.57 Cr of equity, with approximately 96.7% of borrowings being short-term, is a significant risk.
The other major issue is customer concentration. If the company can reduce its dependence on Apollo Green Energy and demonstrate that it can independently build relationships with global fashion brands, the quality of the earnings profile could improve materially.
Therefore, Apollo Fashion should be viewed as:
A potentially attractive small-cap unlisted manufacturing opportunity, but with meaningful execution, leverage and customer-concentration risks.
The next 2–3 years should be judged primarily on:
- Revenue growth
- EBITDA margin
- PAT growth
- Debt reduction
- Operating cash flow
- Customer diversification
- Export growth
- Related-party exposure
- New international customer additions
- Any formal IPO/listing filing
Important Links
Official Company Website:
Apollo Fashion International Limited
About the Company:
Apollo Fashion International – About Us
Investor Relations:
Apollo Fashion International – Investor Relations
Annual Reports:
Apollo Fashion International – Annual Reports
Manufacturing Capabilities:
Apollo Fashion International – Manufacturing Capacity
Official Contact:
Apollo Fashion International – Contact
Current Unlisted Price Reference:
Apollo Fashion International – Unlisted Share Reference
Financial Data Reference:
Apollo Fashion International – Financials
Disclaimer
This report is prepared for informational and research purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Unlisted securities involve higher liquidity, valuation, information and exit risks compared with listed securities. Unlisted prices quoted by intermediaries are indicative and may differ significantly depending on inventory, lot size, buyer/seller demand and transaction terms.
Investors should independently verify the latest audited financial statements, shareholding, related-party transactions, share availability, transfer restrictions, taxation and executable transaction price before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
