
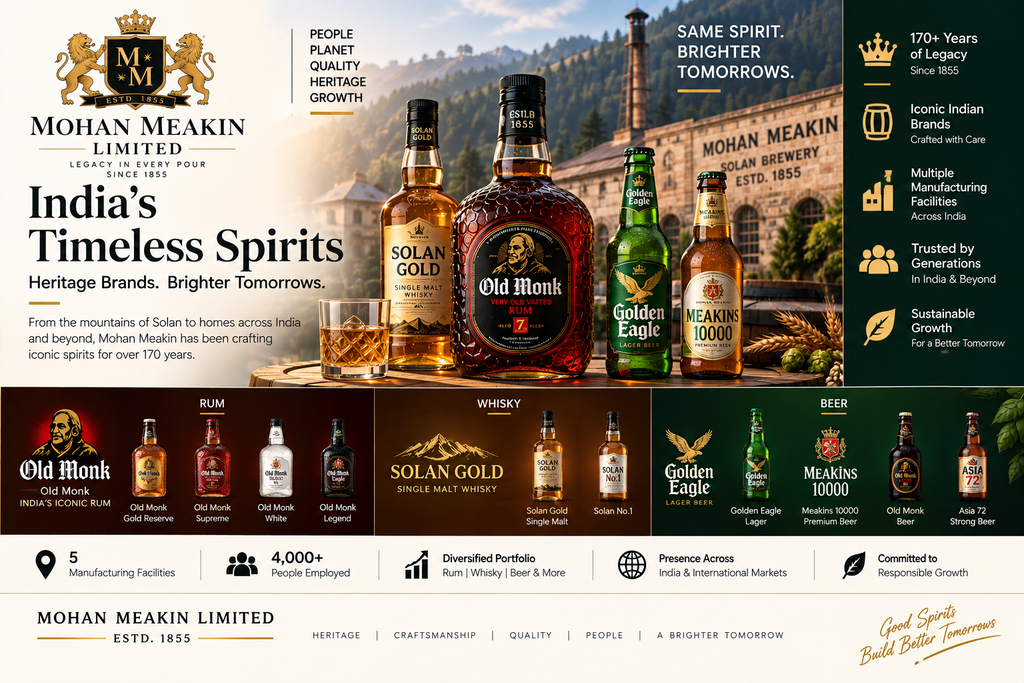
170+ Years of Legacy | Old Monk & Heritage Brands | Profitable, Debt-Light Consumer Opportunity
Company: Mohan Meakin Limited
CIN: L15520HP1934PLC000135
ISIN: INE136D01018
Face Value: ₹5 per share
Registered Office: Solan Brewery, Himachal Pradesh
Established: 1855
Sector: Alcoholic Beverages / Consumer Staples
Status: Public Limited Company — CSE Listed, not actively traded on NSE/BSE
Flagship Brand: Old Monk
Current Reference Price: ~₹2,320–₹2,325/share
Total Shares: 85.08 lakh
Important Listing Status
Mohan Meakin is often marketed in the private market as an “unlisted share”. However, technically this is not correct.
The company’s shares are listed on the Calcutta Stock Exchange (CSE). The company’s own website confirms the CSE listing and ISIN INE136D01018.
Therefore:
Mohan Meakin = CSE-listed / effectively illiquid security rather than a conventional unlisted company.
This distinction is important for investors and should be clearly disclosed on any UnlistedCart page.
About the Company
Mohan Meakin is one of India’s oldest surviving beverage companies, tracing its origins back to 1855, when Edward Dyer established a brewery at Kasauli.
Over the following decades, the business expanded through breweries and distilleries across India and eventually became Mohan Meakin Limited in 1980.
The company has developed into a diversified alcoholic-beverage and consumer-products group with businesses spanning:
- Rum
- Whisky
- Beer
- Brandy
- Vodka
- Gin
- Ready-to-drink beverages
- Fruit products
- Breakfast foods
- Mineral water
- Other food products
The company’s flagship brand is Old Monk, one of India’s most recognised dark-rum brands.
Brand Portfolio
Alcoholic Beverages
Rum
- Old Monk
- Old Monk Gold Reserve
- Old Monk Supreme
- Old Monk White
- Old Monk Legend
- Other variants
Whisky
- Solan Gold Single Malt
- Solan No. 1
- Other whisky products
Beer
- Meakins 10000
- Golden Eagle Lager
- Golden Eagle Strong
- Old Monk Beer
- Asia 72
- IQ Wheat Beer
The company continues to maintain a diversified beverage portfolio rather than depending entirely on one category.
Business & Manufacturing Footprint
Mohan Meakin currently operates manufacturing facilities including:
| Location | Operations |
|---|---|
| Solan, Himachal Pradesh | Brewery & spirit bottling |
| Kasauli, Himachal Pradesh | Distillery / malt spirit |
| Mohan Nagar, Ghaziabad | Brewery, distillery and food-product manufacturing |
| Mohangram, Punjab | IMFL bottling |
| Lucknow, Uttar Pradesh | Distillery — production currently stopped |
The company also has manufacturing, marketing and distribution arrangements with other breweries and distilleries.
Old Monk — The Core Brand Asset
Old Monk is the most important intangible asset in the Mohan Meakin story.
The brand has survived multiple generations and has developed strong recognition in India’s rum market.
Unlike many newer beverage companies that have to spend heavily to establish consumer recognition, Mohan Meakin already owns a deeply established brand franchise.
This creates an important strategic advantage:
Brand heritage + distribution network + manufacturing capability + low financial leverage
The challenge is converting that brand strength into faster growth and greater shareholder value.
Financial Performance
Mohan Meakin has delivered a remarkably consistent improvement in financial performance over the last five years.
Financial Snapshot
₹ Crore
| Particulars | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Revenue / Total Income | 1,379 | 1,779 | 1,942 | 2,167 | 2,334 |
| Revenue from Operations | 1,370 | 1,771 | 1,930 | 2,151 | 2,302 |
| EBITDA | 76.6 | 99.6 | 123.1 | 148.8 | 220.6 |
| PBT | 69.0 | 85.8 | 113.9 | 138.2 | 209.2 |
| PAT | 51.5 | 62.4 | 84.7 | 102.6 | 156.8 |
| EPS | ₹60.47 | ₹73.30 | ₹99.55 | ₹120.61 | ₹184.23 |
FY26 data shows a particularly strong acceleration in profitability. Revenue increased approximately 7.7%, while EBITDA increased approximately 48% and PAT increased approximately 53%.
Five-Year Growth Story
From FY22 to FY26:
Revenue
₹1,379 Cr → ₹2,334 Cr
Approximately 14% CAGR
PAT
₹51.5 Cr → ₹156.8 Cr
Approximately 32% CAGR
EBITDA
₹76.6 Cr → ₹220.6 Cr
Approximately 30% CAGR
This is one of the strongest aspects of the Mohan Meakin investment case.
The company isn’t merely growing sales.
Profitability is growing significantly faster than revenue.
Margin Expansion
The improvement in operating economics is even more interesting.
| Metric | FY22 | FY26 |
|---|---|---|
| EBITDA | ₹76.6 Cr | ₹220.6 Cr |
| Revenue | ₹1,379 Cr | ₹2,334 Cr |
| EBITDA Margin | ~5.6% | ~9.4% |
| PAT | ₹51.5 Cr | ₹156.8 Cr |
| PAT Margin | ~3.7% | ~6.7% |
This suggests that Mohan Meakin is benefiting from a combination of:
- Better product mix
- Higher operating efficiency
- Premiumisation
- Better capacity utilisation
- Operating leverage
- Stronger profitability of the core beverage business
Balance Sheet
The balance sheet is arguably one of the strongest reasons to investigate Mohan Meakin.
FY26
| Particular | Amount |
|---|---|
| Total Assets | ₹813.95 Cr |
| Net Worth | ₹626.13 Cr |
| Total Liabilities | ₹187.82 Cr |
| Debt / Equity | ~0.01x |
| Operating Cash Flow | ₹167.79 Cr |
| Finance Cost | ₹0.78 Cr |
The company is effectively debt-free on a conventional debt/equity basis.
This is a major contrast with many rapidly growing consumer companies that carry substantial leverage.
Cash Flow
Operating cash generation has improved substantially.
| FY | Operating Cash Flow |
|---|---|
| FY22 | ₹47.7 Cr |
| FY23 | ₹42.0 Cr |
| FY24 | ₹66.7 Cr |
| FY25 | ₹96.5 Cr |
| FY26 | ₹167.8 Cr |
FY26 operating cash flow was approximately ₹168 crore, representing a significant improvement over FY25.
This gives the company considerable flexibility to:
- Invest in capacity
- Develop brands
- Reduce dependence on external capital
- Pay dividends
- Expand distribution
- Strengthen the balance sheet
Return Ratios
FY26 return ratios are also attractive.
ROCE: ~32.6%
ROE: ~25.0%
This combination of:
High ROCE + High ROE + Minimal Debt
is an important positive for a long-term investor.
Dividend
Mohan Meakin has also maintained a dividend payout.
FY26 dividend:
₹2.50 per share
versus:
- ₹1.50 FY25
- ₹1.00 FY24
- ₹1.00 FY23
Although the dividend yield is not the primary investment thesis, the increasing payout demonstrates that the company is generating distributable profits.
Shareholding Pattern
Latest reported shareholding is approximately:
| Category | Holding |
|---|---|
| Promoters | 68.17% |
| Insurance Companies | 8.45% |
| Banks / Financial Institutions | 0.26% |
| Bodies Corporate | 1.32% |
| NRI / HUF / OCB | 4.79% |
| General Public | 17.00% |
The relatively high promoter ownership means the public float is limited.
This partly explains the low liquidity and large OTC price movements.
Current Market Price
As of 11 September 2026, available private-market references indicate approximately:
₹2,320–₹2,325 per share
Planify reported ₹2,320 on 11 September 2026, while another private-market source showed ₹2,325 on 10 September 2026. These are OTC/reference prices and not NSE/BSE market quotes.
Indicative Market Capitalisation
Shares outstanding:
85,08,479
At ₹2,320:
₹2,320 × 85.08 lakh ≈ ₹1,973 Cr
Therefore, indicative equity value is approximately:
₹1,970–1,980 Cr
Valuation
Using FY26 EPS of ₹184.23:
At ₹2,320:
P/E ≈ 12.6x
Using FY26 book value per share:
₹626.13 Cr ÷ 85.08 lakh shares
≈ ₹736/share
Therefore:
P/B ≈ 3.15x
This gives the company a very different valuation profile from many premium consumer businesses.
It is profitable, growing earnings, generating cash and carrying minimal debt.
Valuation Perspective
At roughly 12.5–13x FY26 earnings, the stock does not appear expensive relative to its:
- ~32% FY22–FY26 PAT CAGR
- ~30% EBITDA CAGR
- ~25% ROE
- ~33% ROCE
- ~0.01x debt/equity
- Strong brand portfolio
- ₹168 Cr operating cash flow
However, the low valuation multiple can partly be explained by:
- Very low liquidity
- CSE listing
- Limited institutional participation
- Small market capitalisation
- Alcohol-sector regulatory risks
- Limited disclosure compared with NSE/BSE companies
- Concentration around a few legacy brands
- Family/promoter control
Investment Positives
| Positive | Why It Matters |
|---|---|
| 170+ Year Legacy | Extremely strong heritage |
| Old Monk | Powerful established brand |
| Consistent Growth | Revenue and earnings have compounded strongly |
| FY26 PAT Growth ~53% | Strong recent acceleration |
| High ROCE | ~32.6% |
| High ROE | ~25% |
| Low Debt | Debt/equity ~0.01x |
| Strong Cash Flow | FY26 OCF ~₹168 Cr |
| Margin Expansion | EBITDA margin improved materially |
| Diversified Portfolio | Rum, whisky, beer and other products |
| Exports | International distribution provides additional opportunity |
| Increasing Dividend | Shareholder returns improving |
| Reasonable Valuation | ~12.6x FY26 earnings at ₹2,320 |
Key Risks
1. Liquidity Risk
This is perhaps the biggest risk.
Although shares have a CSE listing, the security does not have the liquidity of an actively traded NSE/BSE stock.
Large transactions may therefore be difficult to execute at quoted reference prices.
2. OTC Price Volatility
Private-market prices can vary substantially depending on:
- Buyer demand
- Seller availability
- Quantity
- Settlement terms
- Market sentiment
The ₹2,320–₹2,325 figure should therefore be treated as an indicative reference, not a firm market-clearing price.
3. Alcohol Regulation
Alcohol is heavily regulated in India.
State excise policies, taxation, licensing and distribution restrictions can materially influence profitability.
4. Brand Concentration
Old Monk remains an important part of the company’s brand equity.
The company needs to successfully build the next generation of products around its heritage brands.
5. Small Scale
Compared with large listed players such as United Spirits and United Breweries, Mohan Meakin remains a relatively small company.
6. Corporate Governance / Disclosure
Investors have significantly less real-time information compared with actively traded NSE/BSE companies.
7. CSE Listing
The CSE listing provides formal listed status but does not provide the price discovery and liquidity associated with a major national exchange.
8. Premiumisation Execution
Solan Gold and other premium products provide opportunity, but the company needs to scale premium products without sacrificing margins.
Growth Opportunities
1. Premium Whisky
Solan Gold Single Malt provides a route into India’s rapidly expanding premium whisky segment.
2. Premium Rum
Old Monk has enormous heritage value that can potentially be extended into higher-value premium expressions.
3. Beer
Golden Eagle, Meakins and other beer brands provide exposure to India’s growing beer market.
4. Exports
Mohan Meakin has historically exported products to international markets, and expansion could provide a valuable additional growth channel.
5. Brand Modernisation
The company’s legacy brands can potentially be repositioned for younger consumers without losing their heritage.
6. Operating Leverage
With strong cash flow and very low leverage, additional volume growth could translate into disproportionately higher profits.
IPO Status
No IPO Thesis
Unlike several other companies covered on UnlistedCart, Mohan Meakin should not be presented as a pre-IPO opportunity.
The company is already listed on the Calcutta Stock Exchange.
There is no need to build an investment thesis around a future IPO unless the company announces a separate migration/listing initiative.
The investment thesis should instead focus on:
Earnings growth + brand value + cash generation + low debt + potential re-rating/liquidity improvement.
What Could Unlock Value?
The most important potential catalysts are:
1. Continued PAT growth
↓
2. Expansion of premium products
↓
3. Higher Old Monk monetisation
↓
4. Stronger beer business
↓
5. Increasing dividend
↓
6. Improved investor awareness
↓
7. Potential migration to a more liquid exchange / broader price discovery
Any improvement in liquidity could materially change the valuation framework because the current discount is partly attributable to the company’s trading limitations.
Key Metrics to Monitor
| KPI | FY26 / Current |
|---|---|
| Revenue | ₹2,333.6 Cr |
| Revenue Growth | ~7.7% |
| EBITDA | ₹220.6 Cr |
| EBITDA Margin | ~9.4% |
| PAT | ₹156.8 Cr |
| PAT Growth | ~53% |
| EPS | ₹184.23 |
| ROE | ~25% |
| ROCE | ~32.6% |
| Debt/Equity | ~0.01x |
| Operating Cash Flow | ₹167.8 Cr |
| Net Worth | ₹626.1 Cr |
| Indicative Price | ~₹2,320–2,325 |
| Indicative Market Cap | ~₹1,974 Cr |
| Indicative P/E | ~12.6x |
| Indicative P/B | ~3.15x |
Financial figures are based on FY26 reported/compiled financial data; price and valuation are based on recent private-market references.
Investment View
Mohan Meakin — Legacy Consumer Brand with Strong Financial Transformation
Mohan Meakin is an unusual company in India’s beverage sector.
It has something that most new-age consumer companies spend enormous amounts of money trying to create:
170+ years of brand heritage.
But the investment case today is not simply about Old Monk.
The more interesting story is the combination of:
Consistent revenue growth + accelerating profitability + strong cash generation + minimal debt + high return ratios + reasonable earnings multiple.
FY22–FY26 PAT has grown from approximately ₹51.5 crore to ₹156.8 crore, while operating cash flow reached approximately ₹168 crore in FY26. At around ₹2,320 per share, the company trades at approximately 12.6x FY26 earnings.
Our Investment Classification
Business Quality: ⭐⭐⭐⭐½
Brand Strength: ⭐⭐⭐⭐⭐
Revenue Growth: ⭐⭐⭐⭐
Profit Growth: ⭐⭐⭐⭐⭐
Balance Sheet: ⭐⭐⭐⭐⭐
Cash Flow: ⭐⭐⭐⭐⭐
Return Ratios: ⭐⭐⭐⭐⭐
Valuation: ⭐⭐⭐⭐
Liquidity: ⭐⭐
Overall Risk: 🟠 Moderate–High
UnlistedCart View: FUNDAMENTALLY ATTRACTIVE — BUT LIQUIDITY IS THE KEY RISK
Mohan Meakin looks fundamentally stronger than many of the highly valued consumer names available in the unlisted market.
The key attraction is not an IPO story.
It is:
A profitable, cash-generating, almost debt-free legacy consumer company trading at a relatively modest earnings multiple, but with extremely limited liquidity.
For investors who can tolerate the liquidity constraint and hold for the long term, the combination of Old Monk’s brand equity, improving profitability, strong cash generation and low leverage makes Mohan Meakin a company worth serious consideration.
The biggest potential re-rating catalyst would be improved liquidity and price discovery, rather than an IPO.
Bottom Line
Mohan Meakin is not a typical high-growth startup or pre-IPO bet.
It is a legacy Indian consumer franchise undergoing a strong financial improvement cycle.
The numbers tell a compelling story:
Revenue: ₹1,379 Cr → ₹2,334 Cr
PAT: ₹51.5 Cr → ₹156.8 Cr
EBITDA: ₹76.6 Cr → ₹220.6 Cr
OCF: ₹47.7 Cr → ₹167.8 Cr
Debt/Equity: ~0.01x
FY26 EPS: ₹184.23
Indicative P/E: ~12.6x
The opportunity lies in whether the market eventually recognises the improvement in the underlying business.
The biggest risk isn’t the balance sheet.
It is liquidity and price discovery.
Disclaimer
This report is for informational and research purposes only and does not constitute investment advice, an offer, solicitation or recommendation to buy or sell securities. Mohan Meakin’s shares are listed on the Calcutta Stock Exchange, but the security is not actively traded like a conventional NSE/BSE-listed stock. Private-market/OTC reference prices are indicative and may differ materially based on quantity, availability and transaction terms. Investors should independently verify the latest annual report, financial statements, shareholding, transfer process, taxation and applicable regulations before making any investment decision.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
