
Company: SmartShift Logistics Solutions Private Limited
Brand: Porter
CIN: U74999MH2014PTC306120
Founded: 2014
Headquarters: Mumbai, Maharashtra
Business: Technology-enabled logistics & goods transportation
Status: Active, Unlisted Private Company
Face Value: ₹10 per equity share
ISIN: INE958W01015
Promoters/Founders: Pranav Goel & Uttam Digga
About the Company
Porter is an Indian technology-enabled logistics platform focused primarily on intra-city goods transportation. Founded in 2014 by Pranav Goel and Uttam Digga, the company connects businesses and consumers with driver-partners through its digital platform.
Its services include mini-truck and two-wheeler transportation, enterprise logistics, Packers & Movers and other goods-movement solutions. Porter has increasingly positioned itself as a broader logistics platform rather than simply a truck-booking application.
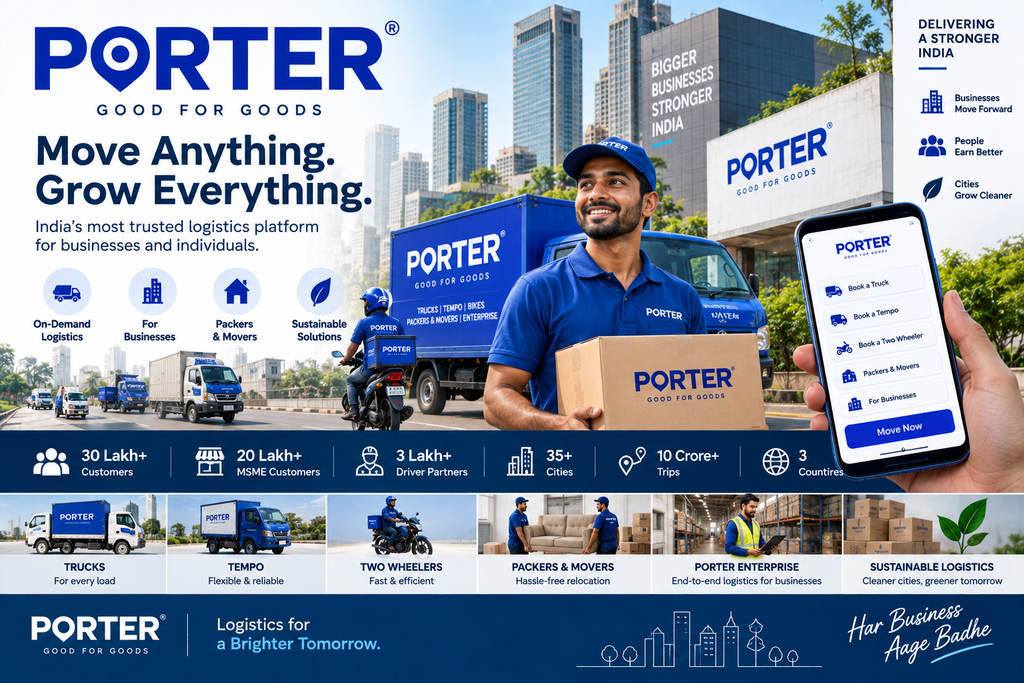
According to Porter, the platform now serves 30 lakh+ customers, including around 20 lakh MSMEs, with operations across 35 cities and a large driver-partner network.
Key Highlights
| Particular | Details |
|---|---|
| Founded | 2014 |
| FY26 Operating Revenue | ₹6,650 Cr |
| FY26 Net Profit | ₹229 Cr |
| FY26 Revenue Growth | 54.4% |
| FY26 Profit Growth | ~314% |
| FY26 EBITDA | ₹159 Cr |
| Latest Institutional Valuation | ~$1.1–1.2 Billion |
| Latest Funding | Series F – $200 Mn |
| Current Status | Unlisted |
| DRHP | Not filed |
| IPO | No fixed timeline |
| Indicative Unlisted Price | ~₹2,960/share |
Business Model
Porter operates a technology-driven, relatively asset-light logistics marketplace.
1. On-Demand Goods Transportation
Customers can book:
- Mini trucks
- Tempos
- Two-wheelers
- EV vehicles
- Other commercial vehicles
2. Porter Enterprise
Porter provides businesses with centralized logistics solutions for intra-city movement, distribution and last-mile transportation. Its enterprise offering serves large businesses, e-commerce merchants, supermarkets, kirana stores and MSMEs.
3. Packers & Movers
The company provides household and commercial relocation services.
4. Technology Platform
Porter’s technology connects customers with driver-partners, manages bookings, pricing, routing and logistics operations.
The company primarily earns through transportation services, with Porter generally retaining a portion of the customer billing while the remaining amount goes to driver-partners.
Scale & Network
Porter has expanded substantially since its launch.
- 30 lakh+ customers
- Around 20 lakh MSME customers
- 3 lakh driver-partners cited by the company/media
- 35 cities according to Porter’s latest company information
- 10 crore+ trips shown on Porter’s platform
- Operations across 3 countries
- Enterprise presence across 21+ cities
Porter’s long-term strategy is to deepen its presence in India’s largest urban markets while expanding its MSME customer base.
Financial Performance
Porter has reached an important inflection point: revenue continues to grow above 50%, while profitability is expanding much faster.
| Financial Year | Revenue from Operations | Net Profit/(Loss) |
|---|---|---|
| FY24 | ₹2,734 Cr | -₹96 Cr |
| FY25 | ₹4,306 Cr | ₹55 Cr |
| FY26 | ₹6,650 Cr | ₹229 Cr |
FY26 operating revenue increased approximately 54.4%, while net profit increased more than four times. Porter has therefore delivered two consecutive profitable years after being loss-making in FY24.
FY26 Additional Financial Metrics
| Metric | FY26 |
|---|---|
| Operating Revenue | ₹6,650 Cr |
| Total Income | ₹6,698 Cr |
| EBITDA | ₹159 Cr |
| Net Profit | ₹229 Cr |
| Total Expenses | ₹6,505 Cr |
| Fleet Operator Costs | ₹5,849 Cr |
| EBITDA Margin | ~3.1% |
Fleet operator costs remain the company’s largest expense and increased around 59% during FY26.
Important Financial Observation
Porter’s profitability has improved dramatically, but margins remain relatively thin.
Approximately ₹5,849 Cr, or nearly 90% of FY26 expenditure, was attributable to fleet operator costs.
This means Porter must maintain:
- High vehicle utilisation
- Strong city-level density
- Efficient pricing
- Driver-partner availability
- Low customer acquisition costs
to continue expanding margins.
This is one of the most important factors investors should monitor.
Funding & Valuation
Porter raised approximately $200 million in Series F funding in May 2025, led by Kedaara Capital and Wellington Management, with participation from existing investor Vitruvian Partners.
The transaction valued Porter at approximately $1.1–1.2 billion, making Porter a unicorn. The round also included secondary transactions, with some early investors exiting partially or completely.
Funding Snapshot
| Round | Approx. Amount | Key Investors |
|---|---|---|
| Series F – 2025 | $200 Mn | Kedaara, Wellington, Vitruvian |
| Earlier investors | — | Tiger Global, Peak XV, Kae Capital, Lightrock, Vitruvian |
| Latest reported valuation | ~$1.1–1.2 Bn | Series F |
Current Unlisted Share Price & Valuation
Moneycontrol’s unlisted-share tracker currently shows an indicative price of approximately ₹2,960 per share, based on 83.83 million shares outstanding, implying a market capitalisation of approximately ₹24,813 Cr. It also shows no DRHP currently filed.
Indicative Valuation at ₹2,960
| Metric | Approx. |
|---|---|
| Share Price | ₹2,960 |
| Shares Outstanding | 8.38 Cr |
| Implied Market Cap | ₹24,813 Cr |
| FY26 Revenue | ₹6,650 Cr |
| FY26 PAT | ₹229 Cr |
| Price/Sales | ~3.7x |
| Price/Earnings | ~108x |
Important: The ₹2,960 figure is an indicative private-market/unlisted reference, not an NSE/BSE traded price. Private-market prices can vary significantly depending on transaction size, seller, buyer and liquidity.
Valuation Concern
There is a significant valuation gap between Porter’s latest institutional funding valuation of approximately $1.1–1.2 billion and the current unlisted-market indication of around ₹24,800 Cr.
At roughly ₹24,800 Cr, the implied valuation is substantially higher than the valuation reported at the 2025 Series F round.
Therefore, investors should not evaluate Porter only on its revenue growth. The entry valuation is now an important part of the investment thesis.
IPO Status
Porter does not currently have a confirmed IPO date or DRHP filing.
In August 2026, CEO and co-founder Uttam Digga said Porter was not in a hurry to go public and that management was focused on increasing market share and executing its business strategy rather than setting an IPO timeline. He also indicated that the company had been financially ready to go public earlier but chose to strengthen the business first.
Current IPO Position
IPO: Possible in the future
DRHP: Not filed
IPO Date: Not announced
Price Band: Not available
SEBI Approval: Not available
Therefore, Porter should currently be classified as an unlisted growth company with future IPO optionality, rather than a confirmed pre-IPO listing opportunity.
Investment Rationale
1. Exceptional Revenue Growth
Porter’s revenue increased from approximately ₹2,734 Cr in FY24 to ₹6,650 Cr in FY26.
That represents more than 2.4x growth in just two years.
2. Strong Profitability Inflection
The company moved from a loss of roughly ₹96 Cr in FY24 to:
₹55 Cr profit → ₹229 Cr profit
within two years.
This is one of the strongest aspects of the Porter story.
3. Large MSME Opportunity
India has millions of MSMEs with fragmented logistics requirements. Porter provides a technology layer that can make intra-city transportation more organized and accessible.
4. Asset-Light Model
Porter does not need to own an enormous vehicle fleet to scale its marketplace. It primarily connects customers with driver-partners.
This can allow the company to expand without the capital intensity associated with owning a large logistics fleet.
5. Multiple Revenue Channels
Porter has expanded beyond simple truck booking into:
- Enterprise logistics
- Packers & Movers
- Two-wheeler delivery
- Intercity logistics
- Technology-enabled transportation
This provides opportunities to increase customer lifetime value.
6. Strong Institutional Backing
Kedaara Capital, Wellington Management and Vitruvian Partners are among the major institutional investors, while earlier investors included Tiger Global and Peak XV.
The 2025 funding round also gave existing shareholders an opportunity for liquidity through secondary transactions.
Risks & Concerns
| Risk | Investor Concern |
|---|---|
| High Valuation | Current indicative valuation is substantially above the last institutional round |
| Thin Margins | FY26 EBITDA margin was only ~3.1% |
| Fleet Costs | Fleet operator costs account for the majority of expenses |
| Competition | Uber, Rapido, Delhivery and other logistics players are competing in adjacent segments |
| Private-Market Liquidity | Shares cannot be freely traded on NSE/BSE |
| IPO Uncertainty | No DRHP or confirmed IPO timeline |
| Driver Dependency | Service quality depends heavily on driver-partner availability |
| Pricing Pressure | Competition can limit the company’s ability to raise prices |
| Execution Risk | Maintaining >50% growth at a much larger revenue base will become increasingly difficult |
Porter – Positives vs Concerns
| Positives | Concerns |
|---|---|
| 50%+ revenue growth | Very high implied valuation |
| FY26 revenue ₹6,650 Cr | Low EBITDA margin |
| FY26 PAT ₹229 Cr | High fleet/operator costs |
| Two consecutive profitable years | Highly competitive market |
| Large MSME customer base | IPO timeline uncertain |
| Strong institutional investors | Unlisted liquidity |
| Asset-light technology model | Growth may normalize at scale |
| Expanding logistics ecosystem | Current valuation leaves less margin of safety |
Investment View
Porter is one of the more interesting profitable logistics companies in India’s unlisted startup ecosystem.
The strongest part of the story is the combination of:
High Growth + Rapid Profitability + Large MSME Opportunity + Technology Platform + Strong Institutional Investors
However, the current indicative unlisted valuation is the biggest concern.
At approximately ₹24,800 Cr implied market capitalisation, investors are paying a significant premium compared with Porter’s last reported $1.1–1.2 billion institutional valuation.
Therefore:
Business Quality: ⭐⭐⭐⭐½
Growth Potential: ⭐⭐⭐⭐⭐
Profitability Trend: ⭐⭐⭐⭐½
Competitive Position: ⭐⭐⭐⭐
Valuation Comfort: ⭐⭐
IPO Visibility: ⭐⭐½
Overall Unlisted Opportunity: High Growth / High Valuation
Investment View: Attractive business, but entry valuation needs careful consideration.
For long-term investors, Porter becomes significantly more compelling if future earnings growth continues to outpace valuation expansion. At the current private-market indication, investors should focus heavily on price paid, dilution, future IPO valuation and margin expansion, rather than simply buying because Porter is a unicorn.
Share Details
| Particular | Details |
|---|---|
| Company | SmartShift Logistics Solutions Pvt. Ltd. |
| Brand | Porter |
| CIN | U74999MH2014PTC306120 |
| ISIN | INE958W01015 |
| Face Value | ₹10 |
| Status | Unlisted |
| Indicative Price | ~₹2,960 |
| Indicative Market Cap | ~₹24,813 Cr |
| DRHP | No |
| IPO | No fixed timeline |
How to Invest
Porter shares are not available on NSE or BSE.
Unlisted shares are generally acquired through private-market transactions from existing shareholders or specialised unlisted-share intermediaries.
Investors should independently verify:
- Seller ownership
- ISIN
- Share certificate/demat details
- Transfer documentation
- Current valuation
- Applicable taxes
- Lock-in implications after a potential IPO
- Whether the quoted price reflects an actual executable transaction
Final Takeaway
Porter has evolved from a loss-making logistics startup into a rapidly growing and profitable logistics platform.
FY26 is particularly impressive:
₹6,650 Cr Revenue → ₹229 Cr Profit → 54% Revenue Growth → 4x Profit Growth
The business fundamentals are strengthening, but the valuation has also moved sharply upward.
For an unlisted investor, the key question is no longer simply:
“Is Porter a good company?”
It is:
“Is Porter a good company at the price I am paying?”
At the current indicative valuation, valuation discipline becomes critical.
Category: High-Growth Unlisted Logistics / Future IPO Candidate
Disclaimer
This report is for informational and educational purposes only and should not be considered investment advice, a recommendation, or an offer to buy or sell securities. Unlisted-share prices are indicative and may differ materially from actual transaction prices. Unlisted investments carry liquidity, valuation, regulatory, business and capital-loss risks. Investors should conduct their own due diligence and consult a SEBI-registered investment professional before investing.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
