
1. Company Overview
Cult.fit Limited, formerly known as CureFit Healthcare Private Limited, is an Indian fitness and active-lifestyle company founded in 2016 by Mukesh Bansal and Ankit Nagori.
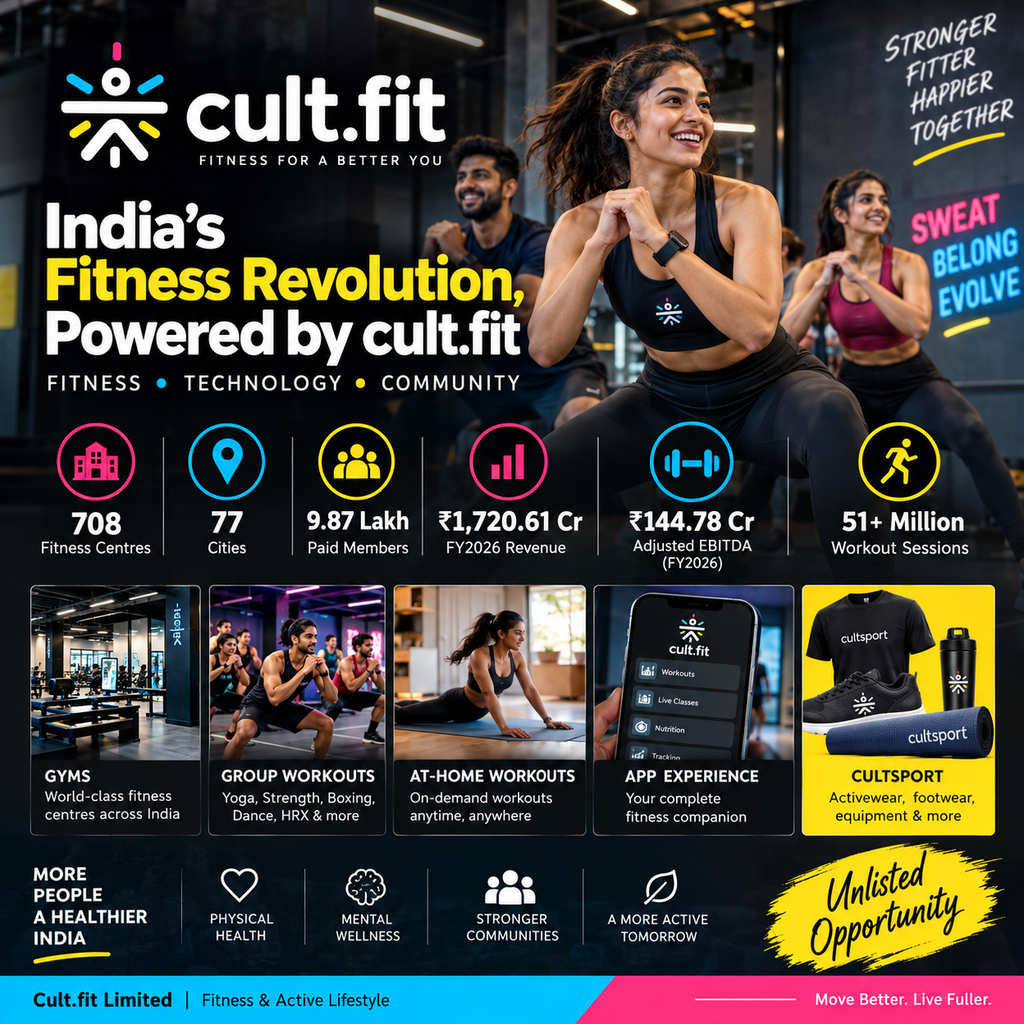
The company operates an integrated fitness platform combining gyms, trainer-led group workouts, at-home workouts, fitness memberships and fitness products through its Cult.fit app, website and offline network.
Its business is divided into two principal segments:
- Fitness Services
- Fitness Products
The company has built a large network of fitness centres across India and also operates the Cultsport fitness-products business. The company describes itself as a professionally managed company with no identifiable promoter under applicable regulations.
2. Company Details
| Particular | Details |
|---|---|
| Company | Cult.fit Limited |
| Former Name | CureFit Healthcare Private Limited |
| Incorporated | 2016 |
| CIN | U74999TN2016PLC176669 |
| Registered Office | Chennai, Tamil Nadu |
| Corporate Office | Bengaluru, Karnataka |
| Industry | Fitness & Active Lifestyle |
| Business Model | Fitness Services + Fitness Products |
| Current Status | Unlisted |
| Promoter | No identifiable promoter |
| Proposed Listing | BSE & NSE |
| IPO Fresh Issue | Up to ₹950 Cr |
| Proposed OFS | Up to 17.86 Cr shares |
| Face Value | ₹1 per share |
| DRHP Date | July 6, 2026 |
The DRHP was filed with SEBI in July 2026.
3. What Does Cult.fit Do?
Cult.fit is designed as an integrated fitness ecosystem rather than a conventional gym chain.
Fitness Services
The services business includes:
- Full-service gyms
- Trainer-led group workouts
- Yoga
- Strength training
- Boxing
- Dance-based workouts
- HRX workouts
- Pilates
- At-home online workouts
- Fitness memberships
- Corporate fitness programmes
Cult.fit also provides access to multiple fitness formats through its app and membership ecosystem.
Fitness Products
The products business operates primarily through Cultsport and includes:
- Activewear
- Sports footwear
- Fitness equipment
- Home workout equipment
- Recovery products
- Fitness accessories
Products are sold through online channels, exclusive brand outlets and other offline retail channels.
As of March 31, 2026, Cultsport products were available through 29 exclusive brand outlets across four cities in addition to other channels.
4. Cult.fit Fitness Network
As of March 31, 2026:
- 708 fitness centres
- 77 cities
- 594 centres integrated with the Cult.fit app
- 987,020 paid members
- 51+ million workout sessions
- 42.39 lakh fitness-product units sold
The fitness-centre network increased from 588 centres in FY2024 to 690 in FY2025 and 708 in FY2026. Paid members increased from approximately 6.91 lakh to 8.33 lakh and then 9.87 lakh over the same period.
5. Geographic Presence
Cult.fit has a strong presence in India’s major metropolitan fitness markets.
As of March 31, 2026:
| City / Region | Fitness Centres | Paid Members |
|---|---|---|
| Bengaluru | 247 | 385,430 |
| Hyderabad | 149 | 192,916 |
| Delhi-NCR | Part of top-four network | — |
| Mumbai Metropolitan Region | Part of top-four network | — |
The four major markets — Delhi-NCR, Mumbai Metropolitan Region, Bengaluru and Hyderabad — accounted for 563 centres, representing approximately 80% of the company’s total network.
These four cities contributed 90.44% of Cult.fit’s FY2026 fitness-services revenue, highlighting both the strength of its metropolitan franchise and the company’s geographic concentration.
6. Business Segments
Cult.fit operates through two reportable segments.
Fitness Services
FY2026 revenue:
₹1,197.83 Cr
Share of total revenue:
69.62%
FY2026 segment result:
₹210.08 Cr
Segment margin:
17.54%
Fitness Products
FY2026 revenue:
₹522.77 Cr
Share of total revenue:
30.38%
FY2026 segment result:
–₹57.37 Cr
Segment margin:
–10.97%
This creates an important distinction in the business model: fitness services were profitable at the segment level, while the products business remained loss-making in FY2026.
7. FY2026 Financial Performance
Cult.fit’s revenue has expanded significantly over the last three years.
| ₹ Crore | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Revenue from Operations | 926.66 | 1,215.54 | 1,720.61 |
| Adjusted EBITDA | (140.19) | (33.53) | 144.78 |
| Adjusted EBITDA Margin | -15.13% | -2.76% | 8.41% |
| PAT / Loss | (888.49) | (480.83) | (251.86) |
| Paid Members | 6.91 Lakh | 8.33 Lakh | 9.87 Lakh |
| Fitness Centres | 588 | 690 | 708 |
| Product Units Sold | 19.04 Lakh | 30.39 Lakh | 42.39 Lakh |
FY2026 revenue increased approximately 41.55%, while adjusted EBITDA moved into positive territory for the first time at approximately ₹144.78 Cr.
The company’s net loss reduced from approximately ₹480.83 Cr in FY2025 to ₹251.86 Cr in FY2026.
8. Profitability Improvement
One of the key developments in FY2026 was the improvement in operating profitability.
Adjusted EBITDA
FY2024: -₹140.19 Cr
FY2025: -₹33.53 Cr
FY2026: +₹144.78 Cr
Adjusted EBITDA Margin
FY2024: -15.13%
FY2025: -2.76%
FY2026: +8.41%
The services segment also improved substantially, with its segment margin moving from -1.13% in FY2024 to 17.54% in FY2026.
However, the company continued to report a consolidated net loss of ₹251.86 Cr in FY2026, meaning the transition to positive adjusted EBITDA has not yet translated into consolidated PAT profitability.
9. Operating Metrics
The growth in operating scale has been accompanied by higher customer engagement.
| Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Paid Members | 6.91 Lakh | 8.33 Lakh | 9.87 Lakh |
| Fitness Centres | 588 | 690 | 708 |
| Product Units Sold | 19.04 Lakh | 30.39 Lakh | 42.39 Lakh |
| App-integrated Centres | 486 | 583 | 594 |
The company also reported a 50.88% member retention rate in FY2026, compared with 45.87% in FY2025.
10. Industry Opportunity
According to the Redseer industry report cited in Cult.fit’s DRHP, India’s fitness-services market was estimated at approximately:
₹25,600 Cr in CY2025
The market is projected to reach approximately:
₹48,700–₹53,100 Cr by CY2030
representing an estimated 14–16% CAGR.
The broader fitness and active-lifestyle products market was estimated at approximately ₹1.16 lakh Cr in CY2025 and is projected to reach approximately ₹2.18–₹2.35 lakh Cr by CY2030, also implying approximately 14–16% CAGR.
Key Industry Drivers
- Increasing health awareness
- Rising disposable income
- Growing urban population
- Greater focus on preventive health
- Increasing participation in organised fitness
- Expansion beyond traditional gyms
- Digital fitness adoption
- Growth in sportswear and fitness equipment
- Corporate wellness programmes
11. Cult.fit’s Competitive Advantages
1. Large Fitness Network
With 708 centres across 77 cities, Cult.fit has built substantial physical distribution.
2. Integrated App
The Cult.fit app connects memberships, bookings, workouts and digital fitness services.
3. Asset-Light Franchise Model
The company is increasingly using franchising and marketplace models to expand its network without carrying the entire capital burden of every centre.
4. Strong Brand
The Cult.fit brand has established recognition in India’s organised fitness market.
5. Services + Products Ecosystem
The combination of memberships and Cultsport products allows the company to cross-sell between fitness consumers and product categories.
6. Technology & Data
The company uses technology and customer data to support fitness programming, member engagement, centre operations and product development.
The DRHP specifically identifies franchise-led expansion, technology, brand strength, omnichannel product distribution and synergies between services and products among its business strengths.
12. Major Brands & Formats
Cult.fit’s ecosystem includes several fitness formats and brands, including:
- Cult Elite
- Cult Neo
- Cult Play
- Cultsport
- Fitness First
- Gold’s Gym India
- Pilates Circle
Cult.fit acquired the master franchise rights for Gold’s Gym in India, Nepal and Bangladesh as part of its expansion into the broader fitness ecosystem.
13. Management
Mukesh Bansal
Co-founder, Managing Director & Executive Chairman
Mukesh Bansal is also known for co-founding Myntra.
He remains an important shareholder and executive chairman, although day-to-day operations are led by the professional management team.
Naresh Krishnaswamy
Whole-time Director & CEO
Naresh Krishnaswamy leads the company’s operating strategy and execution.
The company has also strengthened its board ahead of the proposed IPO with independent directors including Kalpana Morparia, Arun M. Kumar, Indu Bhushan and Pragya Misra.
14. Major Investors / Shareholders
Cult.fit has attracted a number of institutional and strategic investors.
Major shareholders disclosed around the IPO process include:
| Shareholder | Approx. Stake |
|---|---|
| MacRitchie Investments / Temasek | 20.32% |
| Accel | 13.45% |
| Mukesh Bansal | 8.35% |
| Kalaari Capital | 7.80% |
| Fitness First Luxembourg | 6.81% |
| Eternal | 4.88% |
| Tata Digital | 3.58% |
The company is professionally managed and has no identifiable promoter under the SEBI framework.
15. Temasek Investment
In March 2026, Temasek affiliate MacRitchie Investments Pte. Ltd. invested approximately ₹440 Cr through a Series G CCPS issuance.
The DRHP records the issuance of approximately 90.98 lakh Series G CCPS at ₹483.62 per preference share.
The transaction is relevant because it represents a recent institutional capital event ahead of the proposed IPO.
16. Last Reported Valuation
According to Tracxn data cited by financial media, Cult.fit was last valued at approximately:
₹12,600 Cr
or around US$1.5 billion, following its Series G financing round in March 2026.
This should be treated as a historical private-market valuation, not as the company’s current IPO valuation or an implied fair value for its unlisted shares. The final IPO valuation will depend on the eventual offer price and share count.
17. IPO Details
Cult.fit filed its Draft Red Herring Prospectus dated July 6, 2026 with SEBI.
The proposed IPO consists of:
| IPO Component | Proposed Size |
|---|---|
| Fresh Issue | Up to ₹950 Cr |
| Offer for Sale | Up to 17.86 Cr shares |
| Pre-IPO Placement | Up to ₹190 Cr |
| Proposed Exchanges | BSE & NSE |
| Face Value | ₹1 |
| Price Band | Not announced |
| IPO Dates | Not announced |
If the pre-IPO placement is completed, the amount raised through it will reduce the fresh issue size.
18. Offer for Sale – Major Selling Shareholders
The DRHP identifies several selling shareholders.
| Selling Shareholder | Shares Offered – Up to |
|---|---|
| MacRitchie Investments | 2.47 Cr |
| Fitness First Luxembourg | 1.96 Cr |
| IDG Ventures India Fund III | 1.70 Cr |
| Mukesh Bansal | 1.60 Cr |
| Tata Digital | 1.59 Cr |
| Chiratae Trust | 1.11 Cr |
| Bruno Eduard Raschle | 1.02 Cr |
| Schroders Capital | 99.15 Lakh |
| Twenty Nine Capital Partners | 79.12 Lakh |
| Accel India V | 65.32 Lakh |
Actor Hrithik Roshan is also disclosed as a selling shareholder, with up to approximately 6.33 lakh shares proposed to be sold.
19. Use of IPO Proceeds
The proposed fresh issue proceeds are intended to be deployed across expansion, existing-centre obligations, debt repayment and marketing.
| Purpose | Amount |
|---|---|
| New Cult Elite & Cult Neo Centres | ₹276.60 Cr |
| Lease/Rent/License Payments | ₹217.50 Cr |
| Debt Repayment / Prepayment | ₹120.00 Cr |
| Brand Marketing & Promotion | ₹75.00 Cr |
| Cultsport New EBOs | ₹23.40 Cr |
| General Corporate Purposes | Balance |
The company may also undertake a pre-IPO placement of up to ₹190 Cr before filing the RHP.
20. Key Growth Drivers
Expansion of Fitness Network
Cult.fit plans to add more centres, particularly through Cult Elite and Cult Neo formats.
Franchise-led Expansion
The franchise model allows the company to expand its geographic footprint with comparatively lower capital requirements.
Membership Growth
Paid members increased from 6.91 lakh in FY2024 to 9.87 lakh in FY2026.
Digital Fitness
The app provides a digital layer across physical and at-home fitness services.
Cultsport
The products business creates an additional revenue stream from apparel, footwear, equipment and accessories.
Corporate Wellness
Corporate memberships provide another channel for acquiring and retaining fitness users.
Improving Unit Economics
The move of the services segment to a 17.54% segment margin in FY2026 is an important operating development.
21. Key Risks
1. Member Retention
Fitness memberships are subscription-driven. Failure to acquire and retain customers can directly affect revenue.
2. Geographic Concentration
The top four cities generated approximately 90.44% of fitness-services revenue in FY2026.
3. Continued Net Losses
Despite positive adjusted EBITDA, the company reported a consolidated loss of approximately ₹251.86 Cr in FY2026.
4. Cultsport Losses
The products segment remained loss-making, with a FY2026 segment loss of approximately ₹57.37 Cr.
5. Brand Risk
Cult.fit operates a consumer-facing brand where service quality, customer experience and reputation are important.
6. Franchise & Marketplace Risk
The company does not have complete operational or financial control over franchise and marketplace centres.
7. Goodwill & Intangible Assets
The company carries significant goodwill and intangible assets that may be subject to impairment.
8. Import & Supply-Chain Risk
Some fitness products are sourced from overseas suppliers, exposing the business to currency, logistics and geopolitical risks.
9. Competitive Environment
Cult.fit competes with organised gym chains, fitness aggregators, independent gyms, sports brands and online fitness platforms.
10. IPO Valuation Risk
The company is still loss-making at the PAT level. The eventual IPO valuation will therefore be important in determining how investors assess the company’s growth relative to its profitability.
22. Unlisted Investment Perspective
Cult.fit represents an interesting consumer fitness + technology + active lifestyle business rather than a conventional gym operator.
Key factors investors may monitor include:
- 708 fitness centres
- 77-city network
- 9.87 lakh paid members
- ₹1,720.61 Cr FY2026 revenue
- 41.55% FY2026 revenue growth
- ₹144.78 Cr adjusted EBITDA
- 8.41% adjusted EBITDA margin
- ₹251.86 Cr FY2026 net loss
- 17.54% FY2026 services segment margin
- 69.62% revenue contribution from services
- 30.38% revenue contribution from products
- Strong institutional investor base
- Proposed ₹950 Cr fresh issue
- Proposed 17.86 Cr-share OFS
- Proposed BSE/NSE listing
- Reported last private valuation of approximately ₹12,600 Cr
For an unlisted investor, the major variables to compare are entry valuation, IPO valuation, membership growth, centre economics, services profitability, Cultsport losses, cash generation and the final IPO price band.
23. IPO Status – September 2026
| Parameter | Status |
|---|---|
| Company | Cult.fit Limited |
| Current Status | Unlisted |
| DRHP Filed | Yes |
| DRHP Date | July 6, 2026 |
| Fresh Issue | Up to ₹950 Cr |
| OFS | Up to 17.86 Cr shares |
| Pre-IPO Placement | Up to ₹190 Cr |
| Proposed Listing | BSE & NSE |
| Price Band | Not announced |
| IPO Opening Date | Not announced |
| Listing Date | Not announced |
| Identifiable Promoter | No |
| Last Reported Private Valuation | ~₹12,600 Cr |
SEBI’s public-issue filing confirms the Cult.fit DRHP was filed in July 2026. The DRHP itself states that the price band and bid dates were yet to be determined at that stage.
24. Company Snapshot
| Parameter | Cult.fit Limited |
|---|---|
| Sector | Fitness & Active Lifestyle |
| Founded | 2016 |
| FY26 Revenue | ₹1,720.61 Cr |
| FY26 Revenue Growth | 41.55% |
| FY26 Adjusted EBITDA | ₹144.78 Cr |
| FY26 EBITDA Margin | 8.41% |
| FY26 Net Loss | ₹251.86 Cr |
| Paid Members | 9.87 Lakh |
| Fitness Centres | 708 |
| Cities | 77 |
| App-integrated Centres | 594 |
| FY26 Services Revenue | ₹1,197.83 Cr |
| FY26 Products Revenue | ₹522.77 Cr |
| Proposed Fresh Issue | ₹950 Cr |
| Proposed OFS | 17.86 Cr shares |
| Proposed Listing | NSE & BSE |
| Current Status | Unlisted |
| Promoter | No identifiable promoter |
| Major Institutional Investor | Temasek / MacRitchie |
25. Important Links
Official Cult.fit Website:
Cult.fit – Official Website
Cult.fit Services:
Cult.fit Fitness Services
SEBI – Cult.fit DRHP:
SEBI – Cult.fit DRHP / Abridged Prospectus
Goldman Sachs – Cult.fit DRHP:
Goldman Sachs – Cult.fit IPO Documents
Cult.fit App:
Cult.fit App – Google Play
Cult.fit on UnlistedCart:
Cult.fit Limited – UnlistedCart
26. Disclaimer
This report is prepared for informational and educational purposes only and should not be construed as investment advice, an offer to buy or sell securities, or a guarantee of future returns.
Cult.fit Limited is currently unlisted. Its proposed IPO, issue size, OFS, price band, IPO dates, valuation and other terms may change before the final offer document.
Financial figures and business information have been compiled from the company’s DRHP, SEBI disclosures, company sources and reputable secondary sources. Investors should independently review the latest regulatory filings, financial statements, valuation and applicable transaction documents before making any investment decision.
Unlisted and pre-IPO investments involve liquidity risk, valuation risk, regulatory risk and limited price discovery. Past financial performance does not guarantee future performance.
For more such unlisted stocks visit:
UnlistedCart – Unlisted Shares
